Bitget UEX Daily | Oil Prices Break $100, US Stocks Fall for Four Consecutive Days; Oracle Cloud Infrastructure Revenue Surges 121%; Apple Bucking the Trend Rises 3.56%

I. Hot News
Federal Reserve Developments
US PPI Year-on-Year Rises to 5.4%, Tonight's CPI Will Again Test Risk Assets
- US August PPI increased 0.4% month-on-month, higher than July's revised 0.1%; year-on-year rose 5.4%.
- Energy prices increased 4.2% month-on-month, serving as the primary driver of goods price increases; core PPI (excluding food, energy, and trade services) rose 0.3% month-on-month.
- The US August CPI will be released tonight at 20:30, while the Federal Reserve will hold its interest rate decision meeting on September 15–16 local time, accompanied by the Summary of Economic Projections.
Market Impact: Rising energy costs are increasing corporate expenses, and the market needs to assess whether this pressure will further transmit to consumers. If the CPI continues to show price pressures, high-valuation tech stocks and crypto assets could face higher interest rate hurdles; if core inflation cools, it may help ease tensions ahead of the policy meeting.
International Commodities
Rising Red Sea Shipping Risks Expand Crude Supply Concerns
- According to Xinhua citing Yemeni government military officers, Houthi forces captured the Red Sea port city of Mokha on September 10.
- Markets are monitoring whether the conflict will further impact the Bab el-Mandeb Strait and regional energy export routes, while existing shipping risks through the Strait of Hormuz remain unresolved.
- Houthi forces state that international navigation remains safe, but maritime security experts have warned of rising regional sea risks.
Market Impact: Supply and transportation uncertainties are supporting crude risk premiums and raising cost pressures for aviation, logistics, and manufacturing. For US equities, sustained high oil prices simultaneously affect corporate profit margins and inflation expectations, making energy shocks an important variable in cross-asset pricing.
Macroeconomic Policy
US Treasury Buys Back Approx. $5.187 Billion in Long-Term Bonds, Bond Market Remains Under Pressure
- The US Treasury completed liquidity support buybacks of remaining-term 10-to-20-year Treasuries, with an actual scale of approximately $5.187 billion, below the $6 billion operational ceiling.
- Treasury Secretary Bessent stated that buybacks depend on appropriate pricing and downplayed market concerns over the operation's scale.
- Following the buyback, selling pressure on US Treasuries has not subsided, with energy prices and inflation outlooks continuing to influence long-term yields.
Market Impact: The buyback improves liquidity for some outstanding Treasuries, but it is unlikely to single-handedly offset pressures from inflation and financing demand. Capital-intensive sectors like AI data centers and real estate still face constraints on investment returns from higher financing costs.
II. Market Review
Commodities & Forex Performance
- Spot Gold: approx. $4,316.82/oz.
- Spot Silver: approx. $63.58/oz.
- WTI Crude Futures: benchmark quote approx. $103.04/bbl, October 2026 contract.
- Brent Crude Futures: benchmark quote approx. $108.27/bbl, November 2026 contract.
- US Dollar Index (DXY): approx. 99.08 points.
Driver Analysis: Both major crude benchmarks remain above $100, with transportation risks in the Red Sea and Gulf regions becoming the focal point of the energy market.Gold faces both safe-haven demand and upward interest rate pressures, while a stronger dollar further increases headwinds for precious metals. Tonight's CPI release will test whether energy costs are transmitting to broader consumer prices.
Crypto Performance
- BTC: approx. $76,901.67 USDT, down 1.57% in 24 hours.
- ETH: approx. $2,456.68 USDT, down 0.35% in 24 hours.
- Total Crypto Market Cap: approx. $2.71 trillion.
Driver Analysis: Both BTC and ETH declined over the past 24 hours, with ETH showing relative resilience. Rising oil prices and inflation pressures keep interest rate outlooks in play for risk sentiment; the revised draft of the CLARITY Act and next week's procedural vote add regulatory focus, though legislative progress must still be separated from actual capital inflows.
US Equity Index Performance
- Dow Jones Industrial Average: closed at 52,064.10, down 0.60%.
- S&P 500: closed at 7,591.70, down 0.58%.
- Nasdaq Composite: closed at 26,081.72, down 0.65%.
Tech Giants Developments
- NVDA: $218.36, down 2.37%.
- AAPL: $326.57, up 3.56%.
- MSFT: $492.44, up 0.16%.
- GOOGL: $332.60, up 0.59%.
- AMZN: $251.89, down 0.20%.
- META: $644.38, down 1.42%.
- TSLA: $363.56, down 1.16%.
Performance Summary & Driver Analysis: Based on Alphabet Class A shares, three of the Magnificent Seven advanced while four declined. Apple led gains following its foldable display product launch, with Microsoft and Google posting modest gains; NVIDIA led declines, while Meta reversed part of the previous day's gains. Oil and rate pressures suppressed overall risk appetite, and news of Microsoft's data center expansion alongside Google's TPU procurement expectations failed to trigger a broad tech rally. Markets continue to differentiate between business growth opportunities and capital expenditure costs.
Sector Movement Observations
Memory Chips: Retreat After Previous Day's Rally, Rate Pressures Weigh on AI Hardware Valuations
- Representative Stocks: Micron (MU) down 4.90%, SanDisk (SNDK) down 4.06%.
- Drivers: Accelerating month-on-month PPI and crude breaking $100 heightened market concerns over higher rates. Both memory stocks reversed previous gains, indicating industry pricing power remains insufficient to offset macro pressures. Future attention should focus on order fulfillment and earnings forecast revisions.
Consumer Electronics: Apple Strengthens Against the Trend, Foldable Sales Expectations Take Focus
- Representative Stock: Apple (AAPL) up 3.56%.
- Drivers: Following the iPhone Duo launch, markets are assessing Apple's incremental opportunity entering the foldable display market. TrendForce forecasts shipments of approx. 5 million units for this model in 2026; the product cycle catalyst supported Apple outperforming the broader market that day. This figure represents institutional estimates and still requires validation through bookings and deliveries.
III. US Stock In-Depth Analysis
1. Oracle (ORCL) - 121% Growth in Cloud Infrastructure Revenue, Order Fulfillment Runs Parallel to Capital Expenditures
Event Overview: Oracle fell 5.38% in regular trading on Sept 10, closing at $152.94. After-hours release for Q1 FY2027: revenue approx. $19.3 billion, up 30% YoY; cloud infrastructure revenue approx. $7.4 billion, up 121% YoY; adjusted EPS $1.92. As of 19:59 ET, after-hours quote $159.26, up 4.13% from regular close.
Market Interpretation: Remaining performance obligations reached $664 billion, and full-year adjusted EPS guidance was raised to $8.10, reflecting strong AI cloud demand. However, capex for the quarter stood at approx. $28.5 billion, signaling substantial cash deployment. The core valuation question hinges on whether this massive contract backlog can be timely converted into revenue, cash collection, and reasonable returns.
Investment Implications: Monitor new data center deliveries, customer prepayments, and subsequent cash flows. Whether regular trading tonight sustains the after-hours reaction will test if improved earnings sufficiently alleviate financing and capex concerns.
2. Apple (AAPL) - 3.56% Gain Against the Trend, Foldables Enter Sales Verification Phase
Event Overview: Apple rose 3.56% on Sept 10, closing at $326.57. The first foldable iPhone Duo launches in the US starting at $1,999, with pre-orders opening Oct 16 and general availability on Oct 23. Post-launch, investors are reassessing high-end upgrade demand and the competitive landscape for foldables.
Market Interpretation: TrendForce forecasts approx. 5 million units shipped for the Duo this year, accounting for approx. 24.8% of the global foldable phone market. This refers to 2026 shipment projections. For Apple, the key question is whether new purchases will cover higher component costs and how much they substitute for existing high-end models; gaining market share does not directly equate to margin improvement.
Investment Implications: Monitor pre-order volumes, delivery timelines, and product gross margins. The stock has already priced in positive sentiment around the new product; future sustainability requires actual demand to validate earnings expectations.
3. Adobe (ADBE) - Earnings Beat Expectations, But Q4 Guidance Caps Price Reaction
Event Overview: Adobe fell 2.37% in regular trading on Sept 10, closing at $248.83. After-hours reported Q3 revenue of $6.76 billion, up 13% YoY, with non-GAAP EPS of $6.13; the company raised full-year non-GAAP EPS guidance to $24.45–$24.50. As of 19:59 ET, after-hours quote $242.99, down 2.35% from regular close.
Market Interpretation: The company disclosed AI-first annual recurring revenue grew over 150% YoY, yet Q4 revenue guidance of $6.8B–$6.85B comes in slightly below consensus. Investors are looking beyond AI product growth rates to absolute revenue contribution, paid conversion rates, and the cost of expanding user coverage.
Investment Implications: Track AI-related revenue size, subscription growth, and profitability. Simultaneous guidance upside and after-hours downside indicate that earnings growth must surpass market expectations for the upcoming period to sustain momentum.
IV. Market & Project Updates
1. US Senate Republicans unveiled a revised draft of the CLARITY Act, proposing that DeFi protocols failing to meet decentralization criteria register with the CFTC, subject to rulemaking by relevant agencies. The initial procedural vote is expected on Sept 15 local time; the amended proposal has not yet become enacted law.
2. Kalshi reportedly plans to seek regulatory approval to launch regulated perpetual futures linked to individual stocks such as Tesla, Apple, and NVIDIA. The project remains in the planning stage and should not be construed as an approved or live product.
3. Based on Hyperliquid's trade.xyz announced the launch of an Events marketplace, debuting Up/Down event contracts covering equities, commodities, and Pre-IPO assets. The platform states contract outcomes will be determined by XYZ market prices, further expanding event trading scenarios within unified accounts.
V. Today's Market Calendar
Data Release Schedule
All times are in Beijing Time (UTC+8); market attention levels reflect editorial assessment for this issue.
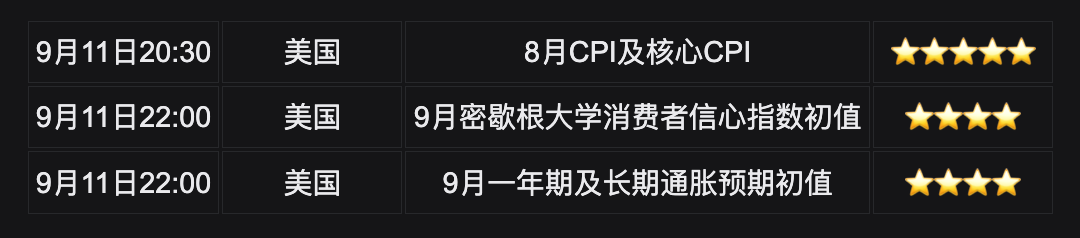
Key Event Preview
- Oracle and Adobe After-Hours Trading: Regular US equity trading tonight will continue to digest earnings from both companies, focusing on divergent market pricing for AI cloud growth, software paid conversions, and capex.
- Fed Rate Decision Meeting: Scheduled for Sept 15–16 local time, accompanied by the Summary of Economic Projections. Watch for interest rate decisions and shifts in inflation forecasts.
- CLARITY Act: Initial procedural vote expected on Sept 15 local time. Monitor the revised draft text and legislative progress.
Institutional Views:
As reported on Sept 11, Krishna Guha's team at Evercore ISI believes Treasury buybacks have limited impact, as the Treasury cannot indefinitely prevent fundamental factors from determining long-term yields. Meanwhile, TD Cowen analyst Derrick Wood cautioned ahead of Oracle's earnings that financing demands, component costs, and data center construction progress are key sources of market concern. These two perspectives separately highlight interest rate environment and project execution risks; future assessments will rely on combining new data with earnings fulfillment.
Disclaimer: The above content is provided for market information reference only and does not constitute any investment advice. Quotes fluctuate with market conditions; please refer to real-time market prices during trading.