


The GENIUS Act Final Rules Unveiled: The U.S. Co-opts Crypto Liquidity, Who Stole Your Stablecoin Interest?
Author: TechFlow
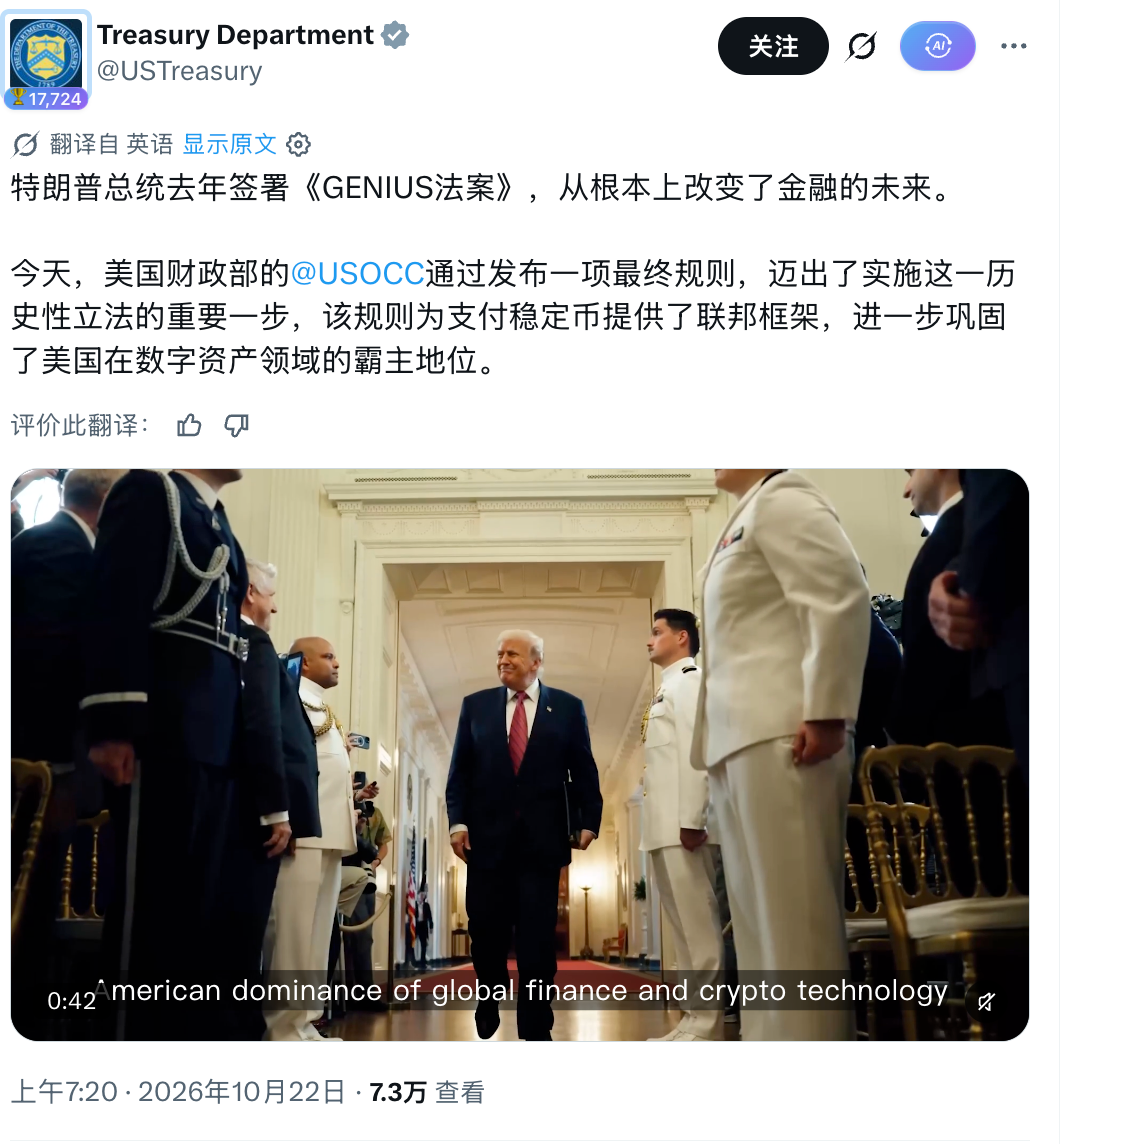
TechFlow Summary: Recently, the U.S. Department of the Treasury and the OCC (Office of the Comptroller of the Currency) officially released the final regulatory rules for the GENIUS Act governing payment stablecoins. Within the official U.S. narrative, this is hailed as a historic step toward establishing American global dominance in the digital asset sector.
But if you turn over this regulatory playbook set to take effect in January 2027, you will find it is far more than an “industry protection guide.” It is an extremely precise national resource allocation strategy: through regulatory shackles, it aims to completely convert hundreds of billions in crypto liquidity into the most loyal buyer base for U.S. Treasuries. Meanwhile, under the guise of “risk prevention,” it legally cuts off the interest-generating channel for ordinary token holders. In this collusion between U.S. regulators and Wall Street institutions, the cost of compliance may ultimately be borne by retail investors in the secondary market.
OCC Finalizes Federal Regulatory “Straitjacket”
To understand the true nature of this regulatory game, we first need to review the timeline of the bill’s implementation.
Signed by President Trump in July 2025, the GENIUS Act represents the first federal-level regulatory framework for payment stablecoins in the United States. Recently, the OCC (Office of the Comptroller of the Currency, hereinafter referred to as the OCC) officially released the final implementation rules for the bill, confirming that they will take effect on January 18, 2027.
In contrast to the ambiguity of previous proposals, the final rules implemented by the OCC this time lay out three hard-and-fast mandates:
First, 1:1 high-quality asset reserves: Behind every stablecoin must be legitimate cash and U.S. Treasuries or other qualifying assets.
Second, an absolute “interest ban”: It explicitly prohibits paying interest solely based on users holding stablecoins.
Third, a circuit breaker mechanism for bank runs: If daily redemption volume exceeds 10% of the total circulating supply, it must be reported immediately, and regulatory authorities will decide whether to allow deferred processing.
On the surface, these three rules appear designed to protect system stability. But if you dig deeper following the money flow (Follow the Money), you will uncover the commercial and macroeconomic logic behind them.
Turning Crypto Liquidity into a “Cash Machine” for U.S. Treasuries
Why is the Treasury Department so invested in this bill, even stepping forward publicly on Twitter to endorse it?
The author believes the answer lies within the “1:1 high-quality asset reserve” requirement.
In the traditional crypto space, reserve assets for certain stablecoins have always been opaque black boxes. The GENIUS Act sets clear rules at the federal level: if you want to obtain a license to issue tokens in the U.S., your underlying assets must straightforwardly purchase U.S. Treasuries or cash.
The current global stablecoin market cap is nearing $200 billion. As compliance frameworks take root and traditional financial institutions rush in, this reservoir will expand exponentially. For the U.S. government, this effectively establishes a massive, fully controlled “statutory U.S. Treasury buying mechanism” within the crypto ecosystem. In essence, this is less about regulation and more about converting crypto liquidity into the most stable buyer base for U.S. Treasuries.
The End of the “Risk-Free Wealth Management” Dividend for U.S. Retail Investors?
This is bearish news for beneficiaries of certain stablecoin wealth management products.
Currently, yields on short-term U.S. Treasuries are highly attractive. Issuers (such as Circle) use user funds to buy Treasuries, earning billions in risk-free interest annually. However, the OCC’s final rules explicitly prohibit returning this revenue to users directly in the form of “token holdings interest.”
What does this mean? It means that in the compliant U.S. market, stablecoin issuers will monopolize all yield generated from underlying assets, while the burden of fiat currency inflation falls squarely on retail investors.
Furthermore, this directly signals the end of the “high-yield stablecoin wealth management” dividend offered by certain CEXs (centralized exchanges). For regulated entities seeking U.S. licenses (such as Coinbase and the USDC ecosystem), the high-yield wealth management channels will be completely shut down.
The OCC has explicitly stated that while third-party or exchange reward arrangements are not automatically deemed violations, regulators will gradually scrutinize whether they constitute circumvention. This stringent compliance pressure will force regulated platforms to proactively cut off retail access to interest-generating channels.
DeFi May Become the Last Fortress for Stablecoin Yield
The GENIUS Act restricts “issuer distributions based on Treasury reserves,” but it cannot stop pure market lending demand.
In the DeFi world, decentralized lending protocols like Aave and Compound derive their stablecoin APY from actual on-chain borrowers (e.g., leveraged crypto traders) paying interest, or from trading fees based on AMM mechanisms.
This organic yield, driven by “actual market supply and demand,” is difficult to classify legally as “disguised issuer distributions.” Therefore, as certain CEXs can no longer offer attractive stablecoin wealth management products, retail and institutional investors seeking to hedge against inflation and secure stable returns will have no choice but to deposit compliant stablecoins like USDC into DeFi protocols.
In other words, while the GENIUS Act’s “interest ban” harvests retail investors, it is highly likely to accidentally serve as a catalyst for the on-chain DeFi explosion. Under the squeeze of compliance regulations, DeFi lending and liquidity pools will instead absorb overflow capital, driving a passive surge in TVL.
Polarization Between Compliance and Offshore Markets
Overall, the GENIUS Act is not attempting to strangle stablecoins; it is simply “redistributing stablecoin profits.” While establishing the dominance of the dollar system over the crypto world, it simultaneously completes the legal harvesting of retail risk-free yields.
The future stablecoin market will face complete fragmentation:
On one side are highly regulated compliant stablecoins governed by the U.S.: incredibly secure, favored by Wall Street institutional capital, but offering zero token-holding yields to retail investors;
on the other are offshore exchanges entirely operating outside the U.S. and offshore stablecoins (such as USDT). As long as they avoid U.S. licensing, they theoretically can continue providing retail investors with liquid yields through market making or on-chain protocols.
When “absolute compliance” means bearing risk without sharing profits, the vote-with-your-feet migration of tens of billions in capital between “U.S. licenses” and “high interest rates” is only just beginning.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 深潮TechFlow
















