


The Other Side of bStocks: Instead of Building a Better Nasdaq, Carving Out a Path to Pricing Power Through Perpetual Contracts
Author: WuBlockchain
Translated by: TechFlow
TechFlow Guide: Binance is using perpetual contracts to seize pricing power during US stock market closure. This isn't simply a 7×24 stock trading model; it's a battle over market structure centered on "who prices first." For traders, understanding this gameplay means seeing the next battlefield where traditional finance and crypto markets merge.

Lu Xun once said, "Don't try to be better, try to be different." If the ultimate goal is to gain pricing power over the underlying assets, there's no need to clash head-on on Nasdaq's strongest front. Instead, shift the battlefield to where we excel: perpetual contracts, 7×24 trading, leverage, on-chain inventory, and decentralized market makers coexisting with retail and institutions.
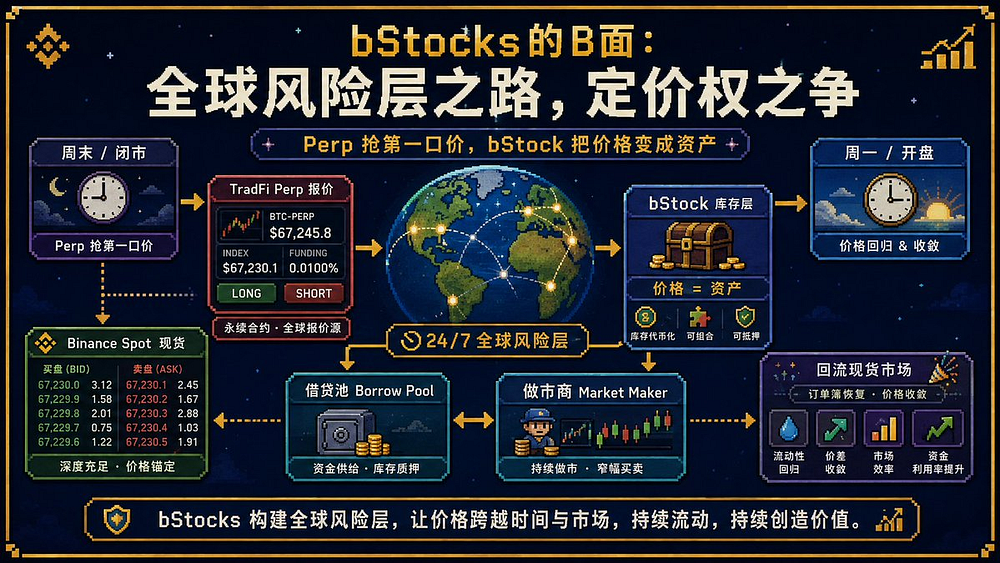
Seize the high ground of price discovery with perpetual contracts, absorb inventory and correct mispricing with bStocks, and ultimately gain pricing power.
When the Chicago Board of Trade (CBOT) was established in 1848, it was not yet the massive futures exchange it later became. Chicago was then rising as the grain hub of the American Midwest, with railroads and canals bringing boatloads and train cars of wheat and corn into the city.
The problem was that wheat wasn't a standardized commodity. Even though it was all called wheat, harvests from different farms and years weren't necessarily the same product. If buyers couldn't even know what they were buying, it would be hard to form a unified market price. One of CBOT's earliest moves was to turn this chaos into tradable standards. After receiving authorization from the State of Illinois in 1859, CBOT established a grain grading system and assigned inspectors to evaluate quality. By 1865, margin requirements and delivery rules began to become institutionalized.
This might sound less like financial innovation and more like warehouse management, but it was precisely those warehouses that changed market structure.
Once grains entered large silos, buyers no longer needed to ask which farm a single bag of wheat came from. The market began trading according to standardized grades, such as wheat of a certain standard grade. The Federal Reserve, reviewing this history, noted that grading and standardized warehousing let buyers know what they were purchasing, reduced transaction costs, and created the necessary conditions for liquid markets to form.
With these in place, futures truly arrived.
Farmers could sell future harvests in advance, grain merchants could procure future supplies, and speculators could bet on future prices without having to move thousands of bushels of wheat home. CBOT gradually evolved from early forward contracts and "arrival" contracts into standardized futures. By the late 19th century, Chicago grain futures had begun to fulfill the functions of price discovery, risk management, and transparent quoting.
Here lies a point easily overlooked.
Futures ultimately grew the fastest and attracted the largest trading volume, but what kept them from devolving into gambling detached from physical commodities was the network of grain elevators behind them.
In a weekend in August 2026, perpetual contracts for NVDA, TSLA, SNDK, and SKHY on Binance collectively generated approximately $461 million in trading volume. On Sunday, the trading prices of these four perpetual contracts were all higher than their respective spot market closing prices from the previous session. However, when the US spot market opened on Monday, all four stocks opened lower. Just SNDK's perpetual contract generated about $338 million in trading volume that weekend. Its Friday spot closing price was $1,212.21, it traded at $1,223.98 on Binance on Sunday, and Monday's spot opening dropped to $1,203.41.
The same SNDK contract gave a different answer during the US Independence Day long weekend a month prior. The spot market closed at $1,745, but SNDK traded as high as $1,841.88 on Binance on Sunday. When the spot market reopened on Monday, it opened at $1,828.68, creating a gap-up of about 4.8%. Binance's weekend pricing anticipated most of the move, although the final opening price didn't rise quite that high.
The same product predicted a significant Monday gap-down in one instance, and completely guessed wrong in direction after generating hundreds of millions in volume in another. This pushes the discussion around 7×24 stock trading beyond mere extended hours, straight into market structure: trading volume does not equal pricing power.
If Binance only wanted users to trade stocks on Saturdays, extending trading hours would suffice. But when Direct Stock, TradFi Perps, and bStocks are viewed together, a different structure emerges. After the spot market closes, perpetual contracts absorb directional trades, leverage, and high-frequency activity. bStocks provide stock inventory that can be held, transferred, pledged, and hedged. Chain-based protocols bring capital from outside centralized exchanges. When traditional stock markets reopen, the question becomes: will the US stock market accept the price formed by this 7×24 market?
This article does not debate whether bStocks are merely another form of tokenized stocks. It answers a different question: if Binance wants to establish the first price after traditional stock markets close, why should perpetual contracts serve as the engine, and why should bStocks become the inventory and correction layer?
I. What Binance is competing for isn't two extra trading days, but post-market prices
Stock markets have time gaps. After New York closes at 4 PM on Friday, companies continue releasing news, macro policies continue changing, supply chains continue evolving, and wars and politics do not wait for Nasdaq to reopen. Capital continues to reprice these stocks, but these views cannot yet enter the official order books of the US spot stock market.
So the issue isn't a lack of information, but rather where market participants can express that information via positions once it appears. If a market can absorb equity risk when NYSE, Nasdaq, KOSPI, and HKEX are all closed, it has the opportunity to perform price discovery before the underlying spot market reopens.
Binance's three products naturally assume three distinct roles. Direct Stock handles actual securities, corporate actions, and connections to traditional markets. bStocks transform stocks into assets that can be held, converted, transferred across chains, and used as collateral. TradFi Perps provide long/short exposure, leverage, and continuous trading.
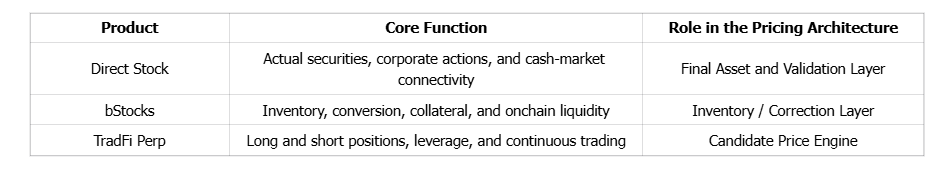
If the goal is to become the primary source of price discovery, perpetual contracts are better suited than bStocks for this task. The reason is simple: the first step of price discovery is getting market viewpoints into the market, and expressing those views through derivatives is cheaper than doing so through spot assets.
II. Why Perpetual Contracts Are Better Suited for Price Discovery?
Taking NVDA as an example. During the sample period from July 17 to July 22, nominal trading volume for NVDAB spot was approximately $4.21 million, while NVDAUSDT perpetual contracts generated about $418 million during the same period—a difference of roughly 99 times. Looking strictly at weekends, perpetual contract volume was about 37 times that of bStocks on July 18, and about 68 times on July 19.
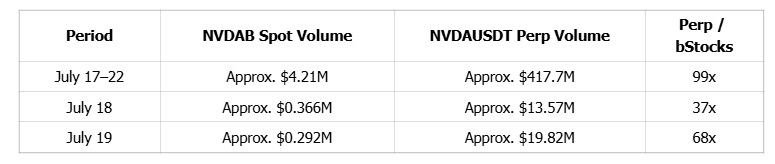
This comparison is between two products within Binance, not between Binance's perpetual contracts and Nasdaq's NVDA stock. The US spot stock market's trading volume still exceeds that of Binance's stock perpetual contracts. The purpose of this comparison is to judge where new directional orders are more likely to flow after the spot market closes.
Spot assets, once purchased, can be held for months. In contrast, perpetual contract positions are constantly opened, closed, reversed, and leveraged. Traders also execute basis trades and collect funding fees, while market makers continuously rebalance hedging positions. Therefore, the same dollar of capital can generate multiple rounds of total turnover in the perpetual market. The difference in shorting is even greater. If negative news about NVDA emerges on Saturday, traders without NVDAB inventory must first arrange share borrowing to short the spot asset. With perpetual contracts, traders simply need to sell to express a directional view.
Thus, the first price path after market close can be written as: Information → Perpetual Contracts → Candidate Price. The role of perpetual contracts is to generate candidate prices, not to guarantee the candidate price is correct. It is precisely this distinction that gives bStocks its raison d'être.
III. Research Methodology: Comparing 25 Market Close-to-Reopen Cycles
To observe how initial prices form, we collected and organized trading data for NVDAUSDT, TSLAUSDT, SNDKUSDT, SPCXUSDT, and SKHYUSDT. There were 25 observations that fully matched the subsequent US cash market open: NVDA, TSLA, SNDK, and SPCX each appeared 6 times, and SKHY appeared 1 time.
Each observation begins from the previous cash market close, proceeds through the pure weekend, Sunday pricing, Monday pre-market, and opening auction, finally arriving at the next cash market open. Prices at 19:59 ET on Sunday are used to observe the market state before regular US stock pre-market trading begins. Pre-market trading resumes after 04:00 ET on Monday, opening auction information begins entering the market after 09:25, and the formal cash market open serves as the final validation point.
The dataset answers four questions:
1. Price analysis measures the distance between weekend quotes and the next cash market open.
2. Liquidity analysis measures the actual order size that displayed prices could absorb.
3. Volume analysis measures the value amount turned over in the market.
4. Trade frequency analysis examines whether trading volume reflects independent investor views or a high-turnover market driven by algorithmic trading, market makers, and HFT.
Displayed market prices do not imply executability. Trading volume does not imply trades reflect independent judgment. Liquidity does not necessarily imply a market possesses price discovery capabilities.
IV. Price Analysis: Error Narrows from 181.9 to 11.3 Basis Points
"Error" here refers to the absolute distance between Binance's perpetual contract price at a given time and the next cash market open, uniformly expressed in basis points.
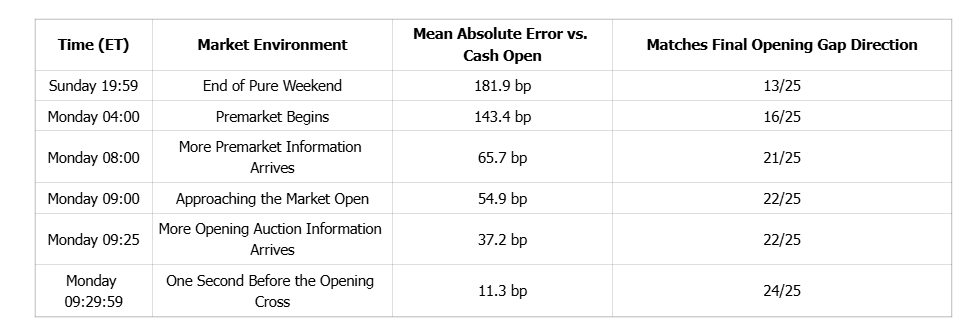
Sunday results show that out of 25 cases, 13 had the correct direction, a ratio of 52%. Among the 25 observations, 13 aligned with the final direction, and 12 did not. This shows no significant difference from random 50/50 directional guessing, so this dataset cannot prove that Binance provides consistent weekend price discovery.
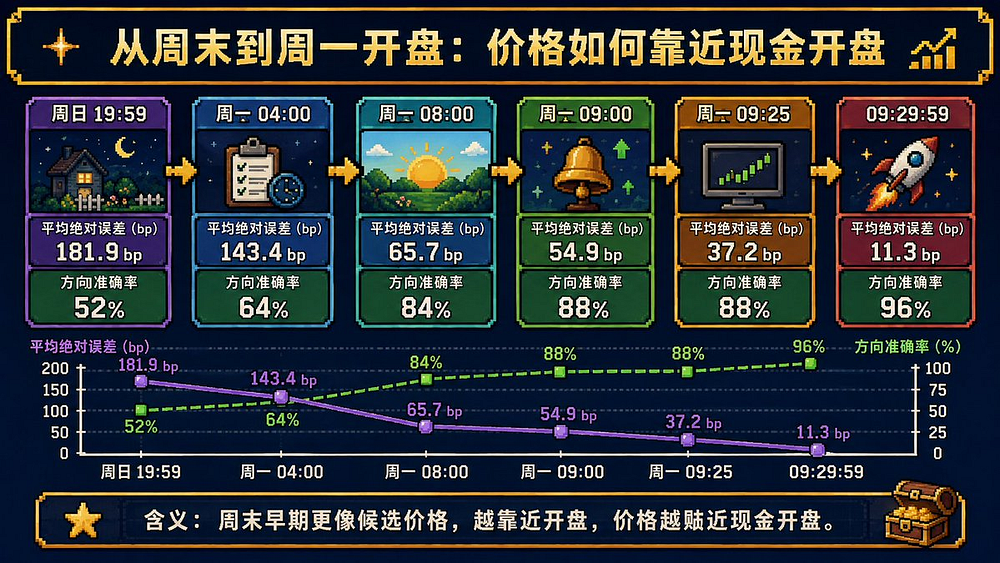
The 11.3 bps error at 09:29:59 cannot simply be interpreted as evidence that Binance can "predict Monday's opening price." By then, US stock pre-market has already been trading for several hours, and opening auction information has entered the market. If perpetual contract prices still significantly deviate from pre-market stock quotes, that difference itself creates a trading opportunity.
Therefore, the convergence from 181.9 basis points to 11.3 basis points indicates that as traditional markets come back online, Binance perpetual contracts gradually approach the next cash market open. This does not prove Binance leads the spot market. To answer that, a lead-lag analysis comparing Binance perpetual contracts, bStocks, and the last bid/ask prices in US stock pre-market must be conducted at the exact same second.
If pre-market prices rise first from 100 to 105, and perpetual contracts subsequently reach 105, then perpetual contracts are following. If perpetual contracts reach 105 first, and pre-market subsequently converges toward it, then this movement constitutes evidence of price discovery and price dominance.
V. Pre-Market Spreads Do Not Change in a Straight Line: SNDK Was Only 2 BPs Away at 09:25, But Deviated Again Five Minutes Later
During the 2026 Independence Day long weekend, from July 3 to July 5, the paths for NVDA, TSLA, and SNDK perpetual contracts from Sunday to the final second before the opening auction varied.
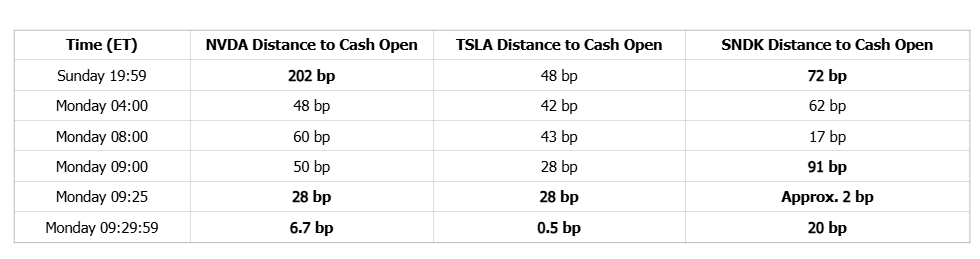
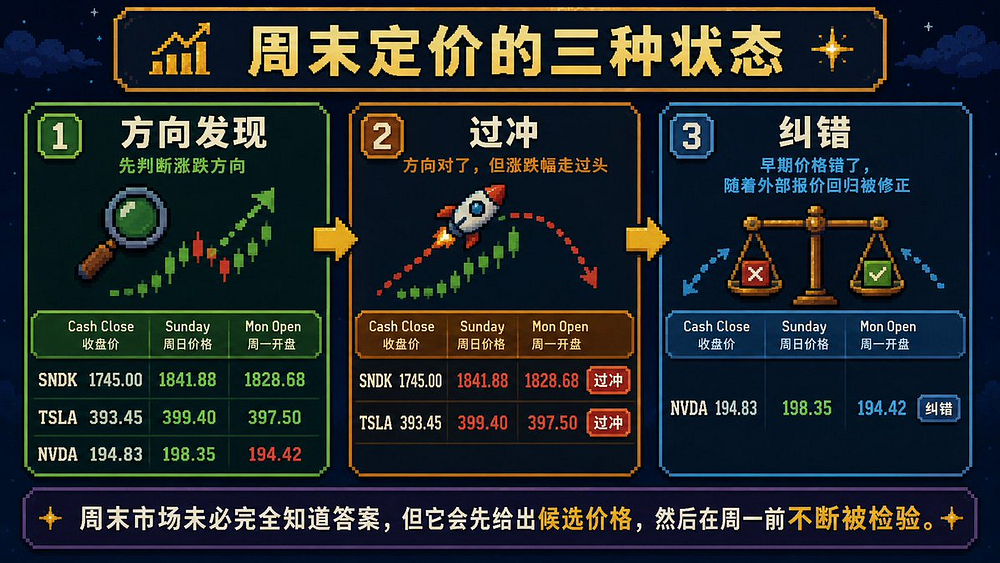
From this perspective, NVDA resembles an error correction process. Sunday trading price was $198.35, while the final cash market open was $194.42, a difference of about 202 bps. Prices returned to $194.97 at 09:25 and reached $194.55 at 09:29:59, narrowing the error to 6.7 bps.
TSLA's directional judgment was correct from Sunday onwards. Cash market close was $393.45, Sunday price was $399.40, cash market open was $397.50. The market priced in the upward direction in advance, but Sunday's gains exceeded the final opening gap.
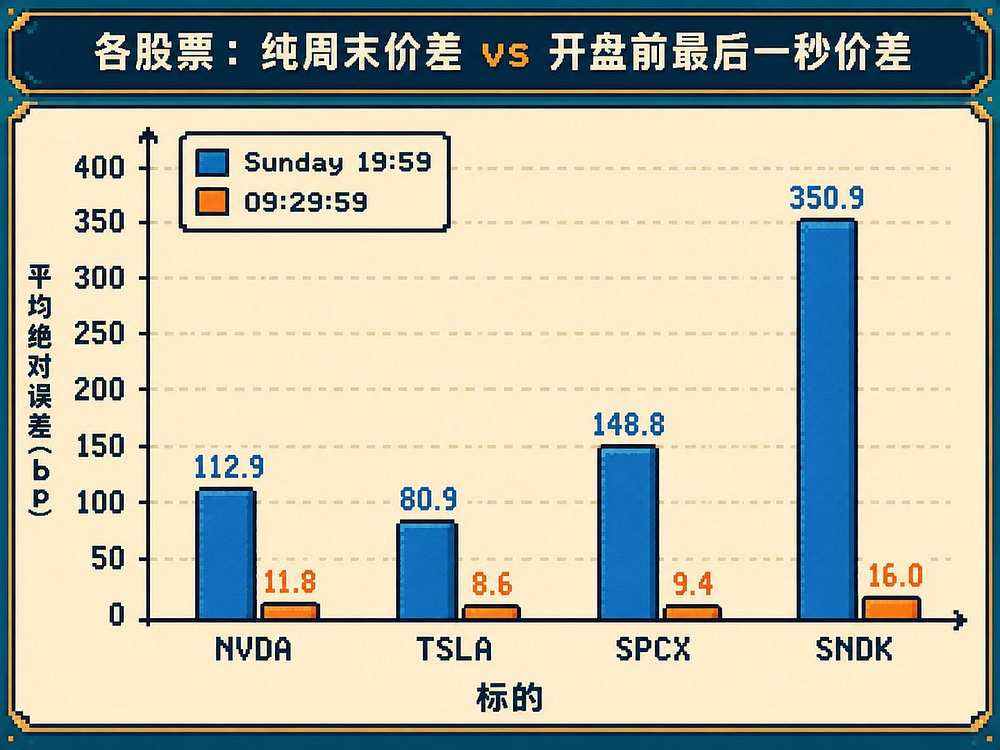
SNDK's path illustrates the issue more clearly. At 09:25, the perpetual contract traded at $1,828.97, while the final cash market open was $1,828.68, a difference of less than 2 bps. But by 09:29:59, the perpetual contract had fallen to $1,825, expanding the error to about 20 bps.
This shows that pre-market prices do not move linearly toward the final open. Pre-market trading, net order imbalance information, market maker inventory, and orders placed in the final minutes can all alter prices. To determine which market holds pricing power, one must examine the complete lead-lag path, rather than just comparing snapshots at two points: Sunday and Monday 09:29:59.
VI. Perpetual Contracts Are Not Necessarily Closer to the Next Open Than bStocks
Another low-frequency sample uses UTC end-of-day prices for NVDAB, TSLAB, MUB, and COINB to compare how they hand off to the next US cash open. Underlying assets with perpetual contracts were also included in the perpetual data.
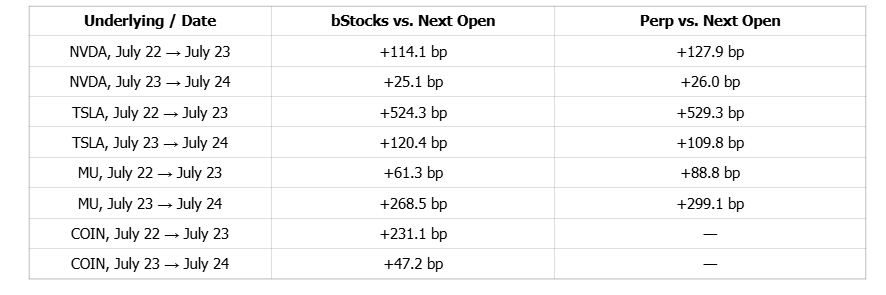
The median handoff error for eight bStocks observations was approximately 117.2 bps, while for six comparable perpetual observations it was about 118.9 bps.
NVDA from July 23 to July 24 provides a useful example. NVDAB traded at $207.97, perps traded at $207.99, and the next day's cash open was $207.45. Both were approximately 25 to 26 bps above the open price. The value of bStocks does not lie in producing prices closer to the underlying stock market than perps. Their role is to preserve the stock prices formed during the cash market closure into a spot-like inventory that can be held, transferred, converted, and financed.
Perpetual contracts drive price. bStocks turn prices into assets.
VII. Stock-by-Stock Breakdown: NVDA Is Error Correction, TSLA Is Overshoot, SNDK Is Stress Test, SPCX Is Product Experiment
In the NVDA sample, the average absolute error (MAE) of Sunday prices relative to the next day's cash open was about 113 bps, with directional matches in 3 out of 6 observations. TSLA's Sunday MAE was about 81 bps, matching direction in 4 out of 6. SPCX's MAE was about 149 bps, matching in 3 out of 6. SNDK reached about 351 bps, matching in 3 out of 6. By 09:29:59, their descriptive MAEs dropped to approximately 11.8 bps, 8.6 bps, 9.4 bps, and 16.0 bps, respectively.
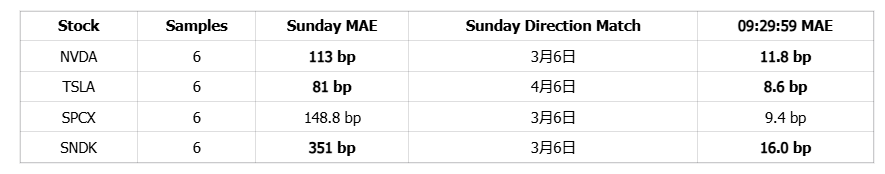
NVDA is better suited for observing how pricing errors get corrected. In the Independence Day observation, Sunday price was $198.35, cash open was $194.42, deviation 202 bps. Prices subsequently converged steadily toward the $194 level.
TSLA serves as a useful example of overshoot. Its cash close was $393.45, Sunday price $399.40, cash open $397.50. Direction was correct, but magnitude was too large.
SNDK demonstrated two states within the same stock. During the Independence Day long weekend, it factored in most of a +4.8% opening gap in advance. But in another weekend in August, its Friday cash close was $1,212.21, Sunday price $1,223.98, Monday cash open dropped to $1,203.41. This time, the direction was wrong.
SPCX occupies a different position. Its Sunday MAE was about 148.8 bps, matching direction in 3 out of 6 observations. However, this stock experienced evolution from Pre-IPO perps to publicly traded stocks, then to TradFi perps and SPCXB. Within Binance, the same underlying risk underwent a product migration: derivative prices appeared first, cash stocks later. This makes SPCX better suited for observing how a 24/7 pricing system interfaces with a subsequently emerging cash market.
Therefore, prices formed during cash market closure should not simply be categorized as "right" or "wrong." They can be further divided into directional discovery, magnitude discovery, and correction dependence. These categories will be discussed later.
VIII. SPCX: A Perp-to-Stock Pricing Experiment from Pre-IPO Perps to Public Stocks
Structurally, SPCX differs from NVDA, TSLA, and SNDK. When Binance Futures launched its Pre-IPO perpetual product in May 2026, SPCXUSDT was the first contract, allowing traders to build positions on SpaceX's expected public market valuation. After SpaceX went public, SPCXUSDT was converted into a standard TradFi perp, with SPCX Direct Stock and SPCXB added simultaneously. In other words, this stock had derivative pricing first, followed by a public cash market capable of verifying that price, and finally bStocks for on-chain holding and transfer.
This created a rare experimental environment. For NVDA and TSLA, Binance added a 24/7 risk layer outside an already mature market. SPCX, however, followed a migration path: Pre-IPO perp → public stock → TradFi perp → bStocks. Only after the cash stock appeared did continuous trading derivative prices gain a fixed Monday cash open for repeated verification.
Here are the six complete weekend datasets for SPCXUSDT:
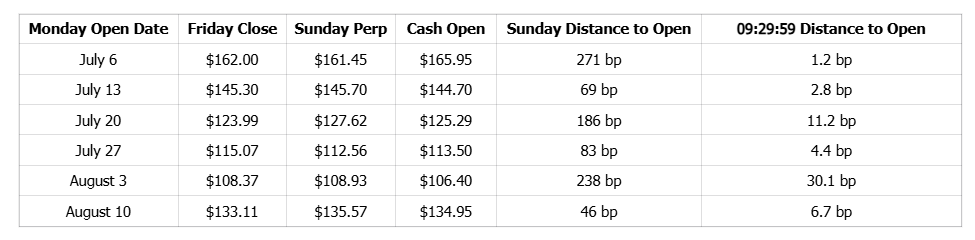
In six observations, Sunday prices matched the final direction 3 times. Its relative MAE to the next day's cash open was approximately 148.8 bps, median approximately 134.4 bps. By Monday 04:00 ET, average error dropped to 114.1 bps. Further down to 102.0 bps at 08:00, 53.8 bps at 09:00, 29.3 bps at 09:25, and 9.4 bps at 09:29:59. After 08:00, all six observations aligned with the final opening gap direction. But by then, pre-market trading had resumed. Therefore, this curve demonstrates price handoff and convergence, not that Binance independently completed price discovery.
SPCX also provides a concentrated overshoot perspective. Across three weekends where Sunday price direction was correct and opening gaps exceeded 50 bps, Sunday movements relative to final gaps were approximately 2.79x on July 20, 1.60x on July 27, and 1.34x on August 10. This suggests overshoot may have little to do with how long a product has been listed. Even after listing, markets can still overshoot.
The path on August 10 illustrates this issue more clearly. Friday close was $133.11, Sunday price had reached $135.57, Monday cash open was $134.95. Sunday price was only about 46 bps above the final open. However, at 08:00 Monday, SPCXUSDT briefly spiked to $138.80, widening the distance to the final cash open to about 285 bps. By 09:29:59, it had returned to $134.86, leaving only a ~6.7 bps gap. Prices can converge, deviate again after pre-market resumes, and converge once more.
SPCX trading doesn't resemble a quiet spot market. Over six weekends, SPCXUSDT cumulative volume was about $1.546 billion, roughly 10 times comparable NVDA figures. Its underlying gross transactions totaled about 3.58 million, averaging 3.45 per second. Its scale falls between SNDK and NVDA, appearing more like a continuously running programmatic risk engine. The implication for bStocks is direct: the faster the perp turnover, the more market makers must use inventory legs like SPCXB or SPCX to absorb delta when client order flow exhibits net directional imbalance.
Therefore, SPCX does not prove Binance has mastered weekend pricing power. A more accurate understanding is that it's a microcosm of the entire product system: Perps generate candidate prices, SPCXB solidifies that price into an asset, Stock provides an exit to the spot market, and lending availability/cross-market arbitrage determines whether mispriced quotes can be attacked bidirectionally. It demonstrates what infrastructure might need to look like if Binance intends to compete for pricing power during traditional market closures.
IX. Weekend Volume Analysis
Across the six weekends covered in the sample, NVDAUSDT cumulative volume was approximately $154 million, TSLAUSDT about $107 million, SPCXUSDT about $1.546 billion, and SNDKUSDT about $2.922 billion.
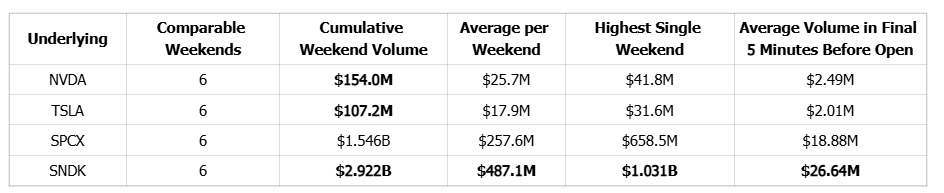
The table reveals clear volume tiers. Across six weekends, SNDK traded $2.922 billion, SPCX $1.546 billion, NVDA $154 million, TSLA $107 million. SPCX volume was roughly 10x NVDA's and 14x TSLA's, but only about half of SNDK's. This ranking bears no linear relationship to company market cap or traditional stock market fame. Therefore, total volume cannot be directly interpreted as organic investor demand.
Another noteworthy data point: during the final five minutes before pre-market, SNDK's average volume across six observations remained about $26.64 million, SPCX about $18.88 million, NVDA about $2.49 million, TSLA about $2.01 million. As the opening auction approached, the perp market did not stop and wait for results. It continued repricing.
The core question behind volume is: who generated these trades, how frequent are they, and how large is each trade.
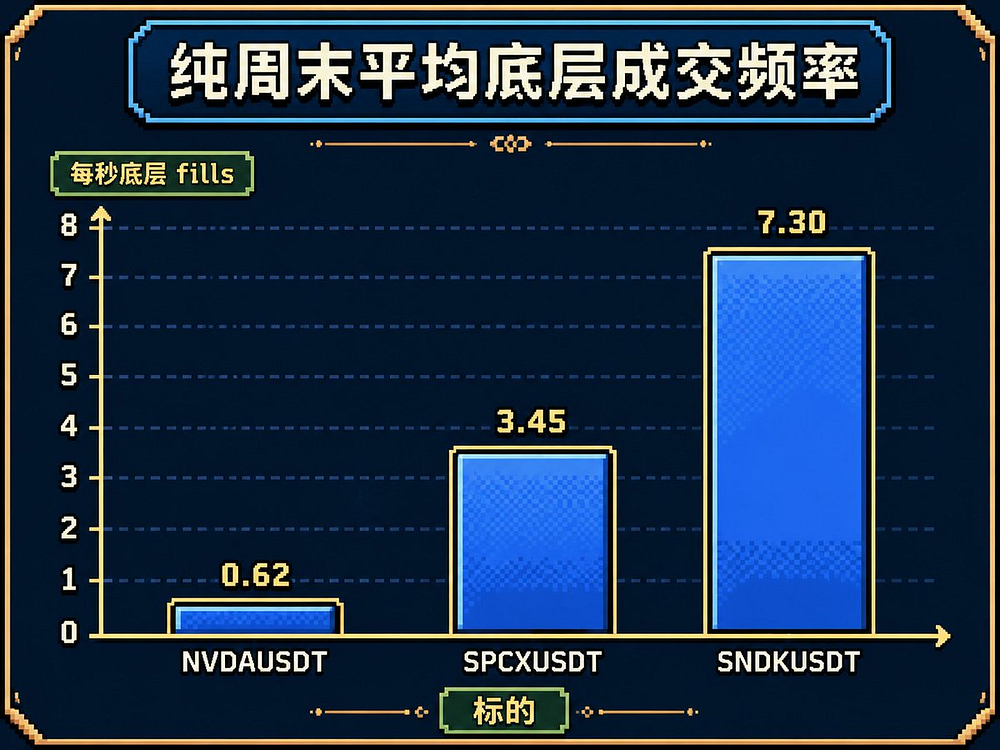
X. Trade Frequency Analysis: SNDK Trades 7.3 Times per Second, SPCX 3.45
Once SNDK's $2.922 billion and SPCX's $1.546 billion volumes are broken down into individual trades, the market's morphology changes.
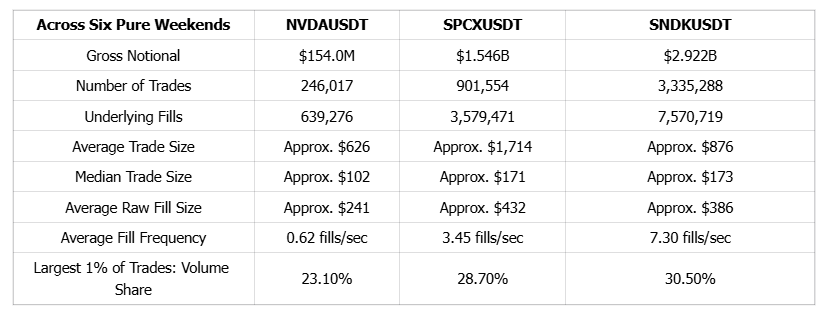
Across six weekends, SNDK recorded approximately 7.57 million trades, averaging about 7.3 per second. SPCX recorded about 3.58 million trades, averaging 3.45 per second, while NVDA recorded about 640,000 trades, averaging 0.62 per second. The primary difference among the three stocks lies in trade frequency.
Interestingly, differences in per-trade size are far smaller than differences in trade frequency. SNDK's average gross trade value was about $386, SPCX about $432, NVDA about $241. SPCX's median trade size was approximately $171, closely approaching SNDK's $173. SNDK and SPCX's massive turnover stems not from a few ultra-large orders, but from a much denser trade flow.
Since we lack account-level data, we don't know how many independent participants, institutions, or market makers generated these trades. However, based on trade size and frequency, this article leans toward the view that billions in trading volume do not represent equivalent independent investment convictions. In other words, volume should not be simply interpreted as institutions making directional bets.
We believe both SNDK and SPCX have evolved into high-speed equity derivative markets, with SNDK operating at an even higher velocity.
SNDK Analysis:
SPCX volume's 24-hour distribution provides another layer of insight. Between ET 00:00 and 06:00, the market still generated about 20.8% of weekend nominal volume and 20.9% of gross trades, averaging about 2.9 trades per second during these nighttime hours. Across six weekends, the net buy/sell nominal imbalance was about -1.16%, indicating a roughly balanced, two-way market. This pattern more closely resembles an all-hours market supported by market making, algorithmic trading, and cross-market arbitrage.
XI. Per-Trade Size Also Suggests Perps and bStocks May Serve Two Different Types of Order Flows
Average raw trade values for SNDK Perps were approximately $386, SPCX about $432, NVDA about $241. Median aggTrade sizes for SPCX and SNDK were approximately $171 and $173, respectively. A Binance Research report noted that about 93% of bStocks trades are fractional, with a median trade size of only $18.81, while approximately 80% of tokenized stock trades come from emerging market users. (https://www.binance.com/en/research/analysis/opportunity-only-tokenized-stocks-unlock)
It must be noted that this article and Binance Research use different data definitions. Therefore, we cannot simply divide $386 by $18.81 to conclude that perp users' average position size is 20 times that of bStocks users. However, taken together, both datasets suggest a division of labor between products. bStocks are better suited for small spot trades, long-term holding, cross-timezone retail users, and on-chain participants. Perps are more likely concentrated around leverage, basis trading, market making, HFT, and high-turnover capital.
One market creates holdable stock inventory; another allows the same risk to change hands rapidly. Only when market makers and arbitrageurs connect the two does a broader pricing network emerge. Currently, these two products are not yet fully integrated, leaving room for further development.
XII. The Higher the Perp Volume, the More Critical bStocks' Inventory Role Becomes
If Perp volume can reach dozens of times that of bStocks, why does Binance still need bStocks? The answer lies on market makers' ledgers.
Customer and market maker perp positions are mirror images. When customers net long, market makers short perps and must buy positive delta bStocks or stocks. When customers net short, market makers long perps and must sell their bStocks inventory or borrow and sell bStocks.
Perps solve the trading speed problem. bStocks determine where risk sits on the balance sheet. If customer net order flow consistently runs in one direction, market makers accumulate delta. This risk cannot circulate endlessly within the perp market. Eventually, an inventory leg is required to absorb it.
Therefore, high perp volume is not evidence of bStocks failure. Quite the opposite, it's one of the reasons bStocks must exist. The faster derivatives turnover, the greater the demand for inventory, financing, and securities lending. Retail users might barely notice this function, but it is crucial for market makers.
XIII. bStocks Are Not an Instantaneous Price Anchor: 1:1 Backing Is Closer to an Endgame Constraint
At this point, one might be inclined to describe bStocks as a spot anchor for perps, drawing an analogy between their relationship and that of USDT to the dollar. However, this mechanism varies under different market conditions and does not operate this way during stock market weekends.
Converting NVDAB to NVDA shares on Saturday does not mean an active spot market simultaneously exists on Nasdaq to complete the other leg of arbitrage. Traders receive inventory that can eventually reconnect with real shares, not an immediately executable spot arbitrage trade.
Therefore, 1:1 backing acts more like an endgame constraint. The market knows bStocks can ultimately reconnect with real shares, and knows the spot market will reopen. During spot market closure, prices may deviate, but once deviation exceeds funding costs, inventory costs, event risk, and execution friction, traders have incentive to wait for traditional markets to reopen, then converge spreads.
bStocks' role is not to tell perpetual contracts what the "correct price" should be. Its role is to pair candidate prices generated by perps with inventory that can be held, hedged, and arbitrated.
This is why a more accurate description is to characterize bStocks as the inventory layer and correction layer.
XIV. Once bStocks Go On-Chain, Priority Turns to Getting Inventory to Turn
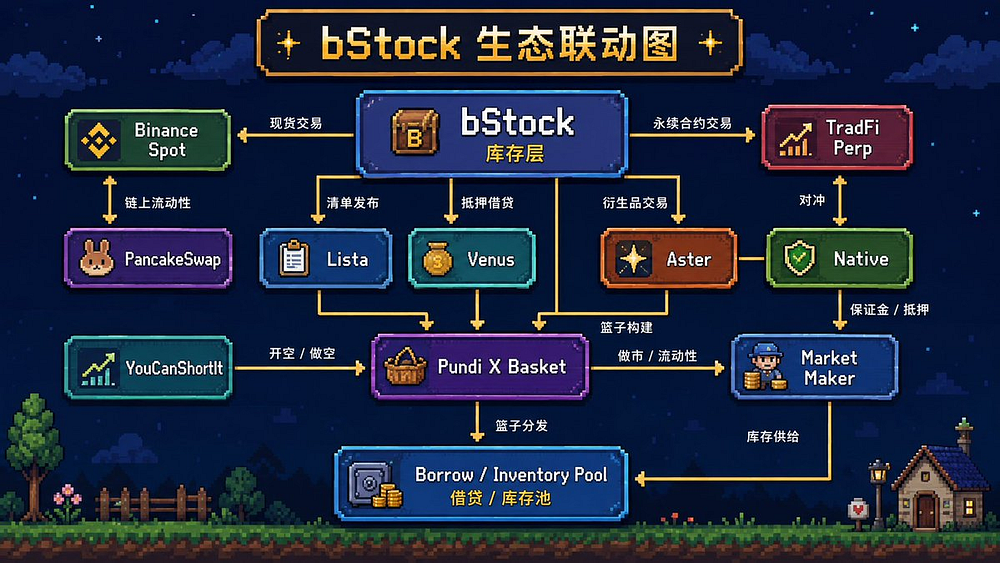
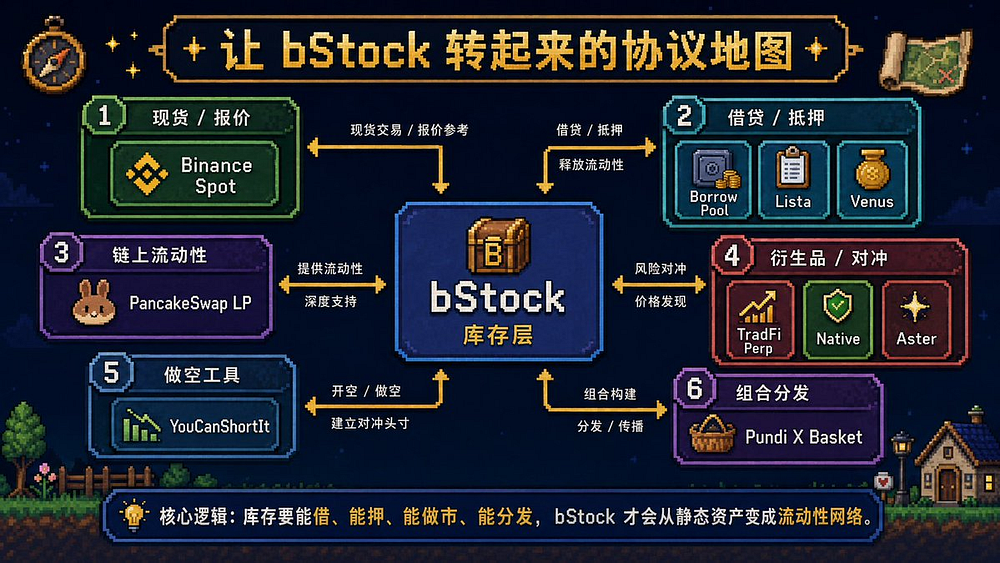
If NVDAB could only remain in Binance spot accounts, it would merely be a spot inventory layer within a centralized exchange. Once bStocks go on-chain, they can enter DEXs, lending, collateral, and margin systems, thereby altering market structure.
PancakeSwap has launched bStocks pools, including TSLAB, NVDAB, MUB, and SNDKB. Lista supports some bStocks as collateral for borrowing stablecoins, while Aster allows qualifying bStocks to enter multi-asset mode.
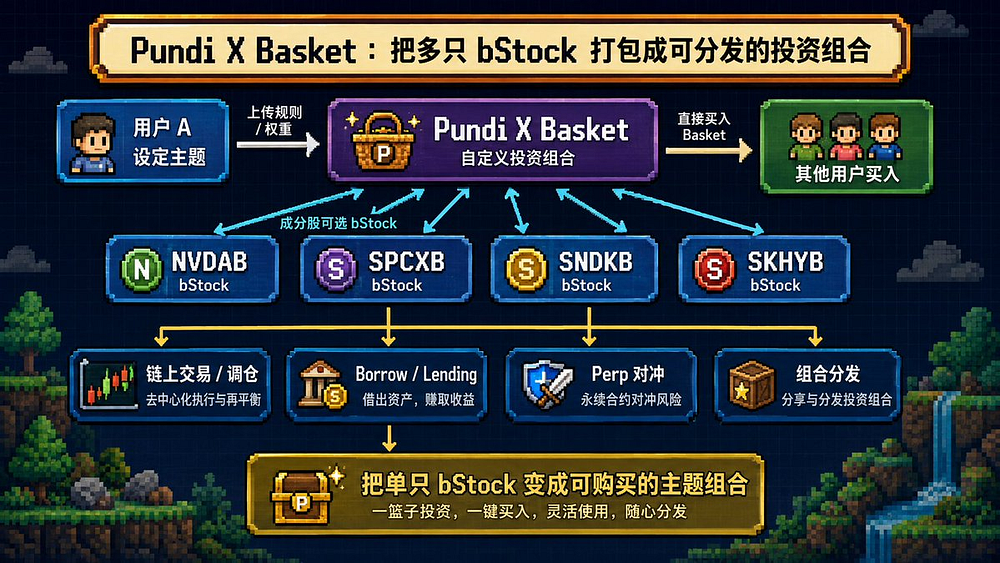
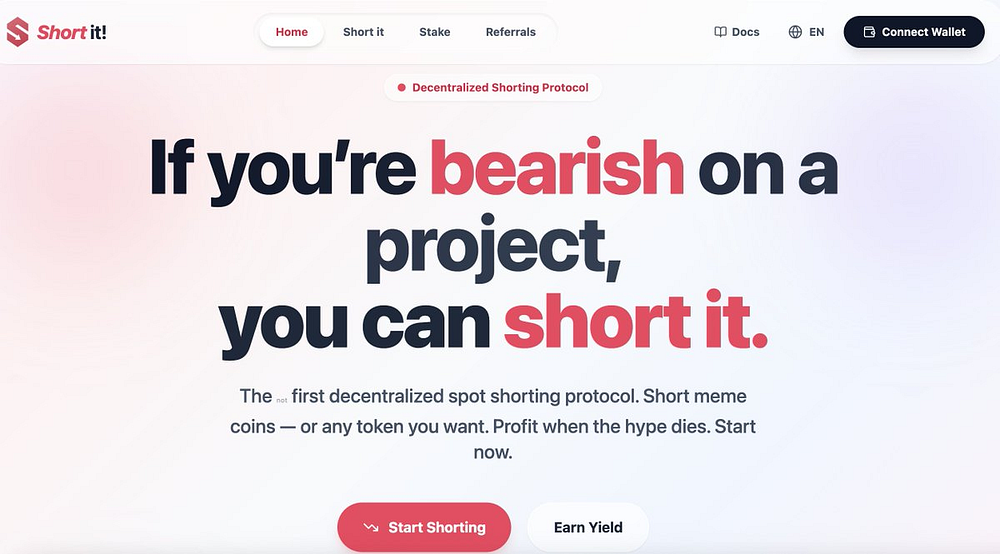
Youcanshortit.com allows users to lend bStocks for leveraged shorting. Pundi X Basket allows users to freely customize their portfolios and index ETFs, which other retail investors can subsequently copy.
These products don't solve the same problem, but they point in the same direction: making NVDAB, SNDKB, and SPCXB tradable, pledgeable, financeable, market-makable, and hedgeable, rather than simply sitting idle in wallets.
Distinguishing between extending utility and adding liquidity is important. When a NVDAB token is locked as collateral in a lending protocol, its utility increases, but it doesn't necessarily bring new buy/sell pressure to the market. It only starts increasing available market inventory when market makers, arbitrageurs, or shorters can borrow it and deploy it on CEXs or DEXs, or use it to hedge perp exposure.
Therefore, the ideal on-chain loop isn't simply Binance → wallet → DEX, but bStocks → DEX/lending/credit pool → market makers → perp hedging → CEX → stock conversion. Inventory only begins turning when the same batch of bStocks can be reused across different accounts.
For bStocks, TVL isn't the most critical metric. A more meaningful question is: how many times can one unit of stock inventory be utilized? If $1 million in NVDAB is merely locked in a protocol, it remains $1 million in static assets. It only begins functioning as market infrastructure when part of that inventory can be borrowed by market makers to provide quotes, hedged with perpetual contracts, and returned to the inventory pool after trades.
Binance's own research also reported that 2,806 users conducted arbitrage-like trades across bStocks, perpetual contracts, and stocks, involving approximately $216 million. About 58.5% of bStocks users also utilize perpetual contracts and/or stocks. This indicates grassroots quant traders already exist; the next step is activating them as seed users for bStocks.
Once bStocks are on-chain, one possible path is using NVDAB as collateral to borrow stablecoins, then transferring them back to a CEX to trade NVDAUSDT perpetual contracts. Another path is depositing NVDAB into a DEX liquidity pool and using NVDAUSDT perpetual contracts to hedge the LP position's stock delta exposure.
In this way, bStocks connect CEX perps, CEX spot, real stocks, DEXs, lending protocols, and stablecoins within a single risk network.
This is also what distinguishes bStocks from ordinary "stock tokens."
XV. What This System Lacks Isn't More Trading Pairs, But Borrowing
Borrowing USDT using NVDAB as collateral is financing. Borrowing NVDAB and selling it is securities lending. Both involve borrowing, but they play different roles in price discovery.
If perp prices are high while bStocks prices are low, arbitrageurs can go long bStocks + short perps. This trade is relatively easy to execute. Buy the cheaper spot asset, sell the more expensive derivative, thereby compressing the perp premium.
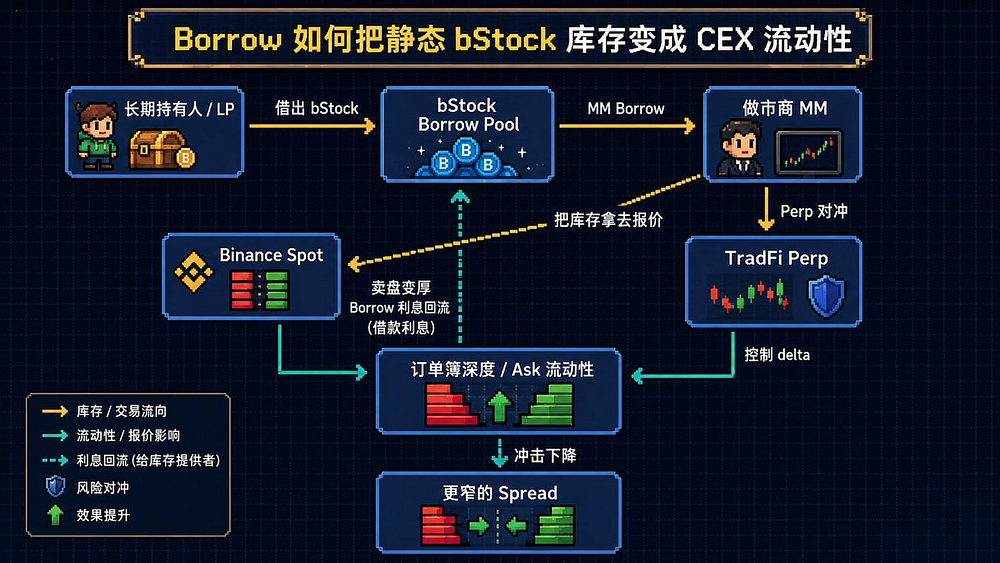
If bStocks prices are high while perp prices are low, the trade should reverse: short bStocks + long perps. The problem is, without borrowable inventory, this trade cannot be executed. When an asset trades at a discount, anyone with cash can buy. But when it's overvalued, not everyone has inventory to sell.
Therefore, bStocks maturity shouldn't be measured solely by listing quantity. Borrow depth, borrowing rates, available inventory, and borrowing stability during event-driven weekends determine whether the market has the capacity to correct mispricing bidirectionally.
Without borrowing, bStocks remain merely an asset layer, unable to realize its intended advantages on the platform.
Once borrowing is in place, bStocks begin to function like a securities inventory market.
Market-making demand drives borrowing → borrowing demand pushes up rates → higher rates attract more deposits → bStocks volume and demand increase → cycle repeats.
XVI. Deepening bStocks Liquidity on CEX Still Depends on Integrating the Borrow Ecosystem
Returning to Binance CEX, bStocks' liquidity bottlenecks become clearer. When customers heavily sell NVDAB, market makers can buy NVDAB and hedge by shorting NVDAUSDT. On the buy side, the primary resource consumed is cash. But when customers heavily buy NVDAB, market makers must continuously sell shares to customers. Once inventory is depleted, market makers without access to borrowing channels can only reduce ask order sizes, raise ask prices, or exit the market.
Therefore, the bStocks spot order book suffers from inherent inventory constraints. Without borrowing, market makers can only quote based on the number of shares they already hold. With borrowing, inventory transforms from a hard limit into a priced resource. Market makers can borrow NVDAB and sell to customers, while going long on perps or hedging with stocks. As short demand rises, borrowing rates increase, incentivizing holders to deposit more bStocks into inventory pools.
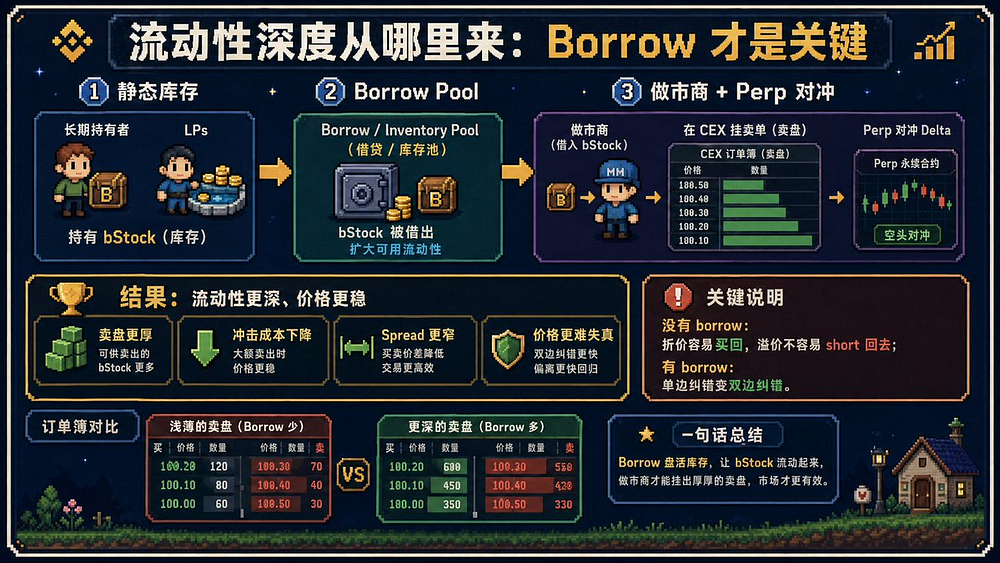
Lending also solves the reverse basis issue discussed earlier. When perps are expensive and bStocks cheap, anyone with sufficient funds can execute a long bStocks plus short perps trade. When bStocks are expensive and perps cheap, the required trade is short bStocks plus long perps. Without borrowable inventory, this arbitrage channel cannot function.
Of course, lending doesn't run in isolation. Deep CEX liquidity also requires stock-bStock conversion to replenish inventory, portfolio margin to lower capital requirements for bStock-perp hedging, and market-maker programs to convert inventory into bids and asks. Market-maker rebates can encourage market makers and protocol operators like Pundi X Basket to deploy trading bots, but lending determines whether these bots have inventory to trade.
Summary:
Perps generate orders. bStocks provide stock inventory. Lending puts inventory into circulation.
If lending develops smoothly, bStocks can take another step from "tradable stock tokens" to becoming securities inventory capable of supporting market making, financing, and two-way arbitrage.
Compared to Wall Street, crypto's greatest weapon is decentralization. Lending can mobilize institutional and grassroots decentralized market makers to participate in the weekend price discovery race.
XVII. The Endgame Isn't bStocks vs Perps, But Four Markets Operating in Synergy
If lending, conversion, and on-chain depth all mature, the same Nvidia exposure could potentially trade at four different prices simultaneously.
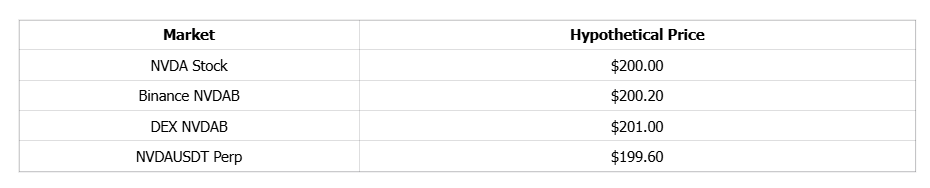
By then, cross-market traders will care first about which market is expensive and which is cheap, not Nvidia's EPS forecast for next year.
If NVDAB on a DEX trades at $201 while perps trade at $199.60, traders can sell the expensive leg and buy the cheap one. If traders lack bStocks inventory, they can borrow. If short on cash, they can pledge other assets. If they don't want overall directional exposure to Nvidia, they can hedge away the delta with the other leg. After cash markets reopen, traders can adjust inventory based on the basis between stocks, bStocks, and perps.
By then, bStocks cease to be an independent trading product. They become an asset class enabling risk migration across stock ↔ CEX spot ↔ DEX ↔ perp ↔ credit.
Prices are no longer dictated by any single exchange or mechanically generated by liquidity. They emerge from arbitrageurs repeatedly deploying balance sheets across markets, compressing spreads.
XVIII. Future Assessment of bStocks Maturity Shouldn't Rely Solely on Volume, Liquidity, and Listing Count
Measuring bStocks solely by AUM, 24-hour volume, and listing count would completely underestimate their role in market structure. It's like reducing something designed to transcend the existing market stack to mere errand-running.
Volume and liquidity are only part of the picture. Gross volume can also be inflated by algorithmic turnover and HFT.
If Binance aims to build bStocks as the inventory layer for weekend stock markets, then borrow depth, executable spot depth, conversion capacity, and basis stability between perps and bStocks may matter more than listing a few hundred more pairs or deepening liquidity for any single spot market.
A $1 million best bid/ask and a $10 million best bid/ask are fundamentally no different in nature. If depth is the sole goal, why trade on Nasdaq? What holds more value than depth is determining which price is "correct."
Why? Because liquidity on mispriced assets ultimately just becomes fuel for arbitrage.
This article organizes relevant capabilities and their corresponding metrics as follows:
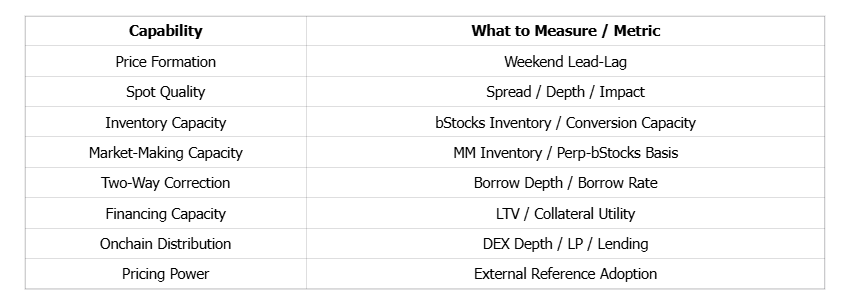
Conclusion: Perps Compete for Pricing Power; bStocks Determine Whether That Price Can Become Market Price
When pricing, volume, trade frequency, order books, and underlying stock data are considered together, the significance manifested by bStocks extends far beyond the so-called "tokenized stocks."
Perpetual contracts will become the darling of the derivatives market. Beyond volume, regulation, taxes, and operations, Wall Street will eventually understand what open interest exceeding float means. Open interest is money, and it's money that doesn't dilute control, require external disclosure, or face identical tax constraints.
If Binance wants to compete for pricing power after traditional stock markets close, perps will lead the charge. In one Nvidia sample, perp volume was 99 times that of bStocks. SNDK generated $2.922 billion across six pure weekends, SPCX $1.546 billion, SKHYNIX over $2.4 billion across six UTC weekend windows. These data indicate that when traditional stock exchanges close, some equity risk trading is migrating to 24/7 derivative markets.
The same dataset also shows volume and price discovery are not equivalent. SNDK could generate hundreds of millions in volume over a single weekend yet still guess direction wrong. Four stocks could generate $461 million in combined volume yet all point in the wrong direction. Adding SPCX, across 25 US market close-to-reopen observations, Sunday direction matched the final open direction only 13 times, i.e., 52%. SNDK's $2.922 billion corresponds to roughly 7.3 trades per second, SPCX's $1.546 billion to roughly 3.45 trades per second. These high-turnover figures cannot be directly interpreted as equivalent independent investment convictions.
Perpetual contracts solve the problem of keeping prices updated in real-time when traditional markets close. But to give these prices credibility, the market must also answer another question: when they're wrong, who corrects them?
bStocks are the answer. They can serve as the inventory leg for market makers hedging perps, the spot leg for basis traders, core holdings for long-term investors, collateral for lending protocols, equity assets for DEX liquidity providers, and tools for managing cross-timezone inventory via stock conversion. If lending develops sufficiently, bStocks can also become securities inventory available for short sellers, empowering arbitrageurs to attack the overvalued side of the market.
Therefore, the relationship between perps and bStocks should be understood as follows:
Perps produce the rough draft of price. bStocks turn that draft into an asset that can be held, financed, transferred, and challenged by the market.
One day, if major Nvidia news breaks on Saturday, NVDAUSDT may move first, followed by NVDAB repricing. The basis between perps and bStocks may widen, borrowing rates may shift, DEX liquidity provider positions may begin rebalancing, market makers may adjust inventory, and arbitrageurs may compress spreads. Then US stock pre-market will reopen, followed by the 09:30 opening auction. At that point, the question worth asking is no longer whether Binance correctly guessed the weekend trend, but:
Whose price converges to whose?
If after pre-market opens Binance continues chasing traditional markets, it operates as a 24/7 exchange. If after spot markets reopen, prices begin converging toward the price repeatedly traded out over dozens of hours in perps, bStocks, DEXs, lending protocols, and inventory markets, if external OTC desks, risk control systems, and market data platforms also start quoting that price, then what Binance gains won't be just a few extra trading hours. It will gain:
Pricing power over the stock market.
That is the foundation for reaching three billion users.
For more details on market-making and arbitrage strategies for Binance bStocks, please visit my Substack. I will share my practical trading experience there, along with bStocks' current defects, structural weaknesses, and trading opportunities.
Finally, this article is dedicated to the elders who accompanied me in my childhood.
Facing death itself isn't difficult. The challenge lies in figuring out how those left behind should continue forward.
May flowers pave your path ahead. Farewell, rest in peace.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 吴说区块链
















