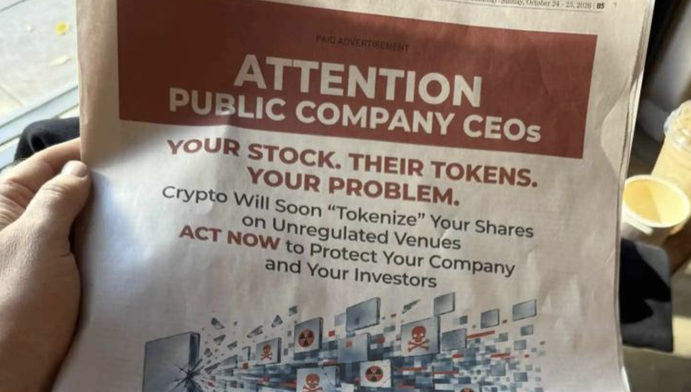
Tokenized Stock Race: Exchanges Rush to Lead the "All-In-One Market"
Author: Tanay Ved
Translated by: TechFlow
TechFlow Summary: Cryptocurrency exchanges are transitioning from pure crypto casinos into “universal exchanges” that cover stocks, commodities, and derivatives, with Binance’s tokenized stock monthly volume surpassing $3.7 billion. This transformation is not merely an expansion of product lines but could also alter the cyclical nature of exchange revenue. Meanwhile, the SEC’s newly introduced “Innovation Exemption” policy may push tokenized stocks out of gray areas and toward legalization.
The Race for Tokenized Stocks, Real-World Asset Perpetual Contracts, and “Universal Exchanges”
Digital asset exchanges are expanding from pure crypto platforms into “universal exchanges,” housing spot markets, derivatives, tokenized assets, and on-chain infrastructure under one roof. Leading platforms are now converging toward full-stack infrastructure that covers both crypto-native and traditional markets.
Kraken and its parent company, Payward, serve as an excellent case study for this shift. Through xStocks, its proprietary Ethereum Layer 2 network Ink, and a newly announced compliant on-chain derivatives business, Payward is positioning itself across the entire tokenized stock value chain. In September this year, Nasdaq Ventures agreed to invest $100 million in Payward to deepen collaboration on tokenized stock infrastructure. Meanwhile, Payward announced plans to offer regulated, permitted on-chain perpetual futures to U.S. clients via Hyperliquid’s HIP-3 mechanism.
These moves coincided with a single month: the SEC’s release of the “Innovation Exemption” policy. It signals that exchanges, issuers, and market infrastructure providers are converging toward tokenized stocks from multiple directions. This issue of “Network State” will break down how tokenized stock trading and real-world asset perpetual contracts expanded across major exchanges this year, the role played by the SEC’s innovation exemption, and how the race for “universal exchanges” is unfolding.
The Race for Tokenized Stocks
Exchanges are approaching the tokenized stock space from various angles. The common thread is their attempt to integrate spot tokenized stocks, derivatives, and blockchain infrastructure into a broader multi-asset trading ecosystem.

Kraken/Payward offers spot exposure through xStocks and is entering the U.S. compliant derivatives market via Hyperliquid’s HIP-3. Issued by Backed Finance, xStocks delivers dividends to holders through a rebasing mechanism, providing economic exposure to equities. Kraken’s partnership with Nasdaq is driving its evolution toward a rights-retained model (NETs), which will coexist alongside xStocks.
Binance launched bStocks in June, reaching over $500 million in assets under management within seven weeks. Similar to xStocks, bStocks are certificates representing financial rights to underlying stocks, carry no voting rights, and can only be redeemed during market trading hours.
Coinbase issues tokenized stocks via the B20 standard, designed specifically for real-world assets on the Base chain. Coinbase describes each token as a direct claim on the underlying stock, held by Alpaca through a Special Purpose Vehicle regulated by the ADGM. However, only eligible holders who complete KYC can redeem or vote. Dividend rights are open to all holders.
Hyperliquid serves as an infrastructure and liquidity layer where third parties can build applications. Since August, Hyperliquid has listed spot markets for select xStocks and allows external developers to deploy perpetual contracts for equities, indices, and commodities via HIP-3. Kraken plans to introduce compliant U.S. perpetual contracts to Hyperliquid through its CFTC-regulated subsidiary Bitnomial, making this model a clear example.
In July, Robinhood launched equity tokens on Robinhood Chain, structured as debt securities utilizing a Jersey-based Special Purpose Vehicle. Dividends are distributed via an on-chain multiplier mechanism. Currently lacking voting or shareholder rights, Robinhood states it is advancing a roadmap for physical stock redemption and voting rights.
Other platforms are also flooding into this track. OKX launched “Unified Tokenized Stocks” on the OKX X Layer blockchain, while Backpack rolled out tokenized stocks on Solana using a U.S. broker-dealer structure, bringing it closer to traditional shareholder rights than most models above.
Tokenized Stocks and Perpetual Contracts: Current Adoption
Despite a pullback in overall crypto trading volume this year, tokenized stock trading and perpetual futures linked to real-world assets have seen significant growth across major exchanges.
Spot tokenized stock volumes for xStocks, Ondo, and bStocks surged significantly this year, largely driven by Binance’s entry. Since launching in June, bStocks saw trading volume on Binance grow from nearly zero to over $3.7 billion within months. The growth in issuance has also directed secondary market activity toward decentralized exchanges and automated market makers, particularly Uniswap v4 on Robinhood Chain, where equity token-related activity continues to accumulate.
Changes in the perpetual futures market have been even more pronounced. The share of equity and commodity perpetual contracts in total futures volume continues to rise, with Binance and Hyperliquid seeing their respective shares climb above 20% and 40% this year. Exchanges are diversifying revenue sources and volume bases beyond pure crypto trading. This suggests future cyclicality may soften, and as markets gradually shift to 7×24-hour trading, exchanges stand to gain a broader, always-on growth engine.

Source: Talos CM Market Data
Just Kraken’s xStocks alone has accumulated over $3 billion in on-chain market capitalization across Ethereum and Solana. Active addresses interacting with xStocks also surged dramatically in September, with the allocation and utilization of these assets expanding from on-chain and centralized exchanges to use cases such as treasuries and lending protocols.

Source: Talos CM Market Data

Source: Talos CM Network Data Pro
SEC Innovation Exemption: Who Stands to Benefit Most?
On September 17, 2026, the SEC launched a five-year “Innovation Exemption,” allowing eligible tokenized securities trading venues to trade tokenized stocks on-chain through permitted automated market makers without registering as exchanges. To qualify, tokens must carry traditional shareholder rights, including dividends and voting rights, and be issued by or on behalf of the issuing company, or by an unaffiliated third party that raises no objections.
Infrastructure that aligns more directly with the SEC’s description includes issuer-native and transfer agent models from Securitize and Superstate, Dinari’s custody architecture, and the DTCC’s own pilot program to tokenize DTC-custodied securities. Whitelisted pools on Uniswap v4 will benefit, while Kraken’s Nasdaq Equity Tokens (NETs) and Coinbase’s B20 indicate that exchanges are building their own rights-retained models. xStocks, bStocks, and Robinhood’s Stock Tokens are driving the majority of current trading volume, but based on their existing structures, they appear to fall outside this framework.
Market reaction has been broadly positive, with tokens and stocks tied to tokenized stock infrastructure seeing widespread gains, regardless of how directly their underlying models map to the exemption requirements.

Source: Talos CM Reference Rates
Crypto trading venues are evolving into multi-asset platforms, while traditional assets are adopting the 24/7 programmable structures pioneered by the crypto industry. The growth of xStocks, bStocks, Coinbase’s B20, Robinhood Stock Tokens, and RWA perpetual contracts indicates surging demand for equity exposure in both spot and derivatives forms.
Tokenization models span a spectrum, ranging from issuer-native equity to custodial exposure, and finally to pure derivatives. Each model trades ownership for accessibility. It remains to be seen which model ultimately prevails, as adoption remains in its early stages. For exchanges, the opportunity lies in a more diversified revenue base; for the market, the boundaries between crypto assets and traditional assets continue to blur.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @coinmetrics