


Pantera Capital: 4 Major Opportunities in the Compute Market
Author: Jay Yu, Partner at Pantera Capital
Translated by: Jiahuan, ChainCatcher
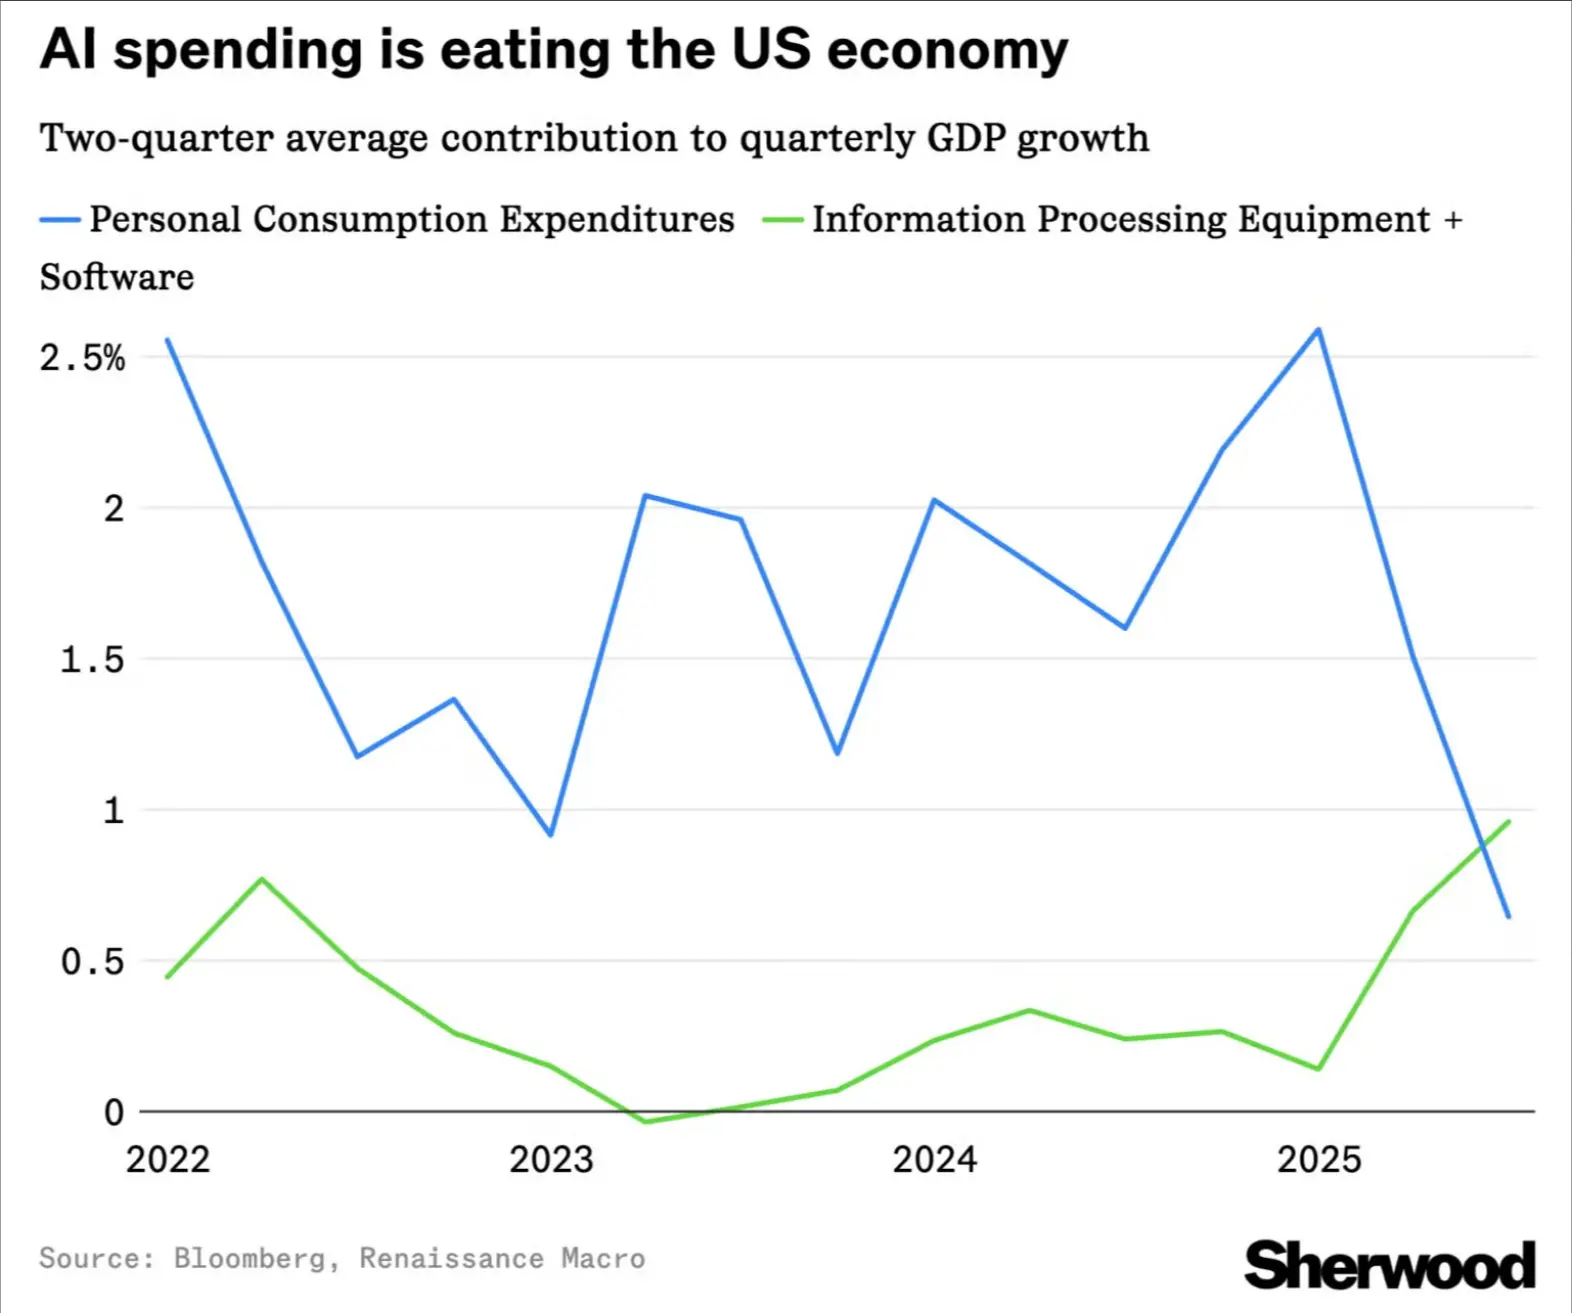
Compute and data center infrastructure spending has become a trillion-dollar market, comparable in scale to US consumer spending, and is gradually emerging as a key pillar of US economic growth.
However, as AI Agents gradually enter the real economy, demand for compute power continues to grow, yet the procurement of GPUs remains highly traditional. Although compute markets such as SF Compute, Vast AI, and Runpod have emerged, the trading of large volumes of GPU nodes still takes place through group chats, OTC brokers, and customized bilateral agreements.
Currently, GPU compute power is still in its early stages of financialization. Similar to electricity, compute is not a fully homogenous asset; it is constrained by factors such as chip model, delivery timeline, and geographical location. However, over the next 5 to 10 years, compute is likely to gradually become a commodity, much like electricity or oil, serving as a critical resource underpinning the global economy in the AI era.
This article explores how the compute market undergoes this transformation, drawing insights from the electricity market, outlining the potential market structure, detailing products being built by the industry, and examining the opportunities and challenges in the commoditization of compute.
1. Finding Answers in the Electricity Market
1.1 Structure of the Electricity Market
To understand how the compute market might evolve in the future, we can first observe its underlying resource: the operation of the electricity market.
Like compute, electricity is also an asset characterized by heterogeneity, time sensitivity, and hub attributes, serving as a fundamental pillar of global economic growth.
Starting in the 1990s, the US power system underwent gradual privatization. Historically highly vertically integrated utility companies began unbundling operations such as power generation, transmission, and distribution.
Independent System Operators (ISOs) began managing power systems across different regions of the United States. At the same time, large interconnection systems such as PJM-West (US East Coast), ERCOT North (Texas), and CAISO SP15 (Southern California) eventually became tradable commodities on exchanges like CME and ICE, establishing crucial price benchmarks for the entire electricity asset class.
At a physical level, the electricity market can be broadly summarized as a structure of "grids, operators, and nodes."
The top layer consists of independent regional grids. Beneath each regional grid are a set of system operators, including Regional Transmission Organizations (RTOs) and Independent System Operators (ISOs). These operators are responsible for managing multiple substation nodes within their local areas.
Taking San Francisco as an example, a city may be supplied by multiple substation nodes, such as Embarcadero, Larkin, and Mission.
Electricity prices at each node are not entirely uniform; they are determined by an algorithm known as "Locational Marginal Pricing" (LMP). This algorithm comprehensively factors in power generation dispatch, user demand, transmission costs, and power flow patterns to calculate optimal pricing under operational constraints.
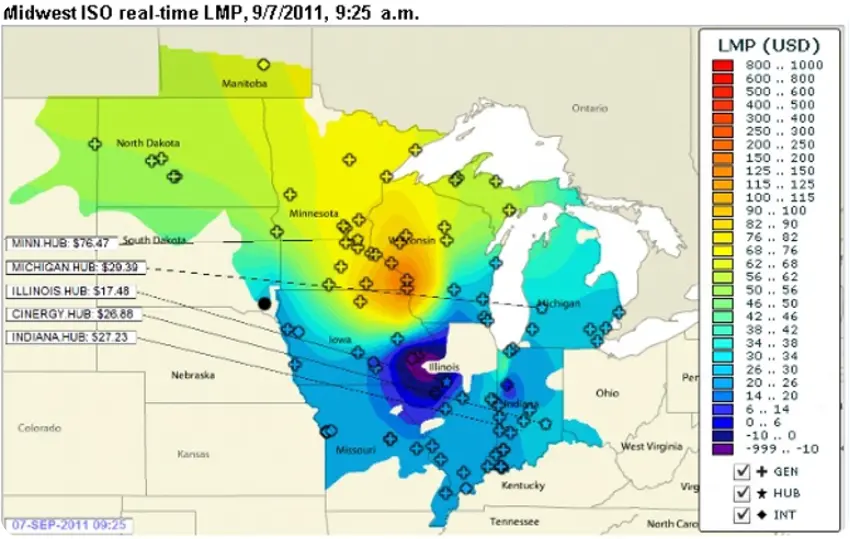
The LMP algorithm serves as the critical link connecting physical electricity delivery with tradable electricity benchmarks such as PJM-West.
Hub prices and index prices in the electricity market are essentially weighted averages of multiple terminal LMP node prices. Among them, the largest and most liquid price benchmark ultimately secures consistent trading depth on exchanges like CME and ICE, becoming the reference price for the entire electricity asset class.
1.2 Potential Structure of the Compute Market
Observing the development of the electricity market over the past 30 years allows us to draw several hypotheses regarding the compute market.
First, the compute market is likely to develop a structure similar to that of the electricity market.
At the physical delivery level, the closest compute equivalent to the electricity market's "grids, operators, and nodes" structure might be "hardware, suppliers, and clusters."
Just as the electricity market features multiple independent regional grids, the compute market may fragment into distinct submarkets based on hardware categories. H100, H200, B200, B300, and other chip categories could each possess their own independent yet interconnected price benchmarks.
At the operator level, compute providers such as AWS, Nebius, CoreWeave, SF Compute, and Ornn will offer varying pricing mechanisms for specific clusters. These clusters are similarly influenced by time, location, and SKU, analogous to different nodes in the electricity market.
As for the compute market equivalent to LMP, it is likely a scheduling or routing algorithm that dynamically generates instance pricing based on the availability of specific SKUs.
In the electricity market, benchmarks that ultimately become industry reference prices, such as PJM-West, ERCOT-North, and CAISO SP15, are typically connected to the most liquid physical delivery infrastructure. This mirrors other commodity markets like oil.
As more price benchmarks emerge in the compute sector, those linked to highly liquid physical delivery venues are likely to prevail.
Furthermore, in the electricity market, generators and industrial consumers sometimes hedge directly on power exchanges, but the majority of transactions are still executed by OTC desks operated by banks and trading firms. These OTC entities facilitate swaps between node settlement prices and hub settlement prices, capturing spreads while hedging their own risk exposures.
A similar market structure may emerge in the compute space. The actual supply and demand participants—namely next-generation cloud providers and AI companies—may prefer sourcing specific SKUs through brokers rather than hedging directly on compute exchanges.
Finally, the compute market may face more severe basis risk compared to the electricity market.
Under the US Federal Power Act, wholesale electricity prices must remain transparent under the oversight of the Federal Energy Regulatory Commission (FERC). Currently, no such transparency requirements exist for the compute market.
This implies that dynamic pricing and indices established in the compute market can only rely on internal order books and order book data provided by partnered next-gen cloud providers. Such partnerships may be structured through revenue sharing or data procurement agreements.
2. Structure of the Compute Market
2.1 Three-Tier Structure of Inference Demand
The electricity market exists due to the continuous power demands of industrial systems. Similarly, the fundamental driver of the compute market is the application-level demand for tokens, particularly inference tokens.
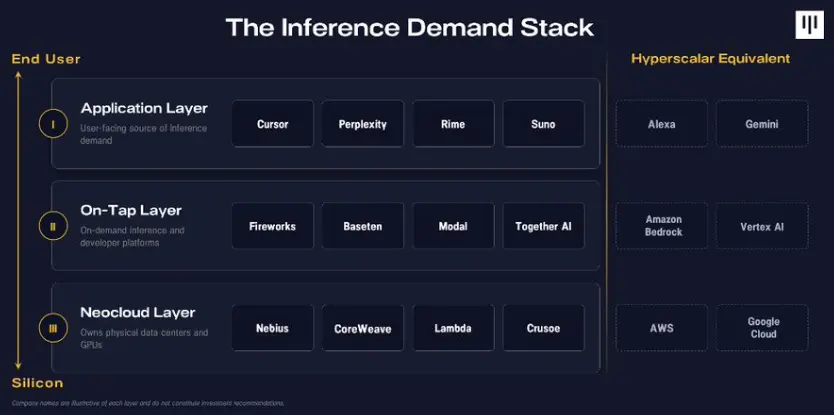
The current inference value chain can be roughly divided into three tiers, which collectively form the structural supply and demand sides within the compute market.
Next-Generation Cloud Provider Tier
Companies such as Nebius and CoreWeave operate physical data centers, forming the sellers of GPUs.
On-Demand Tier
Developer platforms like Fireworks and Baseten transform bare-metal GPU environments into more complete runtime ecosystems, enabling developers to execute tasks directly or access inference tokens on demand. This tier acts as the buyer of GPUs.
Application Tier
Applications such as Cursor, Perplexity, and Rime utilize inference platforms to deliver final products to users and enterprises. This tier represents the demand side for tokens, and token demand subsequently translates into demand for GPU compute.
Although each company in the ecosystem employs different GPU management strategies, overall, next-generation cloud providers occupy the supply side of the GPU market (structural short), while the on-demand and application tiers reside on the demand side (structural long).
On the other hand, hyperscale cloud providers like Amazon and Google operate their own offerings across all three tiers.
Regarding profit flows along the value chain, a rough rule of thumb is that for every $100 spent on tokens by top-tier applications, approximately $45 flows to the on-demand tier, $50 flows to next-generation cloud or GPU layers, and the remaining $5 flows to routing layers like OpenRouter.
2.2 Structure of the Compute Capital Market
The token economics of various participants in the AI value chain will shape how the compute capital market ultimately forms.
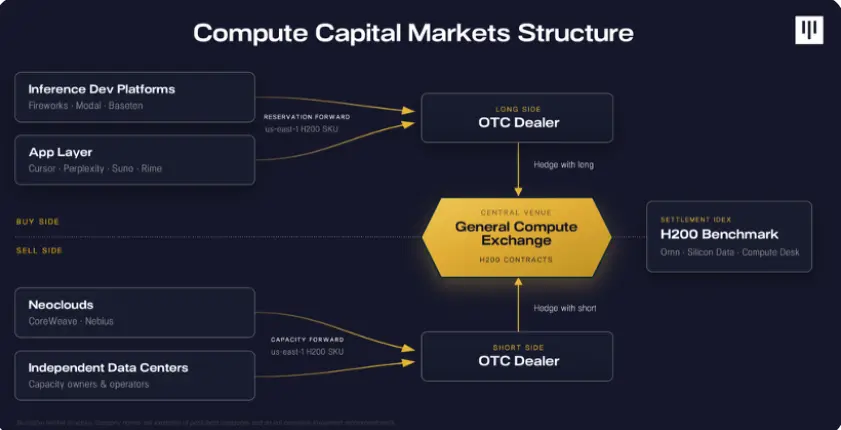
One plausible structure involves developer platforms and application tiers on the demand side, alongside next-generation cloud providers on the supply side, transacting specific SKUs through compute brokers and OTC trading platforms such as SF Compute, Runpod, and Compute Exchange.
Subsequently, compute brokers and OTC trading platforms manage inventory and absorb the basis risk associated with delivering specific SKUs required by end-token consumers versus generic H200 instances.
They can then hedge these exposures through compute trading platforms like Architect or Pluto.
Pricing on these trading platforms is anchored to a compute benchmark, calculated as a weighted average of order book prices from partnered next-gen cloud providers and OTC platforms.
2.3 NVIDIA: The "Central Bank" of the Compute Market
Additionally, NVIDIA recently announced plans to allow compute from its AI factories to function as a "tradable asset class."
Within the compute financialization framework, NVIDIA can be viewed as the "central bank" of the compute market, given its near-monopoly over the GPU technology stack.
Central banks typically pursue several core objectives:
- Manage inflation in the economy;
- Promote full employment;
- Act as a lender of last resort in extreme circumstances.
NVIDIA is, to some extent, fulfilling all three roles.
First is managing "inflation." In the GPU economy, "inflation" parallels the depreciation cycle of GPUs, particularly the pace at which older chips devalue against generations. By controlling product release cadences, such as the launch of Vera Rubin, NVIDIA can influence the rate at which GPU values depreciate over time.
Second is maintaining high GPU utilization. High utilization rates typically signal strong market demand for tokens, prompting users to acquire more GPUs. Therefore, NVIDIA has incentives to drive GPU compute financialization, making GPU hour trading more liquid, thereby further boosting utilization rates.
Third is acting as a lender of last resort. NVIDIA has also announced it will provide support covering up to 25% of the residual value of GPUs. This functions as a rescue or insurance mechanism for GPU assets: when next-generation cloud providers and other GPU suppliers face liquidity crunches, such backing guarantees the residual value of the hardware.
3. Opportunities and Challenges in the Compute Market
3.1 Product Modalities in the Compute Market
As financialization intensifies within the compute market, several primary product categories are likely to emerge. Each carries its own advantages and challenges.
Product One: Physical Delivery
Physical delivery involves transferring actual GPU hardware to end-users requiring compute. Projects such as SF Compute, Hyperbolic, Vast, Runpod, and Compute Exchange fall into this category. This is the layer closest to the hardware itself and most directly connects the supply and demand sides of compute.
Due to the high heterogeneity of compute SKUs, many projects initially operate merely as brokers, earning commissions by matching GPU demand with next-generation cloud providers. In the long term, this layer aims to establish some form of "compute spot exchange."
However, consistently ensuring the quality of physical GPU delivery poses significant challenges, particularly for projects sourcing supply from decentralized networks. The compute market may require a rating agency akin to Moody's to certify the quality of underlying deliverable GPUs before this layer can mature.
Despite intense competition at the physical delivery layer, it may ultimately possess the most durable competitive moat. Examining oil and electricity markets reveals that financialization frameworks typically evolve around venues with the strongest physical liquidity, only later giving rise to indices, exchanges, and lending products.
Consequently, whoever successfully resolves physical compute delivery issues first is likely to capture substantial market rewards.
Product Two: Indices
This tier primarily refers to "index curves" built upon compute, including compute price indices launched by projects such as Ornn, Silicon Data, Compute Desk, and Semianalysis.
Establishing indices marks a crucial step toward further financializing and tradable commodification of compute. Much of the current market discourse surrounding "the compute market" has intensified alongside the maturation of compute indices. Major exchanges like CME and ICE have also announced partnerships with relevant indices.
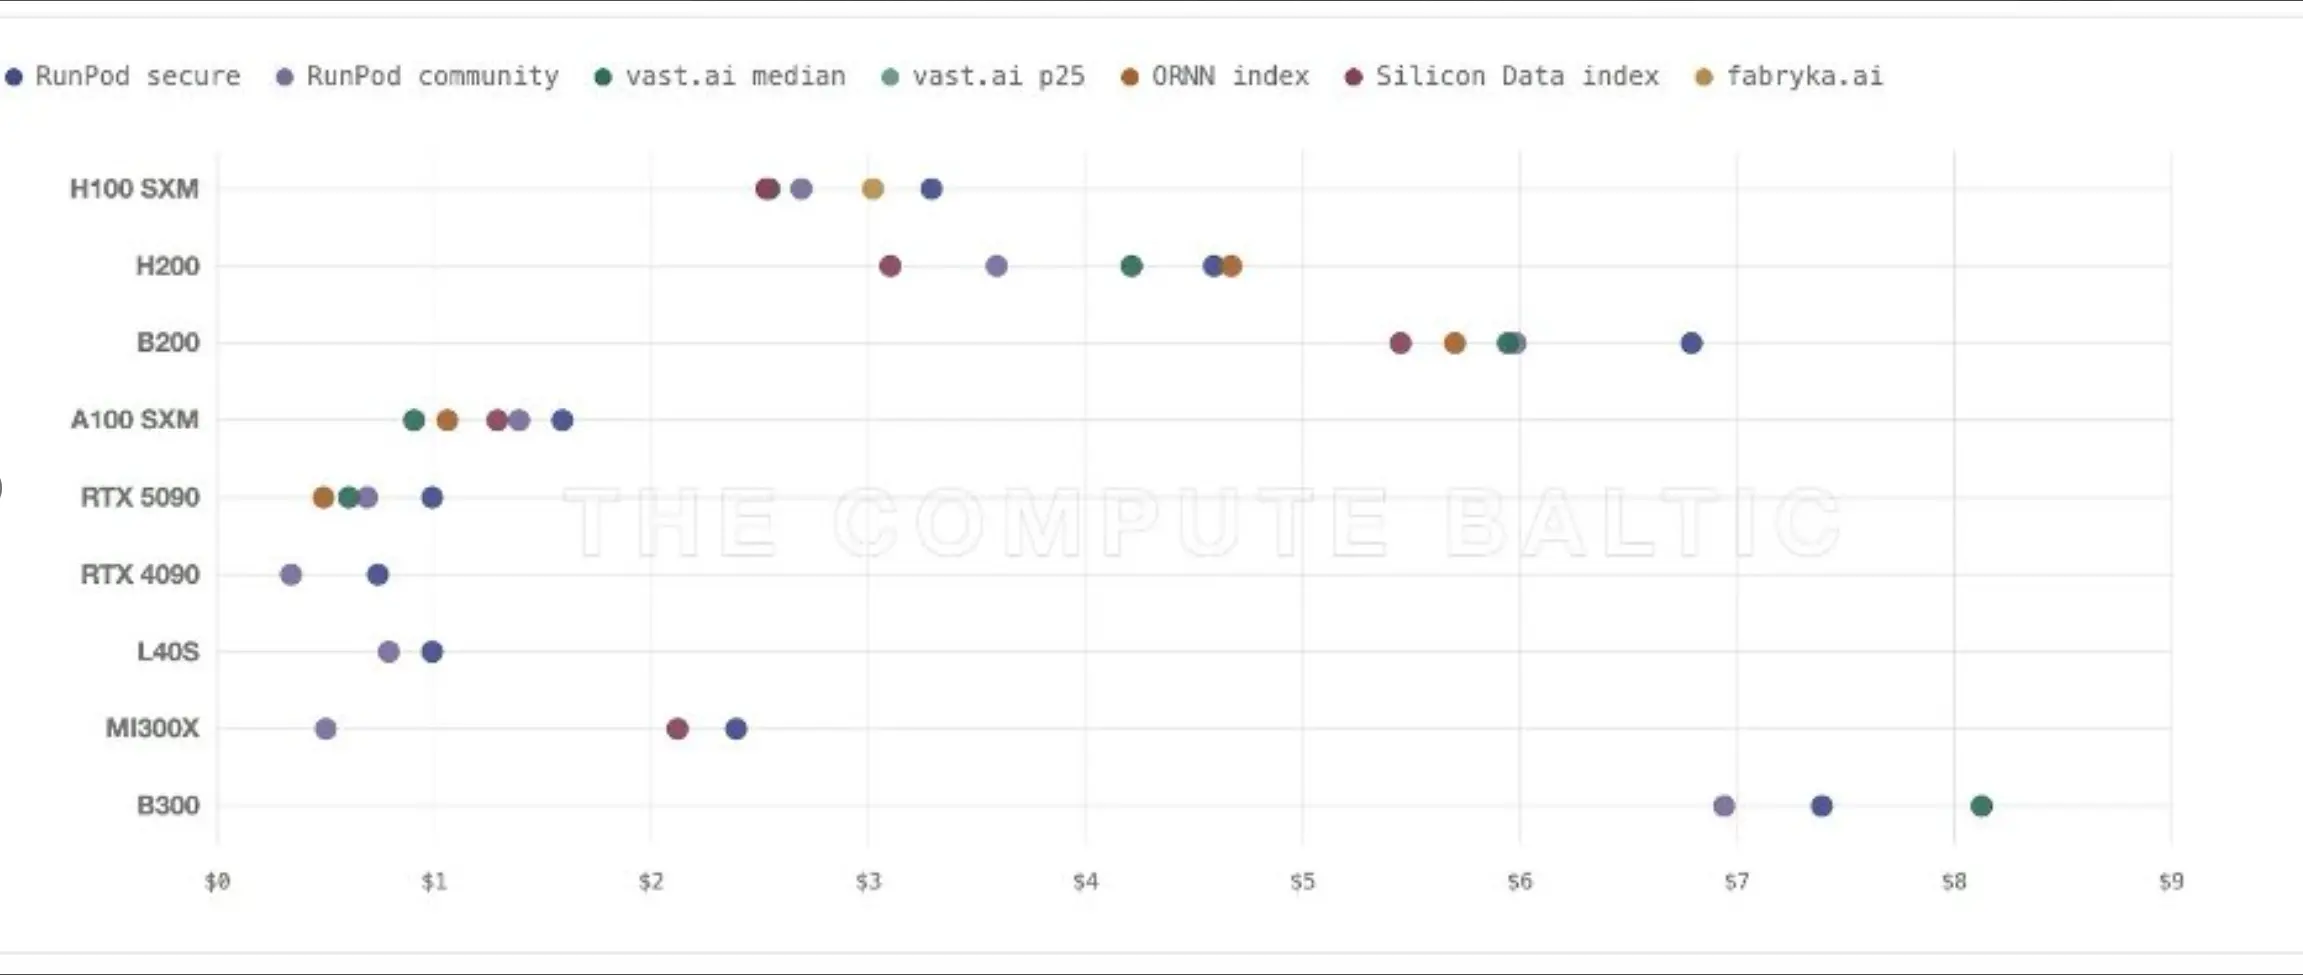
Nevertheless, significant pricing discrepancies currently persist between many compute indices and individual GPU spot markets.
Two primary factors likely contribute to these discrepancies.
First, the underlying products themselves differ. Various compute platforms often vary substantially regarding uptime guarantees, interruptibility, and contractual terms.
Second, the order books underpinning different compute indices are not identical, and the compute market lacks transparency mandates seen in other asset classes, such as FERC's requirements for the electricity market.
Many compute indices today simply bulk-purchase order book data from next-gen cloud providers or establish initial datasets through partnerships and revenue-sharing agreements. Furthermore, the monetization potential of operating solely at the index tier is weaker compared to exchanges and physical delivery layers.
Therefore, although the index tier generates significant attention and plays a vital role in the compute ecosystem, it finds itself squeezed by both upstream and downstream forces:
- The upstream physical delivery layer controls the origin of price discovery;
- Downstream exchanges seek to claim a portion of index-generated revenues.
Product Three: Derivatives Trading Platforms
The third tier comprises derivatives trading platforms, which typically offer cash-settled futures contracts. These platforms leverage compute indices to provide hedging instruments for market participants. Projects like Liquid Compute and Architect are actively developing related products.
Long-term, derivatives platforms represent the most anticipated and scalable monetization avenue within compute financialization. However, this sector remains nascent, with trading volumes yet to reach meaningful scales.
Moreover, tradable products on cash-settled platforms generally involve generic H200 instances rather than specific SKUs optimized for direct inference. Consequently, current participants are likely dominated by OTC platforms and compute brokers rather than end-stage AI enterprises. The former seek to hedge compute inventory on their balance sheets, while the latter aim to manage their own compute exposures.
Product Four: Financialization Instruments
The compute sector may also see broader financialization products emerge to support financing for data centers and next-gen cloud providers. For instance, lending protocols, Vault structures, and synthetic stablecoins like USD.AI could assist these entities in funding infrastructure buildouts.
Simultaneously, risk transfer and insurance layers may develop to smooth out basis risks within the GPU economy. Observing these various tiers reveals that the ultimate morphology of the compute market is relatively clear.
The winners will be full-stack participants capable of executing reliable physical GPU delivery. They will derive price indices from their own physical order books, leverage them to launch compute futures exchanges, and render compute a hedgable asset class.
The true point of divergence within the industry lies in the sequencing of these products. Will the eventual winner begin with physical delivery, establish indices first, or launch trading platforms ahead of others?
3.2 Frontiers of Compute Token Economics
Thus far, our discussion has centered on the compute market at the GPU level. We can also zoom out to examine broader compute token economics, encompassing historical evolution, value capture mechanisms, and strategic dynamics with frontier model labs.
From a historical perspective, the compute market is not a novel concept. As early as 2023–2024, projects like SF Compute and Hyperbolic were exploring this model, while decentralized initiatives such as Akash and IONet were pursuing similar trajectories.
Interestingly, many projects ultimately did not remain confined to the GPU market layer. For example, Hyperbolic pivoted to become an inference service provider, selling tokens directly, whereas SF Compute moved upstream to directly contract and operate compute clusters.
Viewed through the value chain, capital flows from AI applications like Cursor, Harvey, and Granola to routing layers such as OpenRouter, then to inference providers like Fireworks and Baseten, onward to next-gen cloud providers and compute markets like Nebius, CoreWeave, and SF Compute, and finally settles with data center operators.
Companies that remain stuck in the middle of the value chain face margin compression from both upstream and downstream competitors. To sustain more stable profitability, firms will likely need to either integrate upstream or expand downstream.
The token market presents another fascinating game-theoretic perspective, featuring three immovable forces.
The first force is NVIDIA, which controls GPU supply and depreciation velocity.
The second force comprises frontier model labs like Anthropic and OpenAI, whose continuous model releases can rapidly spike token demand.
The third force stems from open-source models such as Kimi, GLM, DeepSeek, and Qwen, which exert downward pressure on inference profit margins.
These three forces jointly exert continuous momentum and pressure on both supply and demand sides of the GPU and token markets. Any single entity could redraw the market's entire pricing curve by launching a pivotal product.
For instance, the release of GPT 5.6 could materialize as a company-driven, unforeseeable event that triggers cascading effects along the AI token value chain, causing volatility in both token pricing and GPU hardware costs.
Therefore, it makes commercial sense for a company to simultaneously operate both inference services and the GPU hardware market within the same ecosystem. This dual-operation model effectively hedges against risks arising from shifting profit structures across the upstream and downstream value chain.
Conclusion
Looking back at history, commodity markets like oil and electricity initially relied heavily on opaque, intermediary-matched bilateral trades lacking unified standards. Over time, however, physical delivery evolved to spawn indices, standardized trading protocols, quality auditing frameworks, and broader financial infrastructure, ultimately transforming into highly financialized asset classes.
Today, the compute market is undergoing a parallel transformation. Numerous projects are actively building foundational financialization tools, including compute indices, cash-settled exchanges, lending products, and insurance solutions.
Simultaneously, physical GPU markets and cloud providers are continuously extending their reach across the value chain, striving to capture the full value of the token economy. As the foundational resource underpinning the entire AI economy, compute is transitioning from mere infrastructure into a standalone financial asset.
In the future, this sector may birth multiple unicorn companies, each targeting distinct layers of the market and cultivating varied business models encompassing physical compute supply, brokerage services, lending, risk management, and integrations with both DeFi and TradFi capital markets.
Compute stands as one of the rare new physical commodities of the past few decades, and we may well be witnessing the genesis of its transition from discreet, brokered early trades into a fully realized asset class.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 Pantera Capital
















