


Bitget UEX Daily Report | Oil prices drop 2% as US and Iran plan to resume negotiations; South Korea's DRAM export prices surge 401% year-on-year; Nvidia ends seven-day losing streak ahead of earnings report

I. Key Headlines
Federal Reserve Developments
Kevin Warsh's Jackson Hole Speech Approaches, ~60% Probability of Rate Hold in September
- Federal Reserve Chairman Kevin Warsh will deliver a speech at Jackson Hole on August 28, with markets continuing to seek his stance on inflation and fiscal issues.
- Data from CME shows a ~60.4% probability of no rate change in September, with a cumulative 25-basis-point hike probability at ~39.6%.
- Several officials, including Richmond Fed Chairman Barkin, will also speak this week.
Market Impact: Speeches and core PCE data jointly form the core of short-term policy pricing, potentially affecting term premiums and risk asset performance.
International Commodities
Russian Media Reports US-Iran Talks to Resume, Crude Oil Drops Significantly
- Iran and Oman discussed establishing a temporary navigation corridor in the Strait of Hormuz and mine-clearing plans, aiming to advance permanent routes within 30 to 60 days.
- Sources from Pakistan and Iran revealed that the US and Iran reached consensus on ceasefire agreement terms, including freedom of navigation through the strait, expected to be announced and negotiations initiated in the coming days.
- US Secretary of State Rubio stated there are currently no plans for a new military strike on Iran, shifting focus to naval blockades and Treasury sanctions; Trump claimed all international waters mines have been cleared.
Market Impact: Rapid erosion of geopolitical risk premiums, WTI crude down nearly 2%, Brent cools in tandem, easing near-term inflation stickiness concerns and benefiting risk assets.
Macroeconomic Policy
Canada Imposes Retaliatory Tariffs on US Goods, US Considers Further Measures
- Starting Sept 8, Canada will impose 15%-50% tariffs on ~$20 billion worth of US goods, with metals facing up to 50%, alongside providing $7.5 billion CAD in support funds.
- The US government is discussing additional punitive measures against Canada, potentially escalating trade friction.
Market Impact: Intensifying North American trade tensions may impact related supply chains and market sentiment, though partially offset by short-term US-Iran détente news.
II. Market Review
Commodities & Forex Performance
- Spot Gold: ~$4,650/oz, -0.25%
- Spot Silver: ~$68.6/oz, +0.05%
- WTI Crude: ~$80.47/bbl, -2.12%
- Brent Crude: ~$83.4/bbl, -2.12%
- US Dollar Index (DXY): ~98.93, +0.02%
Driver Analysis: Expectations of resumed US-Iran talks significantly reduced the Hormuz risk premium, making the sharp drop in crude oil the dominant factor. Gold fluctuated between falling oil prices and safe-haven demand, while silver remained relatively independent due to its industrial attributes. Institutional views suggest commodities are short-term driven by geopolitical détente, with falling oil helping alleviate inflation and rate hike expectations. Asset linkage manifests as geopolitical cooling → falling oil prices → eased inflation concerns → support for risk assets.
Cryptocurrency Performance
- BTC: ~$78,770, -1.17%
- ETH: ~$2,475.4, -1.37%
- Total Crypto Market Cap: $2.73T, -1.9%
- Liquidation Status: $624M liquidated in 24h, including $322M in long positions
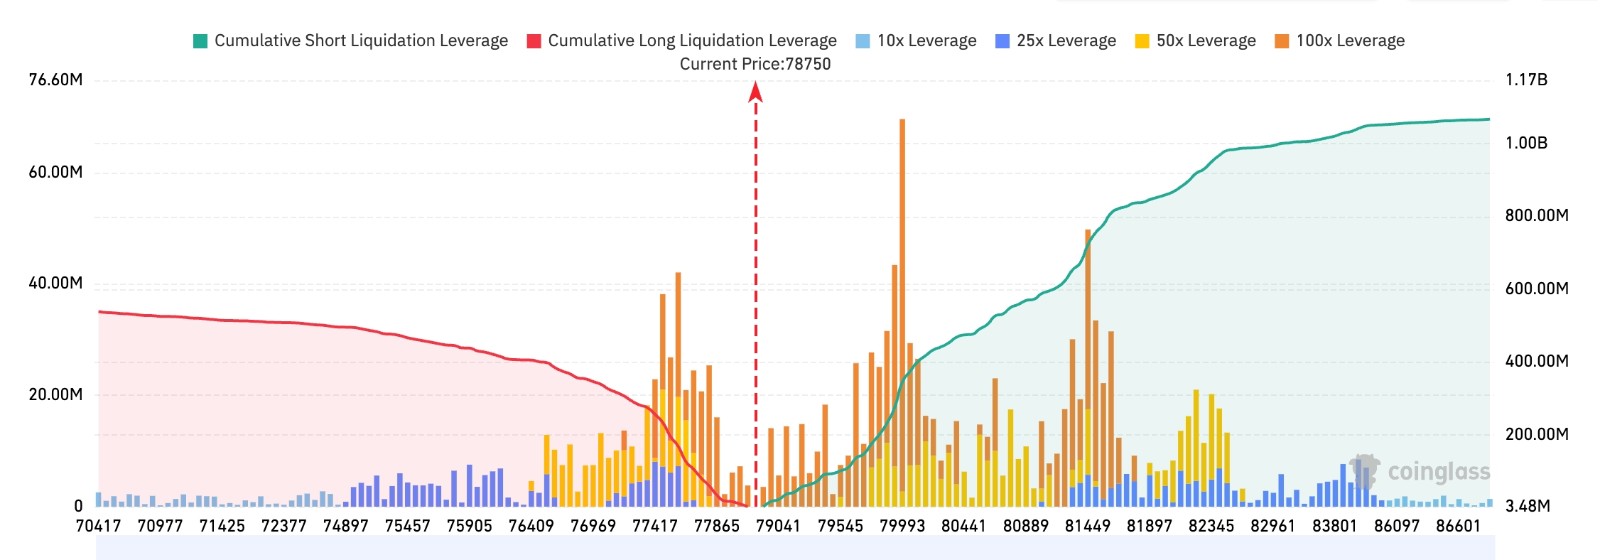
- Bitget BTC/USDT Liquidation Map: BTC currently trades around $78,800. Significant short liquidation pressure clusters above the $80,000–$81,500 range; a breakout above $80k could trigger a notable short squeeze. Below, dense long liquidations exist between $77,000–$79,000; a break below ~$78,000 support could further accelerate leveraged long exits.
- Spot ETF Inflows/Outflows: Maintained inflows recently, with yesterday's net inflow at $338M and current 24-hour net inflow at $29.9M.
Driver Analysis: US-Iran détente and falling oil prices boosted risk appetite, with the crypto market oscillating at highs following suit. BTC once tested the $80k mark, with ETH showing relative synchronization. Institutional consensus points to short-term support from liquidity and policy narratives, requiring attention to macro transmission following core PCE and Jackson Hole speeches.
US Stock Index Performance
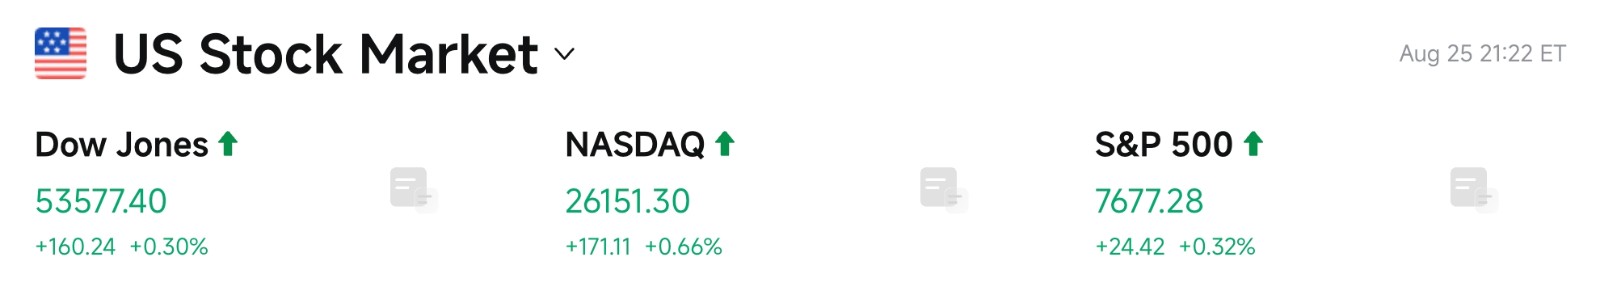
- Dow Jones: Closed at 53,577.40, +0.30%
- S&P 500: Closed at 7,677.28, +0.32%
- Nasdaq: Closed at 26,151.30, +0.66%, with tech and semiconductors rebounding
Tech Giant Developments
- NVDA: $213.05, +2.19% (ended seven-day losing streak)
- AAPL: $309.90, -0.14%
- MSFT: $491.71, +0.90%
- GOOGL: ~$347, slight decline
- AMZN: $261.06, -0.39%
- META: $570.05, +1.97%
- TSLA: $350.25, +0.37%
Performance Summary & Driver Analysis: All three major indices rose, with the tech sector rebounding after NVIDIA ended its losing streak. Memory and optical communication sectors saw broad gains, with AMD rising nearly 5%. Funds flowed back into growth stocks amid US-Iran détente and falling yields, though individual stock divergence persists, with consumer tech remaining relatively stable.
Sector Movement Observations
Semiconductors/Memory Collective Rebound
- Representative Stocks: AMD up nearly 5%, Micron and SK Hynix up over 2%, Seagate and Western Digital up over 3%.
- Drivers: South Korean DRAM export prices surging 401% YoY reinforced tight supply-demand narratives, compounded by NVIDIA's rebound boosting sentiment.
Optical Communications Strong Surge
- Representative Stocks: Lumentum up nearly 7%, Applied Optoelectronics up over 5%, Coherent, Ciena up over 4%.
- Drivers: Technical repair after prior significant pullbacks alongside expectations for AI infrastructure demand.
Crypto Concept Stocks Strong
- Representative Stocks: Robinhood up over 8%, Circle, Coinbase up over 4%, Strategy up over 3%.
- Drivers: BTC trading at highs and recovering risk appetite.
III. In-Depth Analysis of US Stocks
1. NVIDIA (NVDA) - Ends Seven-Day Losing Streak, Earnings Release Upcoming
Event Overview: NVIDIA rose over 2%, ending seven consecutive days of declines. The company simultaneously launched the Jetson Orin Nano 2 robotic computer, featuring 78 TOPS compute power, 8GB memory, and an octa-core Arm CPU. Inference performance improved 2x compared to the previous generation, with power consumption reduced by 40% in 15W mode, primarily targeting robotics, drones, and edge AI applications, with mass production expected in the first half of 2027. After-hours Q2 earnings will be released, with markets focusing on data center revenue, gross margins, and forward guidance.
Market Interpretation: Institutions believe the rebound after consecutive declines reflects sentiment repair and earnings expectation speculation. New Jetson products strengthen edge AI and physical AI layouts, while server price hikes help pass on memory costs. Analysts watch whether customer capex slows and competition intensifies, with earnings guidance becoming key for short-term pricing.
Investment Insights: Mid-term logic remains focused on AI infrastructure and robotics demand, but closely track data center growth rates and guidance changes in tonight's earnings.
2. AMD - Surges Nearly 5%
Event Overview: AMD rose nearly 5%, leading the semiconductor sector. The company announced introducing UCIe interconnect technology to Versal adaptive SoCs, supporting low-power high-bandwidth chiplet communication; simultaneously upgraded to "Strong Buy" by Raymond James with a price target raised to $641. Helios rack-level AI platform expected to begin shipments in September.
Market Interpretation: Institutions are optimistic about progress in AI server CPUs and complete rack solutions, with valuation attractiveness improving after prior pullbacks. Analysts emphasize year-over-year doubling of data center business growth and OpenAI, Meta, etc. design wins, suggesting a multi-vendor landscape benefits AMD's share gains.
Investment Insights: As a focus for diversified AI compute allocation,重点关注 (focus on tracking) Helios shipment pace and data center revenue proportion.
3. Micron Technology (MU) - Tight Memory Logic Strengthens
Event Overview: Micron rose over 2%, with broad memory sector gains. South Korean DRAM August export unit price reached $92,183/kg, surging 401% YoY, up ~12.5x from 2023 lows. Goldman Sachs predicts global DRAM supply-demand gap expands from 5.0% this year to 5.9% next year, possibly extending to 2028; TrendForce notes Samsung, SK Hynix, and Micron's HBM wafer investment share will rise to 30%.
Market Interpretation: Institutions raised optimism levels for the memory supercycle, believing HBM and large-capacity server DRAM continuously absorb capacity, tightening ordinary DRAM supply. Analysts note significantly enhanced pricing power but warn of cycle risks from capacity release post-2027.
Investment Insights: Tight supply-demand provides mid-term support; follow contract prices and capacity expansion progress, avoiding pure momentum chasing.
4. Lumentum / Applied Optoelectronics - Optical Communication Repair
Event Overview: Lumentum up nearly 7%, Applied Optoelectronics up over 5%, Coherent and Ciena synchronously up over 4%, with the optical communications sector collectively rebounding.
Market Interpretation: Institutions view this as a technical repair after prior deep pullbacks; the logic of AI data centers demanding 800G/1.6T optical modules and high-speed interconnects remains intact. Analysts monitor order backlogs and capacity landing progress; short-term elasticity is high but volatility is significant.
Investment Insights: High-beta thematic allocation, suitable for investors with higher risk tolerance, requiring monitoring of industry cycles and competitive landscapes.
5. Robinhood (HOOD) - Crypto Concepts Lead Gains
Event Overview: Robinhood rose over 8%, Circle and Coinbase up over 4%, Strategy up over 3%, with crypto concept stocks collectively strengthening.
Market Interpretation: BTC maintaining highs and recovering risk appetite directly boosted trading platforms and bitcoin holding-related targets. Institutions point out regulatory clarity expectations (Clarity Act) and trading volume elasticity as core drivers, highly correlated with BTC prices in the short term.
Investment Insights: Targets with dual high-elasticity policy and crypto price drivers, significantly volatile, requiring strict position management and tracking of key BTC technical levels.
IV. Market & Project Developments
1. Bloomberg ETF analyst Eric Balchunas stated that gold ETF GLD and Bitcoin ETF IBIT returned to the top ten trading volume list, pushing aside semiconductor ETFs that dominated throughout the summer. This is another signal that "devaluation trades" are beginning to replace AI mania—investors are shifting from chasing AI growth to hard-asset preservation. Semiconductor ETFs maintain high trading activity but have declined compared to summer peaks.
2. South Korea DRAM August export prices surged 401% YoY, reinforcing tight supply-demand expectations through 2027.
3. According to Russian Sputnik News, sources from Pakistan's military and Iran's security departments revealed that the US and Iran reached consensus on ceasefire agreement terms, including freedom of navigation in the Strait of Hormuz. Sources said, "Consensus reached on ceasefire agreement, including free navigation terms for the Strait of Hormuz."
4. Morgan Stanley reported that off-balance-sheet AI-related commitments from the top five cloud vendors, NVIDIA, and Broadcom exceeded $3.1 trillion.
5. Anthropic estimates a potential market size exceeding $30 trillion, with IPO valuation possibly reaching $2 trillion.
6. Apple (AAPL.O) released M6 and M5 Ultra chips, simultaneously launching new Mac mini and Mac Studio models. Among them, M6 is Apple's first 2-nanometer process chip, equipped with 12-core CPU, 12-core GPU, and dual 16-core Neural Engines; M5 Ultra uses quad-die architecture for the first time, featuring up to 36-core CPU, 80-core GPU, 512GB unified memory, and 1.2TB/s memory bandwidth.
V. Today's Market Calendar
Data Release Schedule
| Evening | US | July Core PCE Price Index | ⭐⭐⭐⭐⭐ |
Key Events Preview
August 26 (Wed)
★★★★★ US releases July Core PCE, Personal Income & Spending, Q2 GDP Revised, Durable Goods Orders; ★★★★★ NVIDIA (NVDA) after-hours earnings release (core focus on data center revenue, gross margin, and forward guidance); ★★★ CrowdStrike, Salesforce after-hours earnings release
August 27 (Thu)
US releases Initial Jobless Claims, Trade Balance, Wholesale Inventories; Jackson Hole Symposium opens; ★★★ Marvell (MRVL), Ulta, Gap etc. after-hours.
August 28 (Fri)
★★★★★ Fed Chair Warsh delivers keynote speech at Jackson Hole (10:00 PM Beijing Time), markets focus on his stance on inflation and policy path; US releases Chicago PMI, Nonfarm Payroll Benchmark Revision Preliminary, University of Michigan Consumer Confidence Final.
Institutional Views:
Investment bank analysts believe that expectations of resumed US-Iran talks significantly reduce geopolitical risk premiums, with falling crude oil helping alleviate inflation concerns and boosting risk appetite. South Korean DRAM price surges reinforce tight memory supply-demand narratives, driving rebounds in semiconductors and optical communications. NVIDIA ends its losing streak and releases earnings soon, becoming the short-term focus. Crypto market maintains highs. Overall strategy suggests focusing on core PCE results, NVIDIA guidance, and Jackson Hole speech, maintaining flexibility for high-valuation growth stocks while observing asset rotation post-energy decline.
Disclaimer: The above content is compiled and organized by AI search, manually verified only for publication, and does not constitute any investment advice. Data in the article inevitably contains discrepancies; please refer to real-time market data.














