Bernstein Report Analysis: FY2028 Revenue to Exceed $740 Billion, Yet Only Neutral Rating for Nvidia
NVIDIA (NVDA) delivered $115.8 billion in revenue in Q3 FY2027, with FY2028 revenue projected to surpass $740 billion. Results beat expectations across the board, but Bernstein analyst Stacy A. Rasgon maintained a 'Market-Perform' rating and a $200 target price in a Nov. 18 report. He noted that long-term execution and governance risks following the management changes have not yet dissipated.
New Architecture Generates $20 Billion in a Single Quarter
For Q3 FY2027 ending late October 2026, NVIDIA posted results significantly exceeding market consensus. Total revenue reached $115.84 billion, $6.5 billion above the consensus estimate of $109.33 billion. Adjusted EPS came in at $2.68, also beating the expected $2.47.
The core growth engine remains the Datacenter business. This segment contributed $107.61 billion in quarterly revenue, representing a 21% quarter-over-quarter increase and a 110% year-over-year surge.
The next-generation Vera Rubin architecture achieved the company's fastest production ramp to date, generating approximately $20 billion in revenue within the quarter. Meanwhile, Blackwell Ultra chips continue to maintain strong shipment momentum.
Breaking down the customer mix, both Hyperscale cloud providers and ACIE (AI Cloud and Enterprise) customers continue to expand at high speeds.
Revenue from the cloud provider segment hit $60.136 billion for the quarter, up 23% sequentially and 71% year over year. Revenue from the AI Cloud and Enterprise segment reached $47.474 billion, rising 18% sequentially and surging 195% year over year. Networking revenue also reached approximately $21 billion for the quarter.
Profitability remains equally robust. Driven by a favorable product mix including Blackwell Ultra, adjusted gross margin for the third quarter reached 74.9%, ahead of the consensus estimate of 74.0%. Edge Computing revenue (encompassing gaming, professional visualization, automotive, and OEM businesses) came in at $8.234 billion for the quarter, up 14% sequentially and also beating the $7.5 billion market expectation.
Fourth-Quarter Guidance Inflated by Extra Week
NVIDIA provided Q4 FY2027 revenue guidance of $130 billion (±2%), above the market consensus estimate of $125.1 billion. The company's implied adjusted EPS guidance stands at approximately $2.86, beating expectations of $2.75.
The report breaks down the composition of the fourth-quarter guidance. While $130 billion looks impressive on the surface, it includes an extra accounting week.
Bernstein estimates that this extra week brought approximately $5 billion to $10 billion in additional revenue. If this half-to-one-week calendar tailwind is excluded, NVIDIA's normalized fourth-quarter revenue guidance actually falls slightly below market consensus.
Another detail is that Q3 Datacenter revenue beat expectations partly due to approximately $2.4 billion in Hopper chip sales to the Chinese market (this revenue was not originally factored into the Q3 guidance, pushing China's revenue share up from 8% in Q2 to 10%). However, NVIDIA explicitly stated that the Q4 guidance no longer includes any revenue from Hopper products like the H200 sold to China.
Regarding margins, Q4 adjusted gross margin guidance is set at 71.5%, slightly below the market expectation of 71.7%. The report anticipates this marks the bottom of the gross margin cycle for this period, with margins expected to rebound to the 72%-73% range as pricing adjustments take effect in Q1 FY2028.
FY2028 Guidance Upwardly Revised
Despite the somewhat muted appearance of the fourth quarter after excluding the extra week, NVIDIA significantly raised its long-term outlook for FY2028 (corresponding to calendar year 2027). Management expects revenue growth for FY2028 to reach approximately 75%, surpassing the previously estimated growth rate of around 70%.
Accelerating growth on already massively elevated results means NVIDIA's total revenue for FY2028 will exceed $740 billion. Management acknowledged that the new round of export controls by the U.S. Bureau of Industry and Security (BIS) will indeed have an impact, but currently, global compute capacity orders remain severely oversubscribed. External demand is sufficient to completely offset the losses from export restrictions.
Huge order visibility is also reflected in supply chain commitments. As of the end of Q3, NVIDIA's overall supply commitments have surged to $390 billion. Including cloud service agreements, data center leases, and equity investments, the total commitment scale reaches an astonishing $518 billion.
NVIDIA's total inventory for the quarter also rose from $31.6 billion in Q2 to $39.7 billion, with inventory turnover days increasing slightly from 118 to 123 days, as the company ramps up stockpiling in preparation for a full-scale rollout of Vera Rubin.
Cash flow and shareholder returns remain abundant. The company generated $43.8 billion in free cash flow during the quarter, spent $22.1 billion on share buybacks, and authorized a record-breaking $150 billion stock repurchase program. Based on these results, Bernstein has upwardly revised its FY2028 revenue forecast for NVIDIA from $690.3 billion to $742.4 billion, and its adjusted EPS forecast from $15.80 to $17.18.
Governance Uncertainties After Jensen's Departure
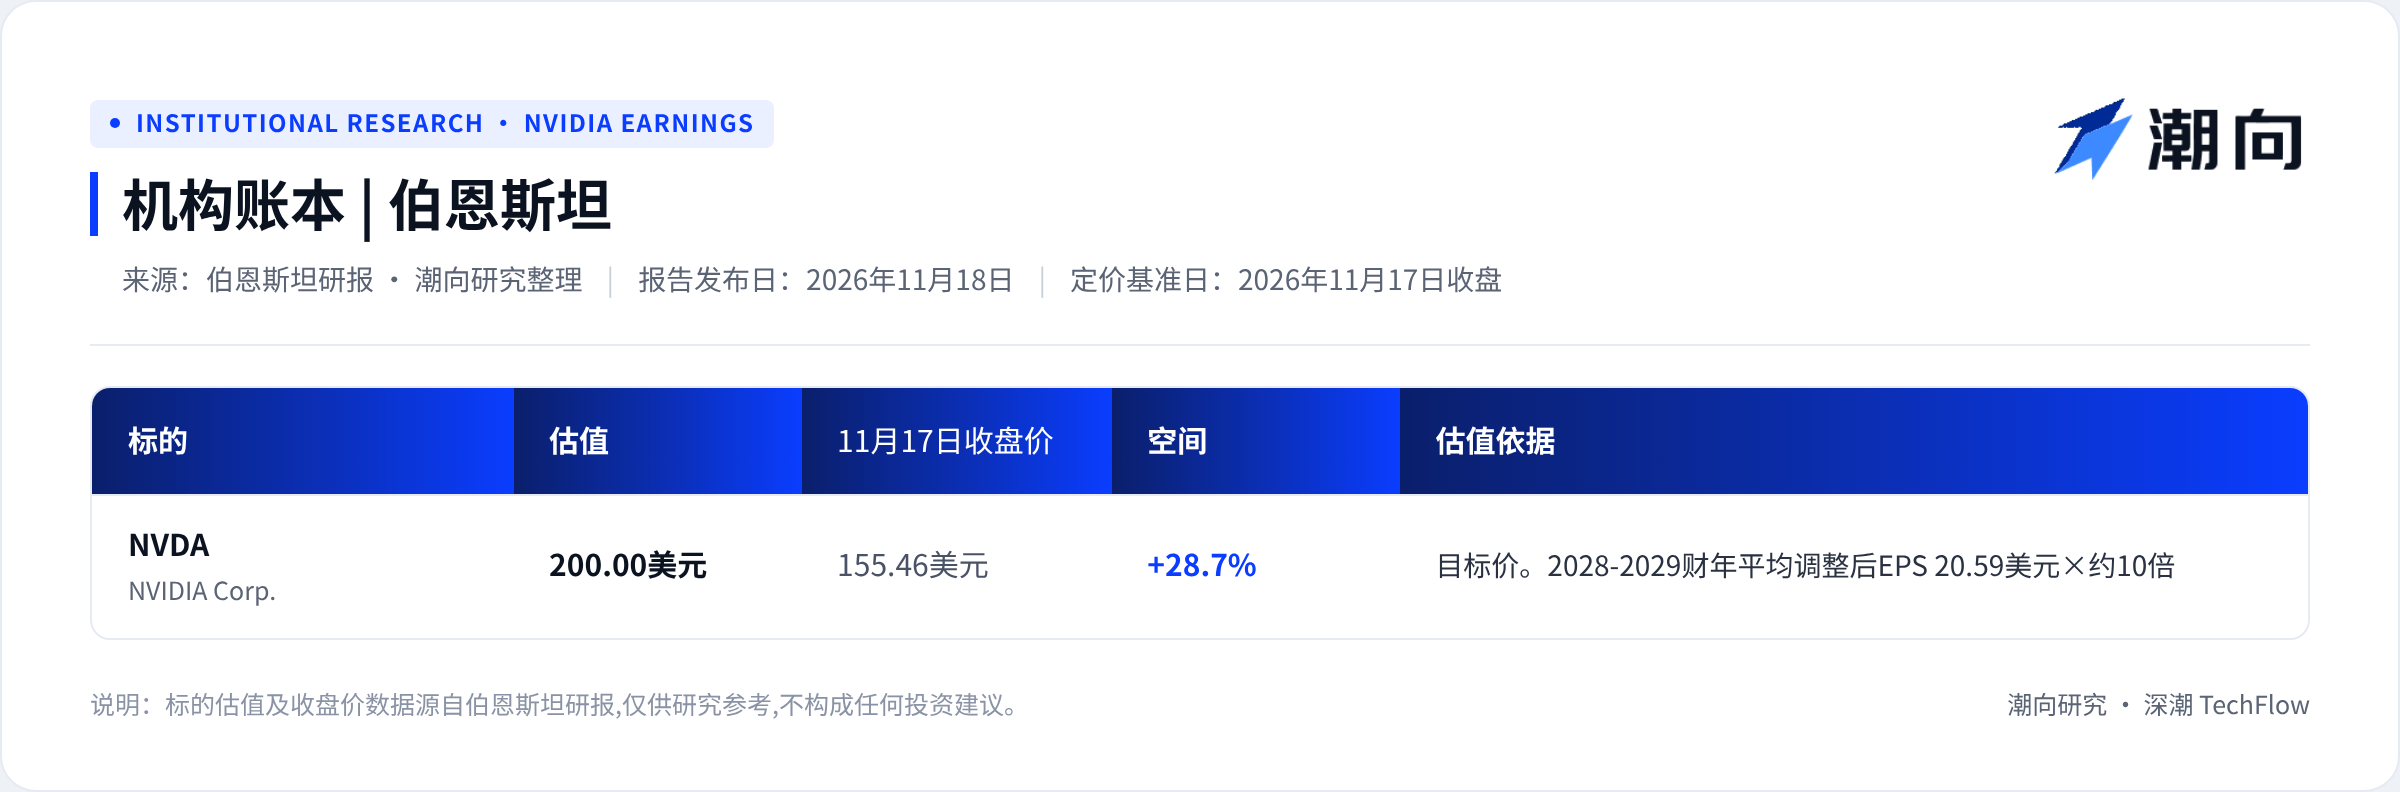
While the fundamental data is flawless, Bernstein's stance on the stock remains exceptionally cautious. In its Nov. 18 report, the firm maintained a 'Market-Perform' rating and a $200 target price.
The report notes that following recent executive turmoil, the strong numbers for Q3 and Q4 are hardly surprising, given that too little time has passed for business inertia to change. During the earnings call, Colette fulfilled her short-term mission, reassuring the market with signals that 'the big ship continues to sail steadily.'
However, simultaneously, the newly appointed chairman of the board clearly stated on the call that the current board has no intention of bringing Jensen Huang back and is actively searching for a new leader.
This is precisely the crux behind Wall Street's hesitation to assign a premium valuation. Without Jensen Huang, NVIDIA faces unknown challenges in future supplier negotiations, long-term product roadmap formulation, maintaining wartime decision-making speed, and retaining core R&D talent. Additionally, the potential investigation risks surrounding the recent controversies have not yet been fully cleared.
NVIDIA's stock currently trades around $155.46, implying a P/E ratio of just 9.0x based on Bernstein's FY2028 adjusted EPS forecast. Even calculating against the $200 target price, it represents roughly a 10x valuation relative to Bernstein's average FY2028-FY2029 adjusted EPS of $20.59.
Until time provides the answer, Bernstein chooses to continue watching from the sidelines.
Institutional Ledger
This article is a compilation and interpretation of third-party brokerage research reports by TechFlow Research. The ratings, target prices, earnings forecasts, and related judgments cited herein are solely the views of the respective brokerage analysts, representing only their institution's stance, not those of TechFlow Research, and do not constitute any investment advice.
Markets carry risks, and decisions must be independent. This article should not serve as a basis for buying or selling any securities.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @chaoxiangooo