Interview with WasabiCard CEO: Why Is Global Payroll Becoming the Core Use Case for Stablecoin Payment Infrastructure?
Author: TechFlow
Companies are accelerating their shift from localized operations to globally distributed operations.
This observation is not held solely by WasabiCard Co-founder and CEO Ray Yang.
According to Frost & Sullivan's Q4 2025 report, the global remote work market size has surged from $45.2 billion in 2023 to $68.5 billion in 2025. Meanwhile, Gartner research data indicates that over 58% of organizations have begun hiring tech talent across borders.
The convergence of post-pandemic remote work, digital nomadism, and AI-driven organizational efficiency reshaping creates a triple force pushing enterprises toward greater globalization.
Personnel are becoming dispersed, businesses are going global, and capital flows are growing more complex, yet the payment system remains stuck in the past: it is still constrained by national borders, designed around interbank fund transfers, and characterized by inefficiency, high costs, and high friction.
This gap is precisely the void WasabiCard is stepping into.
As a stablecoin-powered enterprise-grade global payment infrastructure, WasabiCard recently closed a nearly $10 million Pre-A funding round this June, serves over 700 enterprise clients across 200+ countries and regions worldwide, has issued over 700,000 cards globally, and processed cumulative transaction volumes exceeding $1 billion.
From solving payment friction caused by globalized organizations, to stablecoin-driven fund settlement, down to the practical application of Global Payroll—the most representative use case—WasabiCard has consistently been addressing the same question:
What should payment infrastructure look like when companies truly go global?
With these questions in mind, TechFlow sat down for an in-depth conversation with WasabiCard CEO Ray Yang.

Global Enterprise Organizations, The Old Payment System Is Starting To Fail
TechFlow: Congratulations on WasabiCard's recent nearly $10 million Pre-A funding round. In the current investment environment, this itself is a noteworthy signal.
Given this, could you first briefly introduce WasabiCard? And in your view, what are institutions essentially betting on by choosing WasabiCard at this point?
Ray Yang:
Hello everyone, I'm Ray Yang, Co-founder and CEO of WasabiCard.
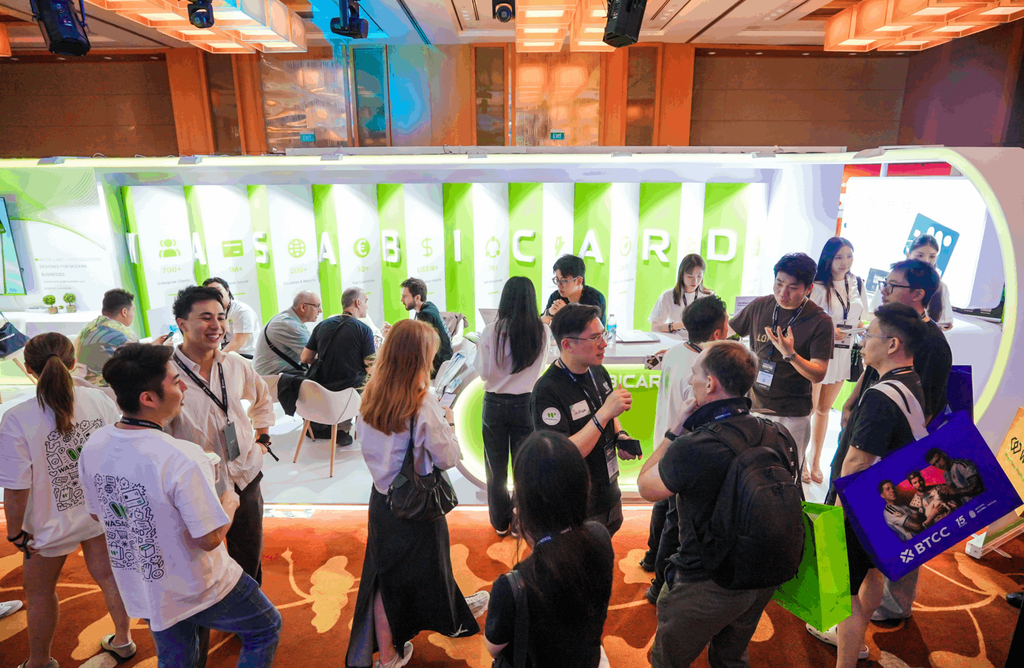
A major milestone for WasabiCard recently was closing a nearly $10 million Pre-A round this June, backed by institutions such as Vernal Capital, Avenir Group, Vision Plus Capital, and 01VC.
In my view, the core reason institutions chose WasabiCard is twofold: it reflects the market's optimism about the prospects of the 「stablecoin-powered enterprise-grade global payment infrastructure」 sector, and it demonstrates recognition of WasabiCard's unique business model value.
Against the backdrop of globalization, payment demands are diversifying while friction becomes increasingly hard to ignore. As a stablecoin-driven global payment infrastructure platform, WasabiCard aims to provide enterprise-grade payment capabilities to global enterprises, FinTech firms, and digital commerce platforms.
WasabiCard's core product capabilities cover cross-border payment functions such as global card issuance and international fund distribution. Based on this, we build scenario-specific payment solutions tailored to different enterprise needs, with Global Payroll being one of the primary applications.
It's often said that 「investing is ultimately investing in people.」 The WasabiCard founding team brings over 10 years of experience in card issuance, card schemes, and crypto payments, with deep expertise in global payment infrastructure, card issuance systems, and digital payments. The team not only possesses a profound understanding of traditional Web2 corporate financial workflows, ERP integrations, and risk management requirements, but also boasts extensive hands-on experience in blockchain on-chain clearing, liquidity routing, and smart contract technology. This hybrid background is a key reason institutions trust us.
Currently, WasabiCard services span over 200 countries and regions worldwide, serve 700+ enterprise clients, have issued over 700,000 cards cumulatively, and processed cumulative transaction volumes exceeding $1 billion. Our clients primarily come from Web3, payment service providers (PSPs), fintech, influencer MCNs, ad tech, OTA, and AI sectors. These companies typically require global operations, cross-border fund transfers, and multi-scenario payment capabilities.
TechFlow: You mentioned earlier the payment changes driven by globalization trends. In your view, where do these changes mainly manifest? How are they shaping the development of next-generation payment infrastructure?
Ray Yang:
A very clear change is that enterprises are accelerating their shift from localized operations to globally distributed operations.
In the past, most companies were more like 「companies within a country」: employees, suppliers, and partners all operated in a single nation, settling in one currency. The traditional payment system served this model for over a century.
But over the past few years, this model is shifting. Post-pandemic, with the rise of remote work and digital nomads, an increasing number of companies now have employees, suppliers, and partners spread across different countries. Meanwhile, AI advancements are further streamlining organizations, giving rise to more small-scale global teams.
Corporate organizations are becoming leaner and more decentralized, yet capital flows are paradoxically growing more complex.
This directly drives changes in corporate payment demand: evolving from relatively fixed, low-frequency, localized payments to higher-frequency, multi-currency, cross-border, and near-real-time fund distributions.
As these distributed micro-organizations multiply, the traditional cross-border payment system—originally designed around interbank fund transfers—begins to falter. When a company must distribute funds to dozens of countries daily, the friction originally hidden within the system gets continuously amplified:
On one hand, companies must address efficiency issues caused by lengthy cross-border transfer chains. On the other, they need to manage multi-currency operations, exchange rate conversions, intermediary fees, and cost disparities stemming from varying regional financial infrastructures.
Evidently, the traditional system can no longer meet modern enterprises' needs. For today's companies, next-generation payment infrastructure is no longer just a payment channel, but a comprehensive framework designed to scale alongside global business operations. It must be more flexible, highly scalable, and inherently global, capable of efficiently connecting the entire workflow from fund distribution and settlement to subsequent usage.
Enterprise Payment Infrastructure, Payroll Emerges as the Core Use Case
TechFlow: Based on WasabiCard's experience serving 700+ global enterprise clients, if we zoom in on specific business scenarios, where is the payment friction most concentrated for globalized businesses?
Ray Yang:
Payroll is one of the most typical and easily understood scenarios, and it's also among the highest-frequency use cases for enterprises.
In the past, 「difficulties in payroll」 were largely concentrated in the Web3 industry. As a classic example of global distributed work, Web3 company team members are often scattered across different countries and regions, facing several highly specific challenges during the entire payroll process:
First is coverage limitations: Not every country where an employee resides can seamlessly receive cross-border payments through traditional banking systems. For some digital asset professionals, traditional financial services may also face certain restrictions.
Second is efficiency bottlenecks: Cross-border bank transfers often involve multiple intermediary steps, and settlement times are rarely fully within a company's control, making it difficult to meet the rapid and flexible payroll settlement needs of global teams.
Third is multi-currency management: A company might price and pay in USD, but employees actually need their local currency. Companies must handle foreign exchange, exchange rates, and regional fund management, which generates extra costs and operational complexity.
Fourth is insufficient capital utilization efficiency: Frequently, receiving funds does not equate to usable funds. After money arrives, employees often still need to withdraw or convert currencies before they can actually spend their salary.
For Web3 companies, payroll isn't just about 「sending money out」; more importantly, it's about enabling global employees to quickly, securely, and flexibly receive and utilize their income. Therefore, businesses need a new type of payment infrastructure that connects stablecoin liquidity, global payment networks, and local financial systems.
In recent years, driven by globalization trends, 「payroll difficulties」 have spilled over from Web3 into multiple sectors: including AI, SaaS, gaming, digital entertainment, cross-border businesses, as well as MCNs and the creator economy. These industries are also heavily adopting remote teams, contractors, and global collaboration models, which is precisely why Global Payroll is a cornerstone use case for WasabiCard.
TechFlow: Regarding Global Payroll as a core scenario, how does WasabiCard position itself within the ecosystem?
Ray Yang:
Before discussing positioning, we need to clarify one thing: corporate payroll actually consists of several layers.
Typically, HR SaaS focuses on employee data management, attendance, performance reviews, onboarding/offboarding, etc.; traditional Global Payroll platforms handle payroll calculations, tax/social security filings, etc.; and Employer of Record (EOR) platforms manage employment contracts and local labor law compliance.
These are crucial front-end components of the payroll process, answering key questions like who should be paid, how much, and why the amount is calculated that way.
WasabiCard focuses on a different question: once the numbers are clear, how exactly does the money cross different countries and payment systems to actually reach employees, contractors, or other payees.
Therefore, regarding WasabiCard's role within the broader Global Payroll ecosystem, I prefer to frame it as the payment execution layer, or the 「last mile」 of global fund distribution:
Sending funds compliantly to employees and partners across various countries at the lowest possible cost and near real-time speed.
From this perspective, WasabiCard's Global Payroll capabilities form a highly complementary relationship with traditional HR SaaS, Global Payroll platforms, or EOR providers: if you are also struggling with the heavy friction of cross-border payment settlements, you are highly likely a potential partner for WasabiCard.
TechFlow: Specifically, within the Global Payroll scenario, how does WasabiCard help enterprises quickly adapt to new global working models?
Ray Yang:
WasabiCard doesn't merely add a 「payroll button」; instead, it provides a complete suite of financial infrastructure designed to tightly link fund distribution, settlement, and usage. This helps enterprises achieve bulk fund distribution, multi-region payments, and more flexible capital utilization.
This infrastructure specifically includes:
- Card Issuing: Supports both virtual and physical card versions;
- Remittance / Global Payout: Enables instant global transfers, settlements, payroll, and commission payouts between stablecoins and fiat currencies;
- Stablecoin Payments & Multi-Chain Infrastructure: The platform integrates with multiple blockchains including Avalanche, Arbitrum, BNB Chain, and TRON, and is part of the Circle Alliance.
Taking payroll as an example:
On one hand, the disbursement workflows of HR SaaS or payroll platforms can integrate seamlessly with WasabiCard, with our system handling low-cost, near-real-time fund distribution worldwide. Throughout the process, companies don't need to build multinational banking relationships or stablecoin clearing capabilities themselves to rapidly connect to the global payment network;
on the other hand, WasabiCard offers corporate-facing card issuance capabilities supporting B2B bulk creation, allowing companies to issue cards in bulk for employees and opt to route salaries directly into issued virtual or physical payroll cards. Employees can bind these cards to Apple Pay or Google Pay for spending, withdraw cash via ATMs, or simply hold the stablecoins;
Additionally, because we also offer global remittance services, corporate employees can use their WasabiCard dashboards to settle received stablecoin salaries into local fiat currencies, instantly transferring them to personal bank accounts with real-time settlement—a highly convenient feature. Our system provides both enterprises and employees with diverse and flexible options for global payroll disbursement and consumption.
TechFlow: Many payment solutions treat 「fund arrival」 as the finish line, but how those funds are used afterward is equally important. By integrating Global Payroll, Global Payouts, and Card Issuing, what problems does WasabiCard solve that traditional B2B payout platforms cannot?
Ray Yang:
Traditional B2B payout platforms typically consider a transaction complete once funds successfully hit the recipient's account. But for Global Payroll, this endpoint is actually too early: after employees receive their salaries, questions surrounding currency conversion, spending mechanisms, and withdrawal processes remain blind spots.
WasabiCard places Global Payroll, Global Payout, and Card Issuing on a single connected chain and integrates them to deliver a complete payment loop:
For enterprises, payroll disbursement and card issuance happen within the same infrastructure. Funds move from corporate accounts to employee spending without passing through any third parties, further boosting capital utilization efficiency and streamlining the payment workflow;
And for employees, upon receipt, they can spend or withdraw cash directly using virtual or physical cards, or continue managing their funds.
WasabiCard extends payment infrastructure beyond mere fund disbursement to seamlessly link fund distribution with consumer spending scenarios, constructing a more comprehensive enterprise payment loop.
TechFlow: Beyond the payment loop, compared to other Global Payroll solutions, what do you believe is WasabiCard's core appeal that attracts enterprises to choose it?
Ray Yang:
I believe WasabiCard holds a distinct advantage in its integration approach.
In my view, what enterprises need in the future is embedded payment capabilities rather than standalone payment tools. The reason is that for a global company, the real headache usually isn't about lacking a specific feature, but rather how that feature can seamlessly and efficiently integrate with the entire existing system.
Based on this insight, WasabiCard has fully modularized its platform capabilities, covering the entire workflow from account setup, KYC, card issuance, top-ups, transactions, risk management, to settlement. With just a simple API integration, enterprises can rapidly unlock these capabilities.
WasabiCard handles these backend processes for companies, significantly reducing development and operational costs: businesses can offer global payment capabilities within their own products without needing to build complex payment systems.
In other words, we aim to transform Global Payroll from a capability that enterprises must build and maintain themselves into directly callable public infrastructure.
From Cost to Efficiency: Why Stablecoins Are Key to Enterprise Payments
TechFlow: Based on your introduction, WasabiCard views stablecoins as the core driver for 「enterprise-grade payment infrastructure solutions」. In your opinion, why are stablecoins a critical component of next-generation global payment infrastructure?
Ray Yang:
Stablecoins are not merely a novel form of digital asset; they represent a fundamentally new method for global value transmission and settlement.
In the past, moving cross-border funds from one country to another typically relied on both nations' banking systems plus intervening financial institutions. Adding another country meant adding another layer of accounts, payment rules, and compliance friction.
Stablecoins operate on blockchain networks 7×24 hours a day. They are unaffected by banking hours or holidays and genuinely decouple value transmission from specific national banking account systems, transforming it into a digital asset that can circulate freely across global networks.
This yields several highly practical shifts:
First is timing: capital is no longer strictly bound by traditional banking operating hours, enabling 24/7 settlement;
Second is global accessibility: breaking geographic limits of traditional finance, helping enterprises connect more efficiently with worldwide employees, suppliers, and partners;
Third is settlement efficiency: reducing intermediary steps in traditional cross-border payments, accelerating fund arrival times;
Fourth is cost optimization: cutting intermediary fees and fund management expenses during cross-border transfers;
Fifth is flexible multi-currency management: enabling companies to conduct global payments and fund distributions based on a unified digital treasury system;
And finally, a crucial feature—programmability: the ability to integrate with corporate systems, APIs, and smart contracts to automate payments, execute bulk distributions, and streamline complex commercial payment workflows.
For enterprises, the value of stablecoins isn't simply to replace existing payment methods, but rather to provide a more efficient and flexible layer of global settlement infrastructure. As global teams, digital commerce, and AI-driven businesses expand, companies require more real-time, automated, and borderless capital movement. Stablecoins are emerging as a vital bridge connecting the digital economy with traditional financial systems.
TechFlow: If we place stablecoins within WasabiCard's entire enterprise payment infrastructure, how exactly do they enhance fund settlement efficiency? What tangible value does this capability bring to corporate clients?
Ray Yang:
Stablecoins serve as the central medium running throughout WasabiCard's payment infrastructure, dictating how funds are routed, settled, and utilized once received.
For businesses, WasabiCard's stablecoin-core architecture supports bulk payroll disbursements for global employees and contractors across 200+ countries and regions. It reduces traditional cross-border payment intermediaries, accelerates global capital turnover, and enables more real-time, efficient fund settlement.
For employees and payees, once funds are received, they can spend online or offline using WasabiCard virtual or physical cards. The system also supports ATM cash withdrawals, conversion into 30+ major fiat currencies, and direct transfers to same-name bank accounts, offering significantly more flexible capital utilization options.
For us, We aim for WasabiCard to solve more than just the 「how to deliver money」 problem. We strive to further bridge 「fund distribution」 and 「fund usage」, delivering a more complete and flexible payment experience for global teams.
Compliance & Ecosystem Connectivity: The Next Battleground for Payment Infrastructure
TechFlow: For corporate clients, alongside payment efficiency, compliance, security, and risk management are equally critical. How does WasabiCard ensure the reliability of enterprise-grade payment scenarios through its licensing framework, payment security standards, and risk control capabilities?
Ray Yang:
One of the biggest distinctions between enterprise-grade payments and standard payment products is that efficiency alone isn't enough. You must simultaneously answer whether 「this money can flow safely and compliantly」. Efficiency must be weighed equally with trust.
Therefore, from the very beginning of building WasabiCard, we never viewed compliance as an external 「add-on」 to the product. Instead, we treated it as a foundational element that demands strict attention.
Currently, WasabiCard has established a compliance framework including US MSB, US MTL, and Canada MSB licenses, while leveraging security standards like PCI DSS Level 1 to safeguard payment data and transaction environments.
Beyond licenses, the true complexity lies in processing massive daily transactions: Who is paying? Who is receiving? Where is this money coming from? Where is it going? Does the transaction align with underlying business logic?
Therefore, We must also establish corresponding KYB, KYC, KYT, and AML frameworks at both the client and transaction levels, continuously identifying identities and risks associated with corporate clients, individual users, and capital flows.
For WasabiCard, we must simultaneously accelerate global capital mobility while embedding this efficiency within compliance frameworks that enterprises can genuinely trust. Only when both conditions are met can this stablecoin-centric payment infrastructure truly transition from innovation to daily enterprise practice.
TechFlow: Over the next few years, as stablecoins gradually become essential infrastructure for global commercial payments, what fundamental changes do you predict for the payments industry? From WasabiCard's perspective, what position do you hope the project occupies within this evolving landscape?
Ray Yang:
In my view, stablecoins will eventually serve as a critical settlement layer connecting global commerce, financial institutions, and the digital economy.
If stablecoins truly evolve into pivotal infrastructure for global commercial payments, I believe the competitive logic of the payments industry will be fundamentally reconstructed.
For decades, competition in the payments sector revolved entirely around channel dominance: whoever connected to more banks, more card schemes, and more local clearing networks held the leverage;
Stablecoins will upend this dynamic. When value can flow freely across borders and outside centralized institutional constraints, the real test for payment companies will shift from channel wars to building genuinely robust infrastructure and ecosystem connectivity capabilities within this new paradigm:
Whoever empowers enterprises to access the most comprehensive and compliant global payment capabilities through the simplest integration methods will have the opportunity to become the default infrastructure chosen by the majority of businesses.
This presents a structural opportunity for WasabiCard: helping enterprises integrate into this new global settlement system more simply and compliantly, allowing them to leverage efficiency gains from stablecoins without needing to grasp underlying blockchain technologies.
If in the future, enterprises only need a single API call to access global fund distribution, settlement, and card payment capabilities—without needing to rebuild their own cross-border payment architectures—that, I believe, is what next-generation payment infrastructure ought to look like.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 深潮TechFlow