a16z: Perpetual contracts are just the beginning. Any future risk can become a tradable asset.
Author: Robbie Petersen
Compiled by: TechFlow
TechFlow Brief: In this long read, a16z crypto makes a counterintuitive argument: what crypto truly disrupts is not trading efficiency, but the supply side of markets. When token issuance, listing, and market making no longer require approval, any risk can become a tradable asset. For market makers, exchanges, and investors, this means a completely new market space is being unlocked.

For most of financial history, the supply of new markets (rather than demand) has been the bottleneck. Blockchain eliminates this bottleneck. I believe this will unleash a fresh wave of market breakouts.
Markets are mechanisms for transferring risk. Every transaction is essentially two counterparties agreeing to transfer some risk exposure at a given price. Abstractly, risk unfolds along two independent dimensions:
- Underlyings: The foundational risk exposure (e.g., a company's cash flows, a barrel of oil, election outcomes, a borrower's creditworthiness, a GPU hour)
- Instruments: The mechanism for transferring that exposure (e.g., spot, dated forwards, perpetual swaps, options, event contracts)
Nearly all of financial history is a story of slow innovation happening one dimension at a time. Spot grain markets have existed for millennia, yet Chicago only listed grain futures in 1865. Currencies floated in 1971, and currency futures followed in 1972. Stock options existed for centuries as customized dealer contracts before becoming listed markets after the advent of the CBOE and the Black-Scholes model in 1973. ETFs did not exist until 1993.
New risk underlyings are even rarer. Interest rates were not widely traded until 1981. Default risk waited until credit default swaps in 1994. Volatility had to wait for VIX derivatives in 2004. Event outcomes did not become true markets until recently through prediction markets.

Demand for these markets has never been the issue. Farmers wanted to hedge harvests well before the CBOT. Creditors sought to transfer default risk long before CDS. What has always slowed growth was the supply of these markets. Historically, two factors have consistently suppressed supply:
- Listing committees and legal frameworks
- Geographic fragmentation
Blockchain eliminates both simultaneously. It makes issuance permissionless and distribution global. In my view, this is the purest form of a killer use case: blockchain is the first technology that allows market supply to catch up to global latent demand.
The argument holds empirically as well. Almost every category-defining outcome in crypto is a downstream result of this killer use case. From perpetual swaps and decentralized spot exchanges to prediction markets, lending markets, memecoins, NFTs, and tokenized real-world assets, value flows to those who hold permissionless on-chain market issuance rights and/or trading rights.

Each of these categories either creates a brand-new risk underlining in a permissionless manner, or invents an entirely new way to transfer risk.
On the asset side, crypto has programmatically created risk exposures that previously lacked financial representation. Prediction markets trace back to the Iowa Electronic Markets, found product-market fit on-chain, and achieved explosive growth by turning discrete events (an election, a Fed decision, a court ruling) into tradable underlyings. Peer-to-peer lending markets transform individual credit relationships into things with real-time continuous pricing. Pre-IPO markets turn risk exposures previously monopolized by a handful of secondary brokers into something users can trade and hold at scale. Even memecoins and NFTs turn abstract risk underlyings (such as attention flows and cultural relevance) into readable, tradable markets.
Additionally, crypto has likewise created or amplified entirely new mechanisms for transferring these risk underlyings. Automated market makers allow markets to exist before dealers agree to quote prices. Perpetual swaps were first proposed in 1993 but found product-market fit on-chain, compressing dated, fragmented exposures into a single contract balanced by funding rates. Binary contracts turn event outcomes into $1-or-nothing tradable markets. Peer-to-pool lending replaces bilateral loans with shared pools and utilization curves. Bonding curves merge issuance and price discovery together, giving assets a market starting from the very first buyer.
Permissionless issuance also generates significant noise. That is the cost of removing listing filters. The point is not that every new market is good. The point is that the market itself (rather than some committee) becomes the self-selecting mechanism that determines which markets survive.
Perpetual Swaps Prove It
Nothing expresses this thesis more purely than perpetual futures, and nothing provides cleaner evidence than the recent growth in on-chain volume for non-native crypto assets.
Because perpetual swaps are synthetic, listing constraints boil down to two things: a robust oracle, and two traders willing to act as each other’s counterparties. As long as those two conditions are met, a leveraged market can essentially exist for anything. In that sense, perpetual swaps are among the most effective coordination mechanisms ever devised.
By the same logic, Hyperliquid represents our closest approximation to a global financial coordination platform. HIP-3 and HIP-4 allow users to launch their own derivatives, tap into the platform’s global front-end, and earn corresponding yields. Lowering friction in launching markets means more markets, and demand will naturally pick the winners.

The fastest-growing markets in crypto (and increasingly across all of finance) — those issued permissionlessly on-chain and distributed globally — is no coincidence. In July, on-chain RWA perpetual swap volume reached a $1.4 trillion annualized run rate, accounting for half of Hyperliquid’s book. Abstractly, this is simply existing risk underlyings (stocks, oil, meme stocks) encountering a new transfer tool in a permissionless manner. Downstream, this recombinant forces generate explosive volume.
Note also that a brand-new market dominates each quarter. Q4 2025 saw US equities and commodities; H1 2026 was driven by oil, gas, and metals; most recently, semiconductors and meme stocks. This again reflects the core thesis. Supply of new markets is catching up to what the world wants to trade each quarter.

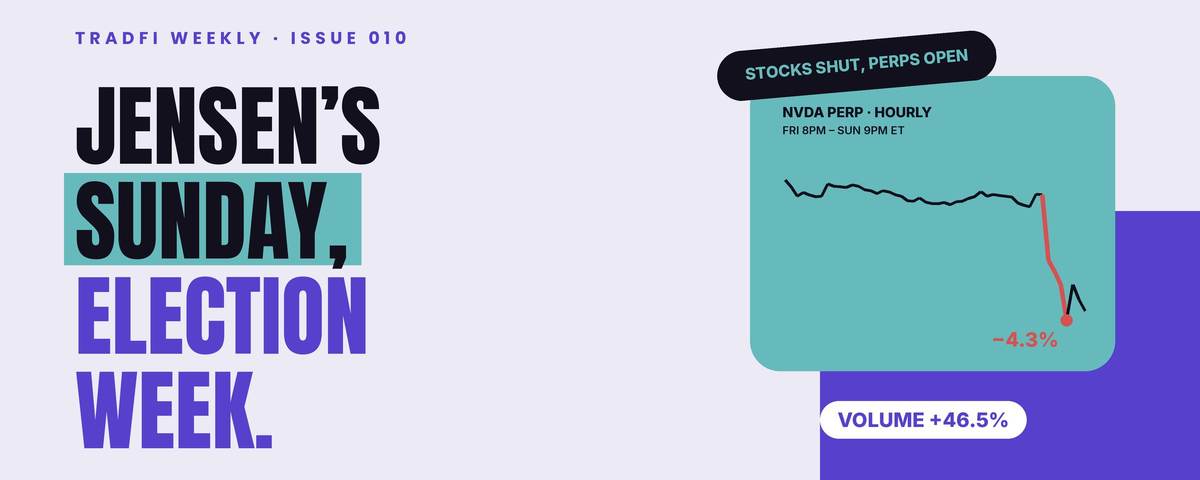
However, a deeper downstream implication is that permissionless, 7x24 trading has become a wedge for on-chain price discovery. During this year’s oil shock, when the CME closed, WTI found price discovery on trade.xyz as one of the most liquid global markets. Similarly, we see pre-IPO equity markets for Cerebras and SpaceX pricing IPOs more accurately than bankers, with minimal marginal differences between the final hour of pre-IPO perpetual trading and actual opening prices.
This dynamic increasingly proves that on-chain markets leverage their freedom from the structural constraints of traditional venues (lack of 7x24 trading, geographic restrictions, pre-listing exclusivity, segregated margin) to establish a sustainable competitive advantage.
Markets transfer risk underlyings. For almost all of financial history, they have been constrained by geography, listing committees, and legal frameworks. These constraints have now vanished. The addressable space for on-chain markets is not a static collection of today’s assets, but any risk that anyone (or any agent) anywhere wants to trade.
This means we will continue to see explosive growth in new on-chain markets. There are novel ways to transfer old risks: commodity and FX perpetual swaps, indices, all-weather equity exposures. There are also entirely new risk units themselves: compute futures, perpetual swaps on macro indicators like CPI, music, social trends, sports, and anything capturable by oracles with both long and short sides. The applications and protocols that issue these markets, along with the venues that trade them, are ultimately the ones that capture value.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 a16z