Wintermute: After ETFs and DATs, RWAs May Take the Lead in the Next Bull Market
Author: Wintermute
Edited by: Jia Huan, ChainCatcher
In the past two weeks, the crypto market has broken out of consolidation, ETF capital flows have turned positive again, and new stablecoin issuances are gradually stabilizing. The question on everyone's mind is: does this signal the start of the next bull market?
Looking back, every market acceleration has been driven by a new liquidity channel. From early token fundraising and stablecoins to ETFs and digital asset treasury (DAT) companies, these channels continuously attract incremental off-market capital into the crypto space, circulating across different assets and ultimately driving a repricing of the entire market.
If a new bull market is brewing, which channel will bring this new incremental capital into the market this time? We believe RWA is one of the most likely candidates.
Every Bull Market Begins with New Capital Inflows
Liquidity drives bull markets, but liquidity also needs an entry point. No matter how abundant global capital is, it won't automatically flow into the crypto market. Only when a sufficiently attractive new channel emerges to bring external funds into this asset class can the crypto market truly benefit from global liquidity expansion.
In the past, when channels like stablecoins, ETFs, and DATs first emerged, they often brought sustained one-way capital inflows that drove market repricing. Over time, however, they gradually transitioned from incremental catalysts into everyday infrastructure, allowing capital to enter and exit just as easily.
Today, ETFs and DATs—the newest channels of the last cycle—have become normalized. The market continues to wait for a fresh capital channel to drive the next bull run.
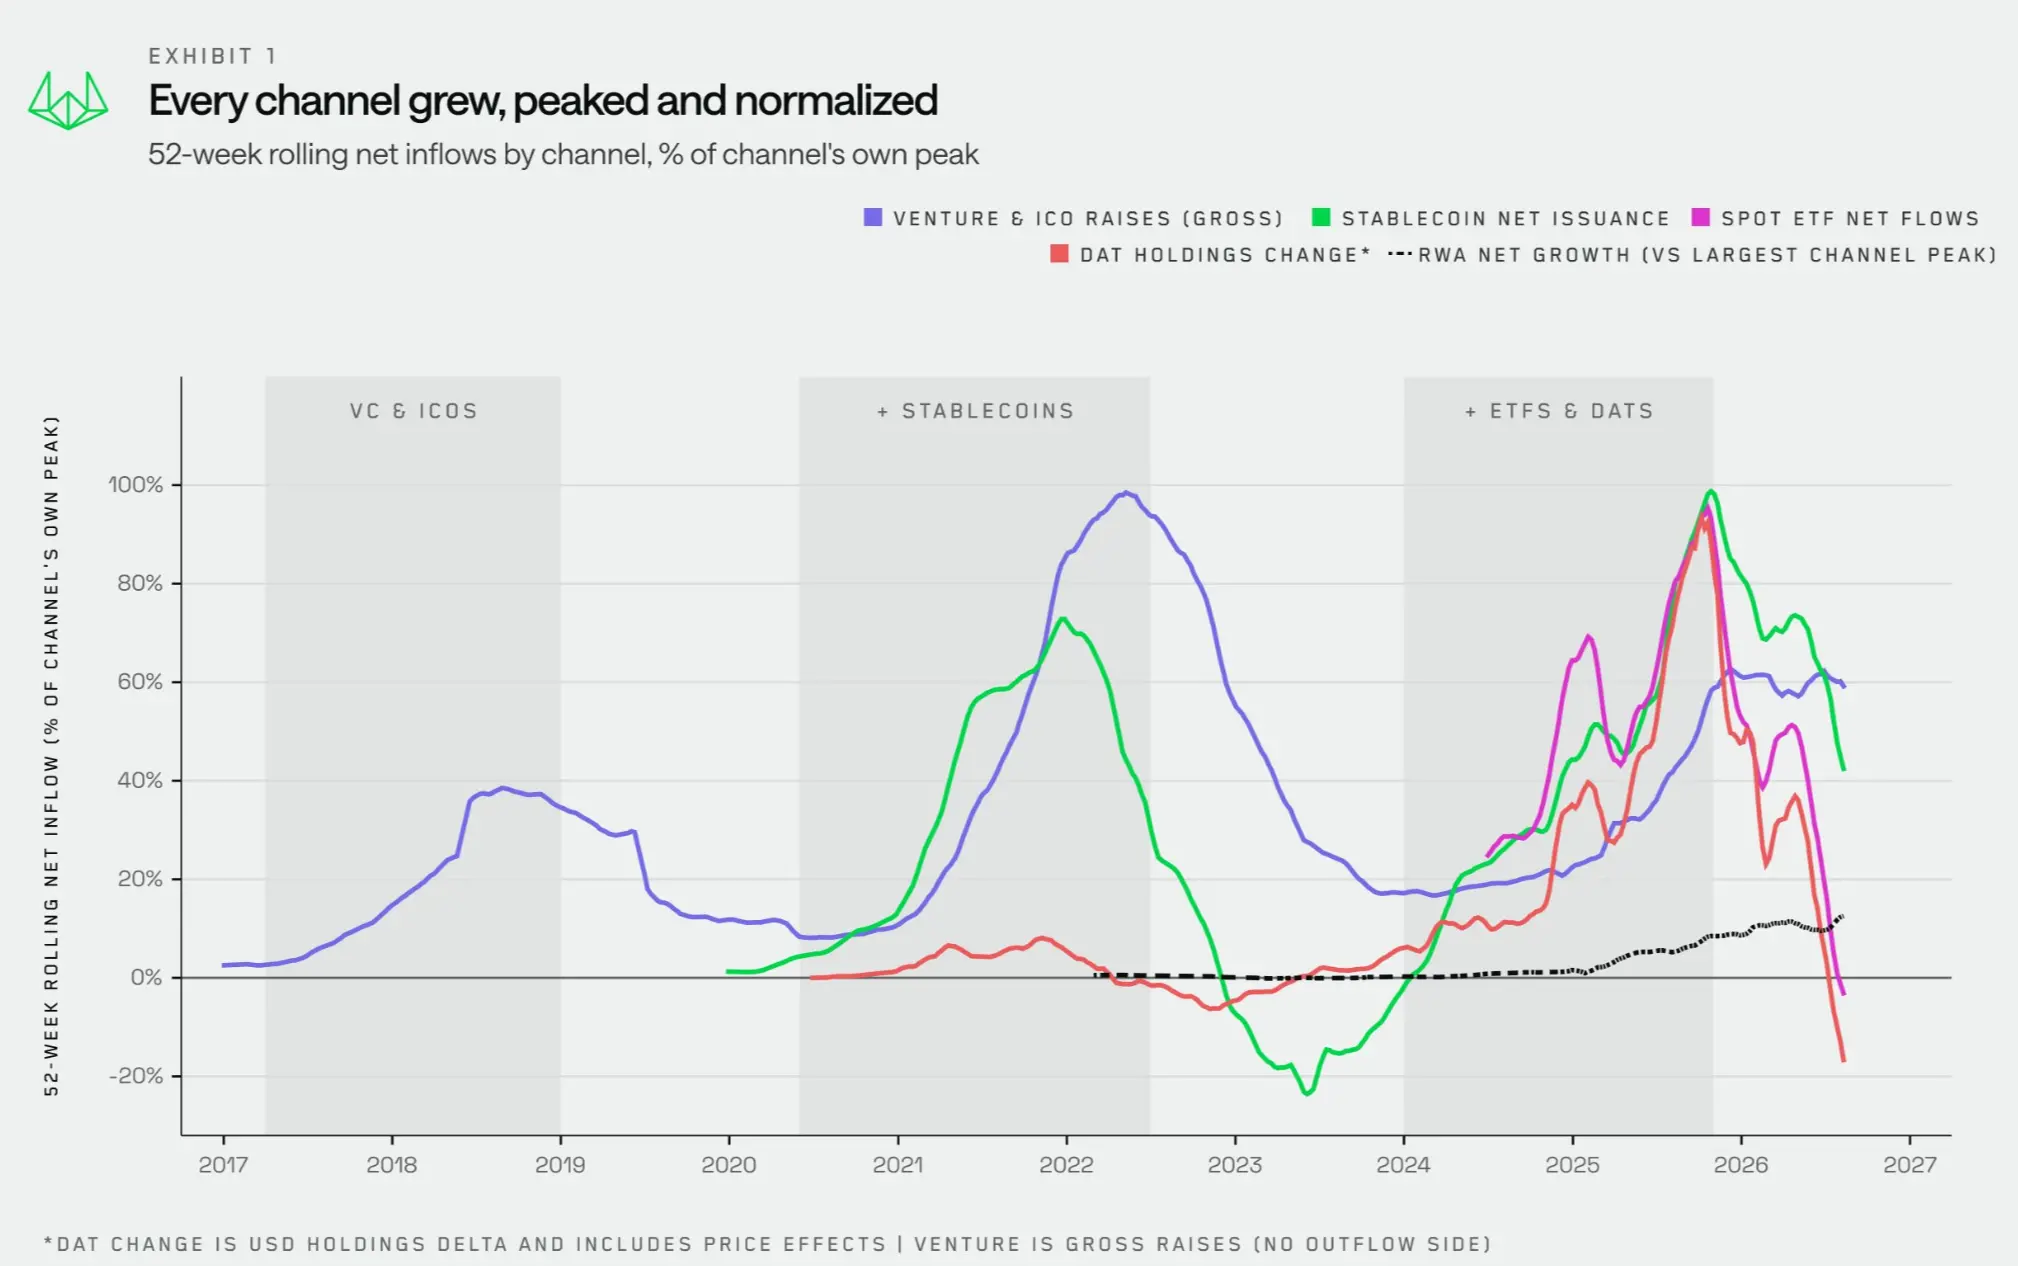
In each bull market cycle, a different capital channel undergoes expansion, peaks, eventually normalizes, and paves the way for the next cycle:
- VC and Early Token Fundraising (2017–2018): Venture capital and token sales brought the first wave of institutional-scale capital into the crypto market.
- Stablecoins (2020–2021): Net issuance exceeded $120 billion in a single year, establishing an on-chain dollar base that funded the DeFi and altcoin cycles.
- ETFs and DATs (2024–2025): ETFs saw $63 billion in net inflows, while digital asset treasuries cumulatively increased their holdings by over $115 billion. This primarily drove the repricing of mainstream crypto assets, with relatively limited spillover effects on other assets.
The dotted line in Chart 1 represents the fifth capital channel currently taking shape. Although RWA's net increase remains small compared to the peaks of previous channels, it is the only one still growing as others begin to retract. Next, we explain why RWA could become the next capital entry point capable of influencing the market cycle.
Old Channels Recede, New Capital Yet to Arrive
Upon entering a bear market, incremental capital typically dries up alongside the decline of the dominant channel. As shown in Chart 2, each cycle sees one channel contribute the majority of incremental capital, causing total inflows to peak in sync with it: reaching 12% of the crypto market cap in 2021, and 10% in 2025.
Once the dominant channel transitions from an incremental catalyst to standard infrastructure, overall capital inflows quickly approach zero. At recent lows, total inflows across all channels accounted for merely 2.4% of the crypto market cap.
ETF capital once flipped to net outflows, and many DAT trading prices fell near or below their net asset value (NAV), making it difficult for them to continue financing further accumulation via valuation premiums. Meanwhile, stablecoin supply experienced its largest contraction since the Terra collapse.
In the past two weeks, these flows have bounced back from their lows, but they remain extremely limited compared to the peaks of previous cycles.
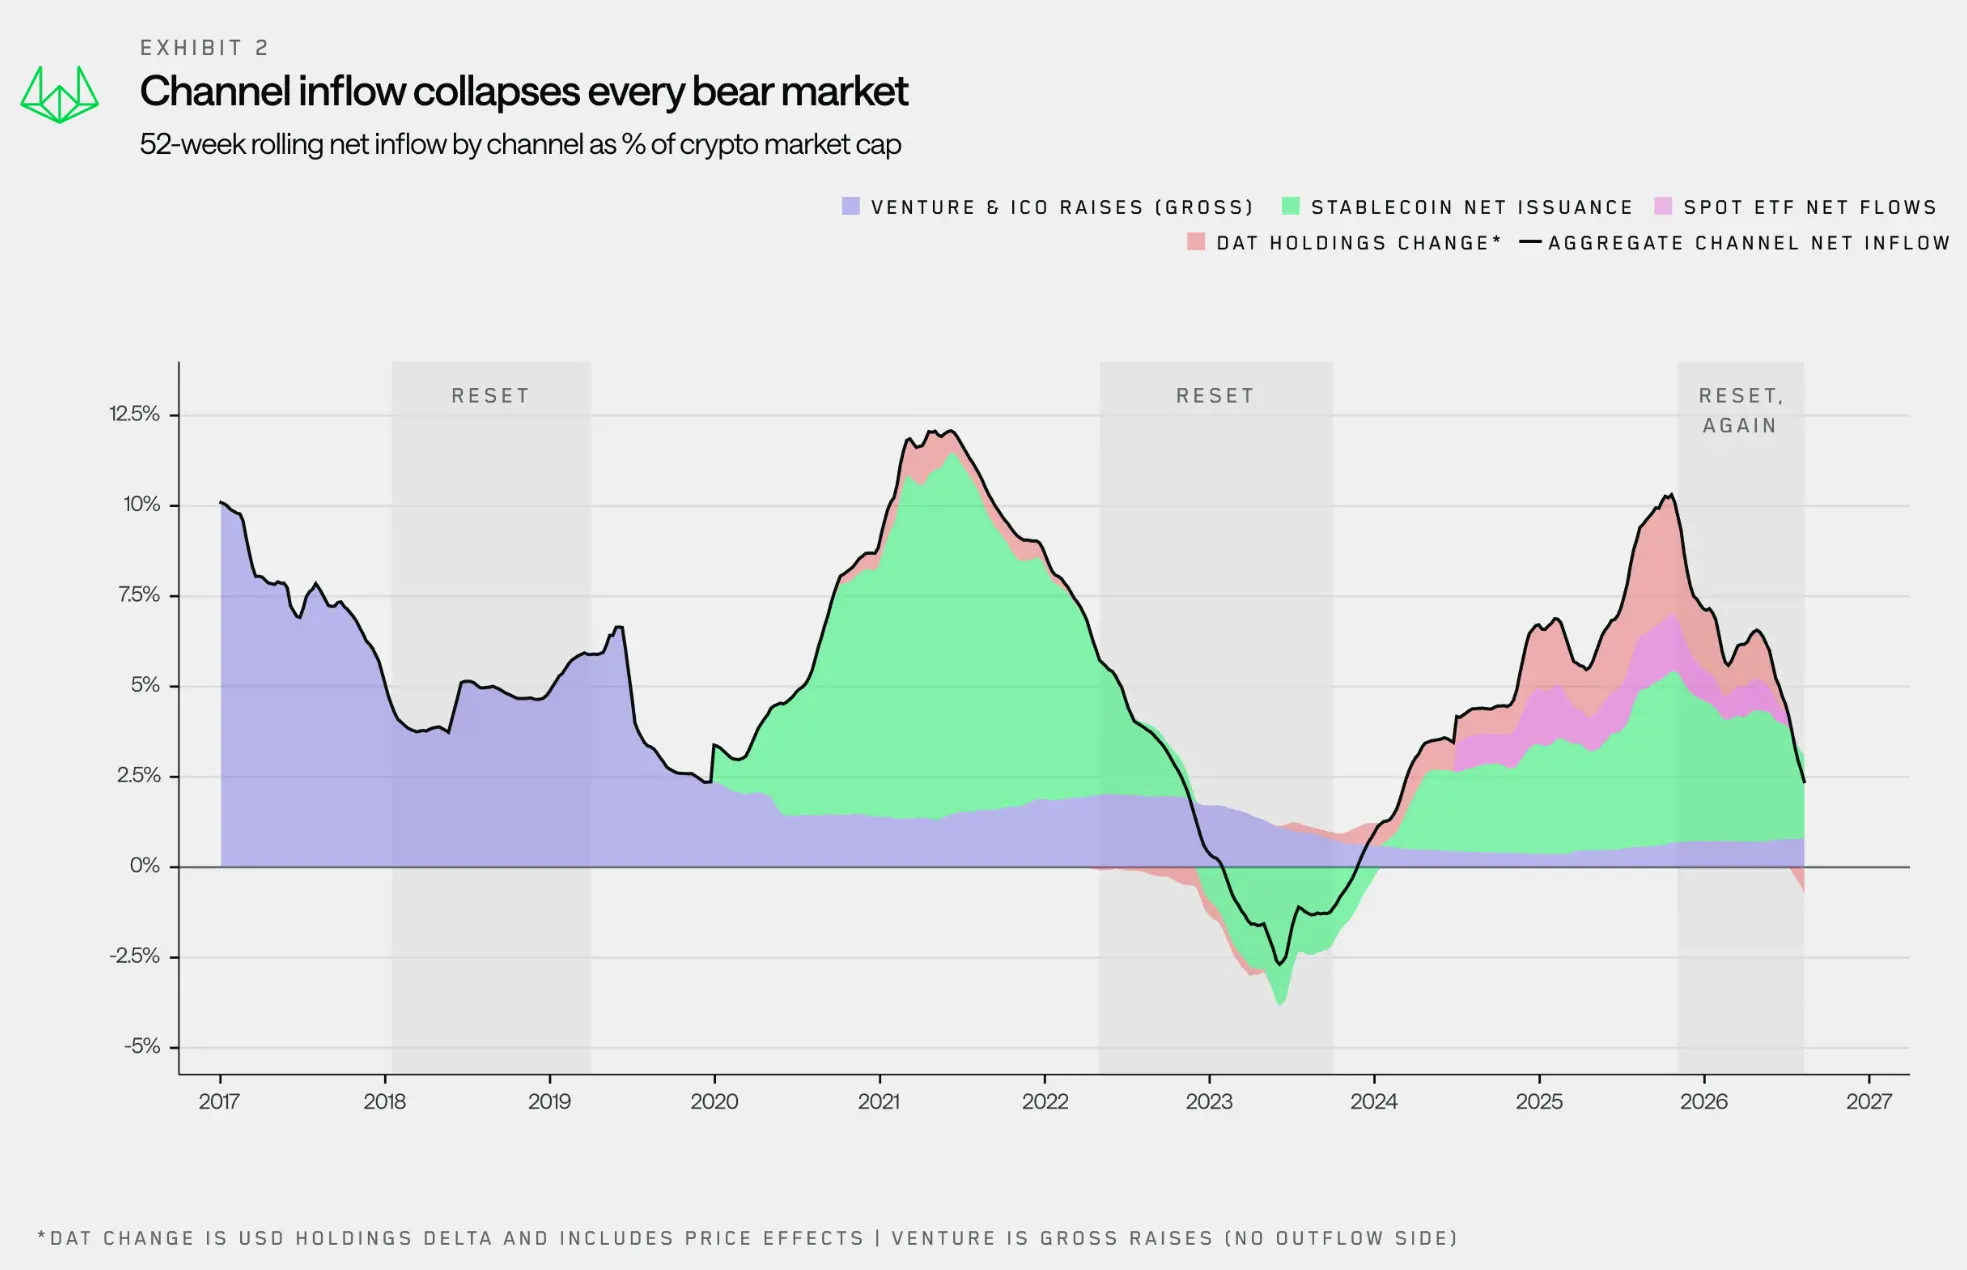
This contraction is not abnormal. Historically, during each cycle reset, as old channels gradually recede, the next channel usually begins to expand. But this time, RWA's scale is still insufficient to take the baton, lagging behind the previous dominant channel by roughly an order of magnitude. Whether it can grow large enough will determine whether the next cycle can truly unfold.
RWA Is Not Just On-Chain Assets, But On-Chain Capital
The market typically understands RWA as "asset tokenization," but we argue it equally means liquidity moving on-chain.
Over the past year, the size of on-chain tokenized assets has roughly tripled to over $30 billion. Even during months when total stablecoin supply contracted, tokenized assets continued to grow steadily. As capital flows more freely between these two asset classes, the barriers to converting between tokenized assets and native crypto assets are constantly lowering.
Today, tokenized stocks, tokenized funds, and crypto assets are increasingly stored in the same wallets and trade and settle using the same stablecoins.
This enhanced ability for asset conversion means tokenization is no longer just a migration of traditional assets on-chain; it also functions as a potential liquidity channel. We believe it could become a key entry point for delivering incremental capital in the next cycle.
Different Entry Mechanisms
The biggest difference between RWA and previous channels lies in how capital enters the market.
Previously, each channel brought buyers to specific asset categories. VC and early token fundraising purchased new tokens, stablecoin capital flowed into DeFi and altcoin markets, while ETFs and DATs primarily bought mainstream coins and blue-chip alts.
Tokenization operates differently. This capital initially purchases Apple stock or U.S. Treasury funds, not crypto assets. However, once funds enter the on-chain ecosystem, shifting them toward BTC or altcoins becomes considerably easier.
Past channels pushed capital directly toward specific assets, whereas tokenization first brings incremental funds into the on-chain ecosystem, after which the capital decides where to deploy itself.
Therefore, RWA's short-term impact won't be as immediate as the capital inflows seen on the first day of ETF launches. Over time, however, this on-ramped institutional capital may gradually allocate across the broader crypto ecosystem. Meanwhile, as infrastructure connecting traditional assets to crypto protocols matures, the costs of capital conversion and allocation will continue to fall.
Why Capital Hasn't Spilled Over Yet
Over the past 12 months, RWA has attracted approximately $16 billion in capital, roughly one-tenth of the combined inflow peak for ETFs and DATs during the best 12-month period of the last cycle. This channel remains in its early expansion phase.
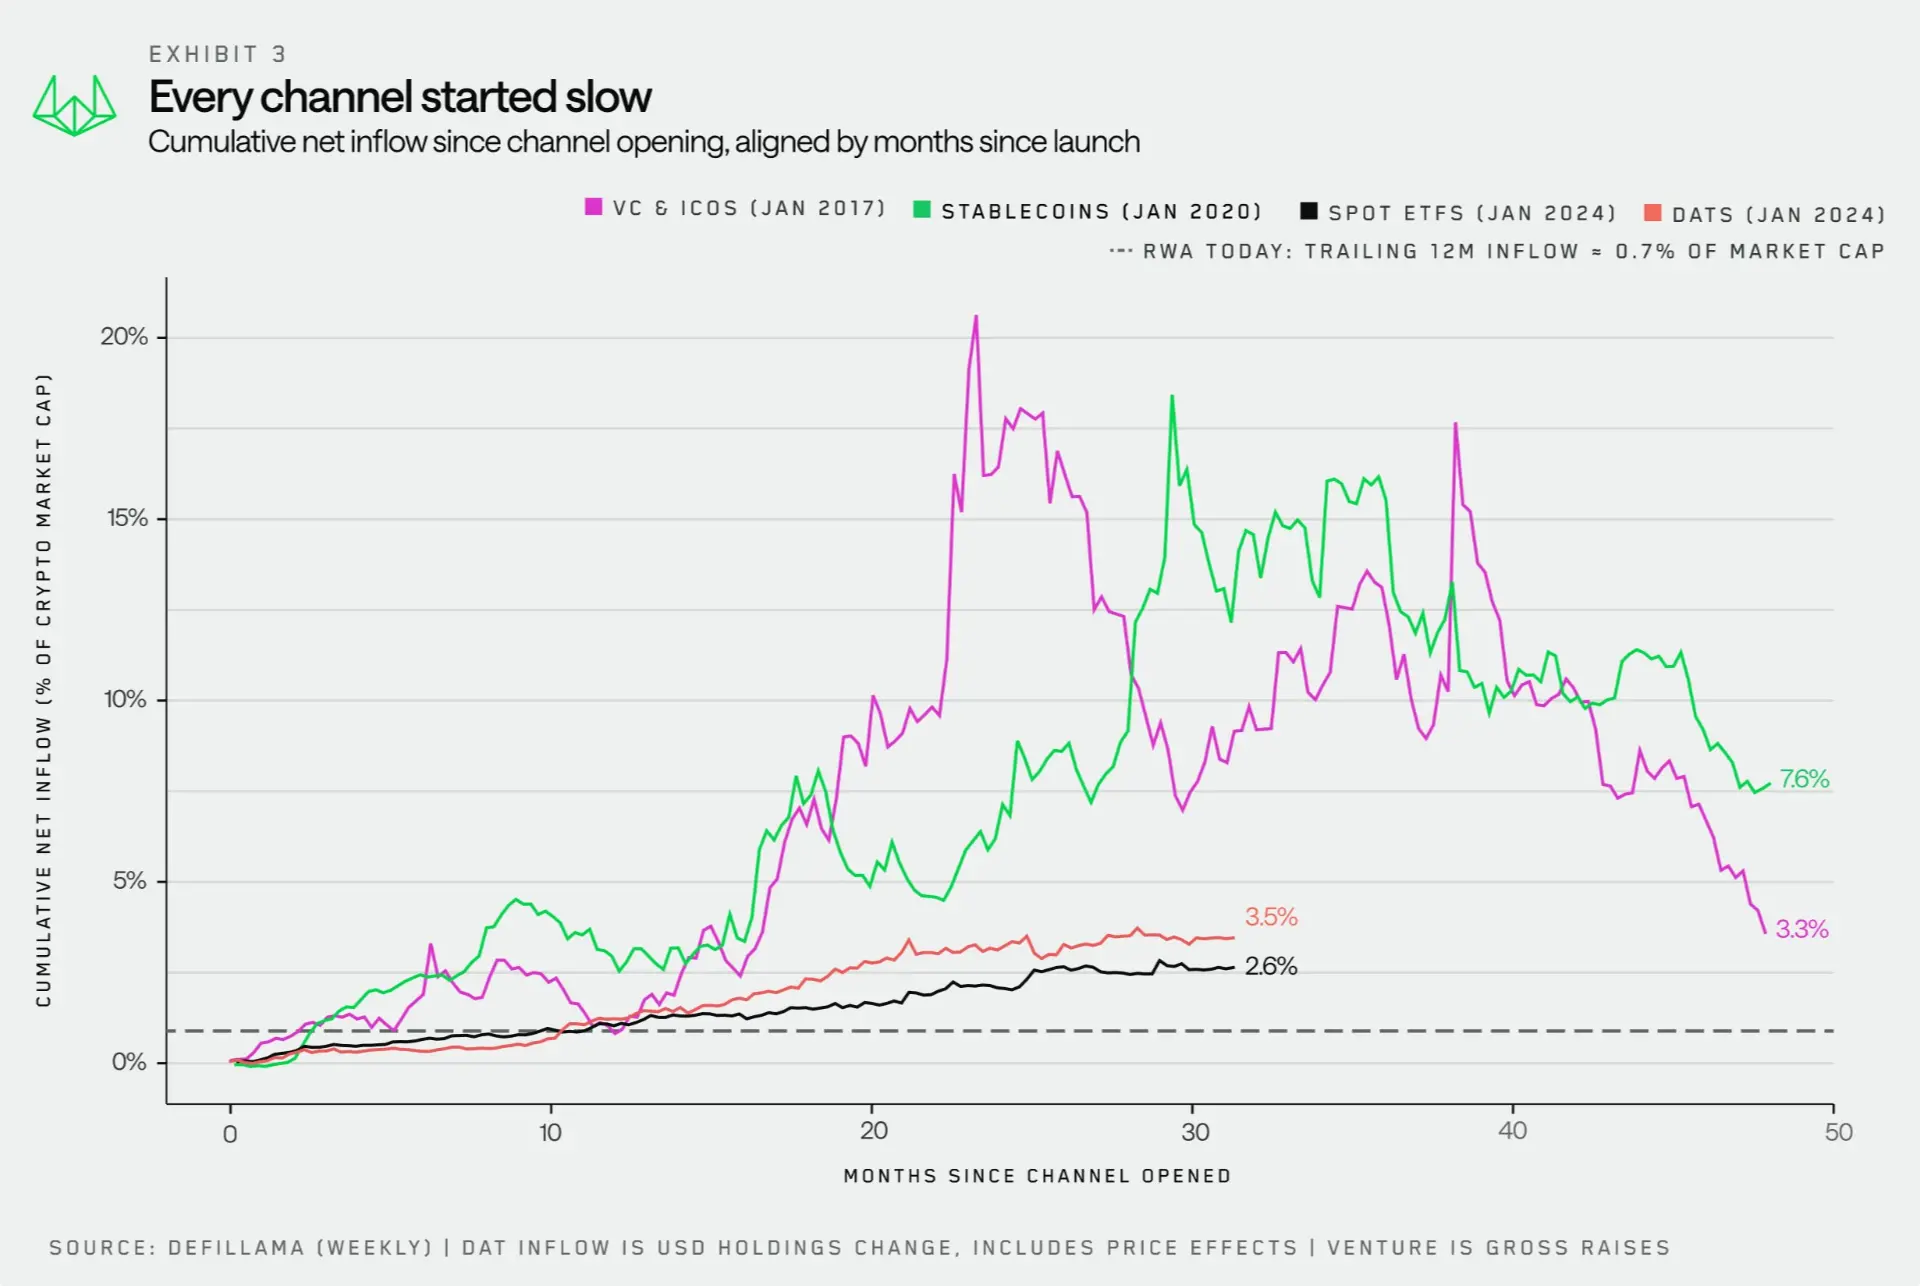
As shown in Chart 3, if counting from the moment each channel first reached observable scale, its capital inflow peak typically occurs between 20 and 60 months after scaling. ETFs peaked at month 20, stablecoins at month 33, and VC and early token fundraising at month 54.
By this timeline, the RWA channel currently has only an 18-month history, with past 12-month inflows accounting for 0.9% of the total crypto market cap. This performance leads DAT from the same period and trails ETFs only slightly. Being in the early stages does not mean this channel has failed.
Currently, most tokenized assets are cash management products, U.S. Treasuries, and money market funds, confined within closed vehicles with access barriers. Infrastructure linking these assets to other on-chain markets has only recently begun operating in earnest.
The catalysts driving this shift come from both regulation and market infrastructure:
- Regulatory level: Market structure legislation and tokenization frameworks are expanding the pool of eligible holders for tokenized securities and clarifying transfer rules for these assets, pushing them out of closed, permissioned pools.
- Market infrastructure level: Tokenized U.S. Treasuries and funds are increasingly being accepted as collateral by major trading venues and DeFi protocols, transforming previously idle on-chain cash management assets into capital that can be deployed across the entire on-chain ecosystem.
Why This Matters for Portfolio Allocation
From 2024 to 2025, capital entered the market primarily through various structured and wrapped products, ETFs, and DATs, which mainly held mainstream coins and blue-chip alts. Consequently, BTC, ETH, and a select few altcoins underwent repricing.
Aside from minor capital spillovers during memecoin rallies, the vast majority of altcoins received no significant buying pressure; and even that spilled-over capital largely stemmed from wealth effects generated by BTC and SOL's price appreciation.
Investors waiting for a broad altcoin season are essentially waiting for capital that structurally cannot reach those assets. This bull run ultimately passed without triggering widespread market mania. Investors who better understood the destination constraints of ETF and DAT capital were also better positioned to anticipate which assets would attract buying interest.
This time, two questions are critical:
- Where will RWA capital flow once it enters the on-chain ecosystem? Beyond remaining in their original vehicles, will they migrate to other on-chain markets?
- If this capital begins moving, where will the value ultimately settle? Which assets will benefit? Which settlement networks, collateral platforms, and foundational DeFi protocols will capture this activity?
Understanding that tokenized assets are primarily held by institutions rather than short-term traders is crucial. This implies that if the next cycle is RWA-driven, the resulting rally may not be overly frenzied but could sustain longer. At the very least, the structural support RWA brings to the crypto market is more likely to manifest as a steady and enduring characteristic.
In the past two weeks, traditional channels including ETFs and new stablecoin issuance have seen renewed capital inflows. While this can propel market recovery, forming a complete cycle may still require a fresh channel for incremental capital.
Every past bull market was accompanied by the continuous expansion of a new channel. Currently, RWA appears to be the only candidate developing along this trajectory.
As the market enters a new cycle, we will closely monitor whether already on-ramped institutional assets can break out of closed vehicles, be used more extensively as collateral, and flow into DeFi, as well as whether they can generate capital flows beyond basic cash management needs. Only when these changes materialize can RWA validate its potential as the liquidity channel for the next bull market.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @wintermute_t