Unitree's IPO wealth feast is destined for only a few to profit from.
Author: Gu Lingyu, Tencent Technology
In the winter of 2017, because high-speed rail did not allow large-capacity lithium batteries, Wang Xingxing held a robot dog and took a train for over ten hours from Hangzhou to Beijing to pitch to Sequoia China. At that time, his company's account was almost unable to pay wages.
9 years later, Unitree Robotics is about to become the "first humanoid robot stock" in China's A-share market. The latest news is that on August 6, Unitree Robotics announced an issue price of 150.80 yuan/share, online roadshow on the 7th, and online subscription will open on the 10th.
Many people expect its market value to break through 100 billion yuan. Multiple secondary market practitioners expressed the same view to Tencent Technology: although the stock market has fluctuated greatly recently, Unitree's IPO subscription will still be very scarce, "because everyone believes this belongs to an industry supported by policies, and the leader must rise."
According to the prospectus, the company is publicly issuing 40.4464 million new shares this time, accounting for 10% of the total share capital after issuance. On August 6, the final issue price was determined at 150.80 yuan/share, actually raising about 6.1 billion yuan, corresponding to a post-issuance valuation of about 61 billion yuan. The initial online issuance was only 6.471 million shares. Calculated at 500 shares per signature, there are only 12,942 winning numbers available for lottery in the whole market, less than 13,000. This means that for every 10,000 valid subscription allocation numbers, there are only about 2 winning spots.
According to incomplete statistics, in the past two years, more than 300 startup companies have been born in China's embodied intelligence industry. By August this year, at least 5 companies had valuations over 20 billion yuan, and nearly 50 companies were preparing for IPOs on the HK Stock Exchange or A-shares. For these companies, Unitree's stock price will constitute a valuation anchor for A-shares and a valuation reference for HK stocks.
This is a critical moment—however, in this capital feast supported by the concept of embodied intelligence, a fault line is appearing between the wealth creation in the primary market and the reality of the secondary market.
The People Who Made the Most Money from Unitree
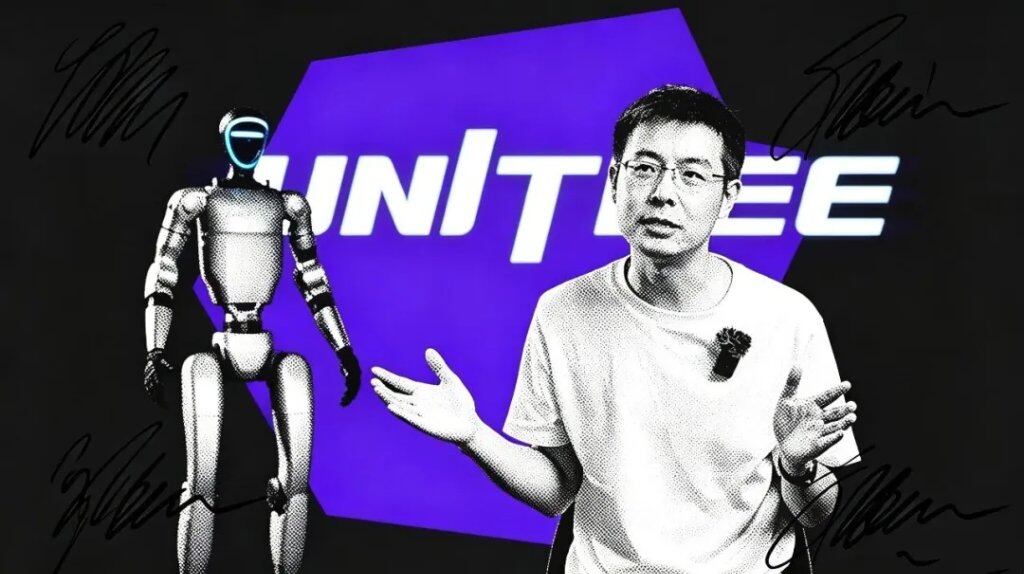
Wang Xingxing does not fit the typical profile of a hard-tech entrepreneur—this became the origin of "contra-consensus" for Unitree's early bettors.
He graduated from Shanghai University with an ordinary resume. During early financing, he encountered setbacks everywhere. In the golden decade of internet model innovation, VC had templates for identifying people: prestigious school background, big tech executives, overseas returnee elites, or serial entrepreneurs. These to some extent guaranteed the lower limit of startup projects, but also screened out entrepreneurs like Wang Xingxing to some extent.
Chuxin Capital Partner Tian Jiangchuan once publicly reflected on this experience. At the end of 2017, Tian Jiangchuan met Wang Xingxing for the first time in a coffee shop in Hangzhou. At that time, Unitree's products had already shown extreme cost-reduction thinking and differentiated technical paths, but Tian Jiangchuan finally gave up investing. "Afterwards I reviewed, the problem mainly lay in my 'arrogance of elitism': Xingxing graduated from Shanghai University, and I thought the robot industry needed a top school background." Tian Jiangchuan later admitted. It was not until 2020 that Chuxin Capital chased Unitree back at a price more than 4 times higher.
An investor who has watched the domestic robot sector for more than ten years told Tencent Technology that when Unitree was founded, the quadruped robot sector did not receive much attention domestically, and very few institutions contacted it early on.
Time rewarded the "contra-consensus" players who entered the earliest. In 2016, Yin Fangming, who had worked at MediaTek, Sogou, and Qihoo 360, made an angel investment of 2 million yuan and obtained 15% equity in Unitree Robotics. The post-money valuation corresponding to this investment was only 13.33 million yuan. Nowadays, this investment indirectly holds equity in Unitree Robotics through the shareholding platform Tianjin Junwan Hongyi. Tianjin Junwan Hongyi holds 3.0699% equity in Unitree overall, ranking as the tenth largest shareholder. On a look-through basis, Yin Fangming actually indirectly holds about 0.46% equity in Unitree. If calculated based on the initial issue valuation of 42 billion yuan, the book value of shares indirectly held by Yin Fangming is about 200 million yuan, with an overall return rate of about 100 times. He cashed out 58 million yuan in advance by transferring part of the existing shares in 2025.
In terms of return multiples, the institution that earned the most multiples is Variable Capital. This early-stage fund invested only 2.09 million yuan in Unitree Robotics' angel round in 2018, and the return multiple so far reaches 174.62 times. Plus the exited part, the total return is about 364 million yuan.
Sequoia China's return multiple is also significant. The pitch session Wang Xingxing exchanged for by taking that train made the Sequoia Seed Fund issue an investment intention letter immediately. This investment of 15 million yuan corresponded to a post-money valuation of only 150 million yuan. After multiple rounds of additional investment, Sequoia China cumulatively invested about 102 million yuan and currently holds a combined 7.11% shares. Calculated based on the issue valuation of 42 billion, its corresponding book market value is about 2.98 billion yuan, with an absolute amount exceeding 2.5 billion yuan.
Meituan is the institution that earned the most in absolute amount. Through entities such as Hanhai Information and Chengdu Longzhu, Meituan holds a combined 9.65% shares in Unitree Robotics, becoming the largest external institutional shareholder. Calculated based on the issue valuation, the market value corresponding to Meituan's shareholding is about 4.05 billion yuan. Considering its cumulative investment of about 400 million yuan in rounds such as the 2024 B2 round, Meituan's book return exceeds 3.6 billion yuan.
Meituan Longzhu Partner Wang Xinyu met Wang Xingxing in the first week of formal work in 2016, but did not invest in him until 2024. At the end of 2023, Wang Xinyu went to the United States to research robot laboratories at top universities such as Harvard, MIT, and Stanford, and found that these institutions representing the world's most cutting-edge research forces were all using Unitree's robot dogs for secondary development. "If the best PhD students in the world are using Unitree's robots for the most cutting-edge research, won't its AI capabilities be solved?" Wang Xinyu once said in a media interview.
Other investors who entered early or mid-stage also benefited richly. Matrix Partners China entered around the 2022 Series B valuation of about 1.12 billion yuan, currently holds a combined 5.45% shares, corresponding to a market value of about 2.29 billion yuan, with a book return multiple of about 45 times; Shunwei Capital first entered in January 2021 at a valuation of 380 million yuan, currently holds 3.98% shares, corresponding to a market value of about 1.67 billion yuan, with a book return multiple of about 26 times; the CITIC group entered in the 2024 B2 round, currently holds 4.49% shares, corresponding to a market value of about 1.88 billion yuan; the SCGC group cumulatively invested about 90 million yuan, currently holds about 2.55% shares, corresponding to a market value of about 1.07 billion yuan, with book returns all around 10 times. Shanghai Yuyi, as an employee shareholding platform, holds 10.94% equity, corresponding to a market value of about 4.59 billion yuan, among which 14 core employees hold about 5.92 million shares, with an average per capita book market value of nearly 48.9 million yuan.
In June 2025, Unitree Robotics confirmed the completion of Series C financing closing, led by funds under China Mobile, Tencent, Jinqiu, Alibaba, Ant, and Geely Capital, with the post-money valuation reaching 12.7 billion yuan. Calculated based on the 2016 angel round valuation, its valuation surged nearly 1000 times in 9 years. Before the IPO issuance, the combined shareholding ratio of the top ten shareholders reached 71.50%.
For early investors, a valuation of 61 billion is already enough for them to succeed and retire.
The Primary Market Expects Unitree to Surge
For the primary market, Unitree's listing is crucial. Currently, the valuations of several leading unlisted embodied intelligence companies have reached 20 to 30 billion yuan. If there is no "anchor" of Unitree's surge in the secondary market, subsequent high-valuation projects will be affected.
A CEO of a robot company with a valuation over 10 billion told Tencent Technology that just like NIO's stock price continued to fall for a while after listing, causing XPeng's subsequent financing to be hindered, "although each company looks different, investors think you are all robots." They are all expecting the stock price of the company that lists first in the industry to surge.
Multiple robot company management personnel told Tencent Technology that humanoid robots are eager to list, first for primary-secondary linkage fundraising, and second often due to urging from capital parties. "On the surface, these institutions have not yet reached the exit cycle, but as long as one company lists, subsequent companies will face huge pressure from shareholders." A CEO of an embodied intelligence component company currently preparing for listing told Tencent Technology.
Some views compare the current embodied intelligence to new energy in 2021, expecting that more than 80% of companies will be eliminated in the future. Concerns about future uncertainty in the capital market and the actual slow landing speed of the industry constitute universal anxiety in the industry.
Capital is willing to pay an issue P/E ratio of 219.23 times for Unitree—far exceeding the industry average P/E ratio of 38.56 times—betting on a future where humanoid robots can fully replace human labor. But currently, Unitree's profits mainly come from robot dogs. Unitree admitted in the prospectus, "During the reporting period, the company has not yet scaled the application of its self-developed general embodied large model to robot products. If brain technology fails to make important progress, there is uncertainty in the large-scale application of general robots."
In other words, capital pays for its market value with the "brain", but Unitree can currently only make money by selling the "cerebellum".
Unitree is trying to make up for this key lesson. In the proposed fundraising of 6.099 billion yuan, there is a special fund for intelligent robot model research and development projects. This is the necessary path for its leap from a "hardware manufacturer" to an "embodied intelligence full-stack platform", and is also the key to supporting its market value.
No Consensus in Secondary Market, But Actions Are Honest
If there is consensus in the primary market, then the influence of this consensus cannot be called sustainable in the secondary market yet.
In the current A-share environment, funding is relatively tight, and old-brand value stocks and semiconductor sectors have diverted a lot of funds. The "Embodied Intelligence/Physical AI" favorite in the eyes of primary market investors may be just a hardware company facing high valuation pressure in the eyes of some secondary market funds. A public fund person told Tencent Technology that the gap between the two logics is one of the sources of uncertainty Unitree faces after listing.
Unitree's circulating cap on the first day of listing is extremely small, amplifying this emotional gaming. The total public issuance of Unitree Robotics this time is 40.4464 million shares, but the initial issuance volume facing online investors is only 6.4710 million shares, accounting for 16% of the total issuance. The remaining 84% of chips were allocated to institutional investors through strategic placement (8.0893 million shares, accounting for 20%, locked for 12 to 24 months) and offline placement (25.8861 million shares, accounting for 64%). In the total share capital of 404.4643 million shares after issuance, only about 29.77 million shares are tradable on the first day, accounting for about 7.36% of the total share capital. More than 90% of shares are in a locked state on the first day of listing. Under conditions of limited supply, once market sentiment is high, stock price elasticity will be significantly amplified.
The aforementioned public fund person told Tencent Technology that the speculation on the Unitree chain in the secondary market has always shown typical "event-driven, surge and fall" characteristics. He believes that this attention sustainability is very limited, "often where it rises, it returns where it was, cannot be maintained long-term."
Taking the 2026 Spring Festival as an example. Funds gambled in advance before the festival on the expectation of humanoid robots appearing on CCTV Spring Festival Gala, completing a round of speculation. On the night of February 16, New Year's Eve, humanoid robots from companies such as Unitree Robotics appeared on stage. The good news was quickly realized and evolved into funds leaving. On February 20, the first trading day of the Year of the Horse in HK stocks, targets such as Dobot and UBTECH surged significantly and then fell back quickly; only a few trading days later on February 24, the A-share robot concept sector suffered a heavy blow, Wzhou Xinchun had a maximum intraday drop of over 9%, closing down 6.9%, and core component companies such as Leader Harmonious Drive and Wanxiang Qianchao led the sector decline.
The process of Unitree Robotics sprinting for the STAR Market was also extremely volatile. From acceptance on March 20 to registration approval landing on July 2, it took only 104 days, creating the fastest audit record on the STAR Market. On July 2, the CSRC approved Unitree Robotics' IPO registration. The next day, the A-share robot concept exploded across the board, with over 50 stocks hitting the limit up or rising more than 10%. However, just in the first three weeks of July when Unitree's IPO registration became effective and the World Artificial Intelligence Conference was held intensively, the CSI Robot Index fell 12.77% in a single week, and the STAR 50 plummeted 10.5% cumulatively in three days. When expectations were realized in advance, the market lost incremental funds, and capital flight under high crowding led to a tragic stock price plunge.
In the whole of July, A-share market value evaporated over 12 trillion yuan, the Shanghai Composite Index fell cumulatively by 6.4%, the Shenzhen Component Index fell drastically by 16.21%, the ChiNext Index fell drastically by 23%, and the STAR 50 Index fell drastically by 25.90%, creating the largest single-month drop in history. AI concept stocks welcomed the most tragic month, the ChiNext and STAR 50 indices fell 23% and 25.90% respectively, and the semiconductor index fell over 33%.
In other words, Unitree's valuation anchor actually does not depend on Unitree itself.
Multiple analysts focusing on the robot sector pointed out that what can still drive the entire humanoid robot industry is Tesla, the reason being analogy with the electric vehicle industry: truly pure electric vehicles began to walk into people's lives only after Tesla Model 3 scaleization, which triggered changes in domestic cognition of pure electric vehicles, and then the rise of other brands. And even the Tesla chain regarded as a weather vane faces great uncertainty.
Tesla Optimus third generation release expectation is delayed to the first quarter of 2026, with core upgrade points focusing on hand flexibility and body structure. This continuous change at the design level means that the supply chain previously carefully dismantled and repeatedly speculated by the market faces restarting at any time. "From the release of the first generation Optimus to now, except for general contractors like Sanhua and Tuopu, the design material usage, corresponding suppliers, and value amount of every joint have changed several rounds. The design we see today may be completely different from the design when future actual humanoid robots begin to popularize. An analyst said.
Against this background, the aforementioned public fund person believes that the key for the entire humanoid robot sector still depends on whether Tesla can open expectations. "If Tesla cannot open this expectation, Tesla's stock price itself is also falling, also in a slump, industrial progress continues to be lower than expectations, Unitree will also find it difficult to walk out an independent upward trend."
Despite this, he said, not a single person around him watching Unitree's IPO subscription has decreased.