Crypto Winter Yields Resilient Results: HashKey’s Interim Report Shows 21% Revenue Growth and 59% Surge in Institutional Trading Volume
Authored by: Xiaobing
On August 27, HashKey Holdings (3887.HK) released its interim results for the first half of 2026.
In an environment where the global total market capitalization of crypto assets contracted significantly in the first half of the year, this Hong Kong-based largest compliant digital asset exchange delivered a performance report that exceeded market expectations.
Core Data: Total revenue for H1 reached HKD 343 million, up 20.6% year-on-year. Gross profit was HKD 208 million, up 12.5% year-on-year, with gross margin rising sequentially to 60.6%. Adjusted losses narrowed from HKD 398 million in the same period last year to HKD 315 million, a decrease of 21%.
All three core business segments showed simultaneous improvement.
This interim report contains three key signals worth examining closely.
Institutionalization Is Not Just a Slogan
Trade facilitation revenue reached HKD 268 million, up 38.6% year-on-year. In terms of trading volume structure, the platform's total trading volume reached HKD 282.2 billion, up 31.8% year-on-year.Among this, institutional client trading volume hit HKD 231.5 billion, a surging increase of 58.8% year-on-year, accounting for 82% of total trading volume.
A year ago, one of the market's core concerns about HashKey was its reliance on retail users and market cycles ("retail-driven, market-dependent"). This interim report provides a data-backed response:HashKey's revenue growth engine has shifted from retail investors to institutions. Despite a broadly contracting crypto market in H1, institutional trading volume surged instead, indicating that the appeal of compliant infrastructure to institutional capital is accelerating into actual trading activity.
On August 4, Citi initiated coverage of HashKey with a "Buy/High Risk" rating, setting a target price of HKD 5.60, implying a potential upside of 203% relative to the then-stock price of HKD 1.85.
One of the core logics in Citi's research report is:The policy dividends of Hong Kong's onshore compliant market have yet to be fully realized, and as the holder of over 75% market share, HashKey stands to benefit the most.
RWA Tokenization Is Moving from Concept to Revenue
The standout feature of the on-chain services segment lies in its Tokenisation business. The total value of on-chain RWAs reached HKD 268 million, up 167.8% year-on-year. During the period, it launched Hong Kong's first real estate RWA and its first regulated silver RWA token.
A growth rate of 167.8% is highly prominent in the current market environment, indicating that HashKey Chain, as an L2 network designed for RWAs, is transitioning from the "building infrastructure" stage to the "attracting assets on-chain" stage.
The pioneering onboarding of real estate and silver covers the two most core categories of physical asset tokenization: real estate and commodities.
Although this business line currently represents a small portion of revenue, its growth rate is the fastest among the three segments. If the commercialization of tokenization continues to accelerate (especially driven by the HKMA's tokenized bond pilot and the implementation of HKDAP), on-chain services could become HashKey's most critical growth driver within the next two to three quarters.
Global Expansion Map Is Taking Shape
A series of moves during and after the interim reporting period outline HashKey's global roadmap.
In July, it announced the proposed acquisition of 100% equity in Singapore-based Asia Pacific Exchange (APEX). APEX holds dual licenses as a "Recognized Exchange" and "Recognized Clearing House." Upon completion of the acquisition, HashKey will possess complete trading and clearing infrastructure spanning Hong Kong and Singapore. This has no precedent among compliant digital asset companies in Asia.
In April, it strategically invested in Vietnam's CAEX, reaching a technical cooperation agreement to jointly build a local institutional-grade compliant trading platform. In May, through HashKey Capital, it led a USD 40 million Series B+ round investment in SignalPlus, positioning itself in institutional-grade derivatives trading technology. By late July, it completed an app merger, consolidating four regional sites—Hong Kong, Singapore, Dubai, and Bermuda—into a single unified gateway to achieve "multi-site integration."
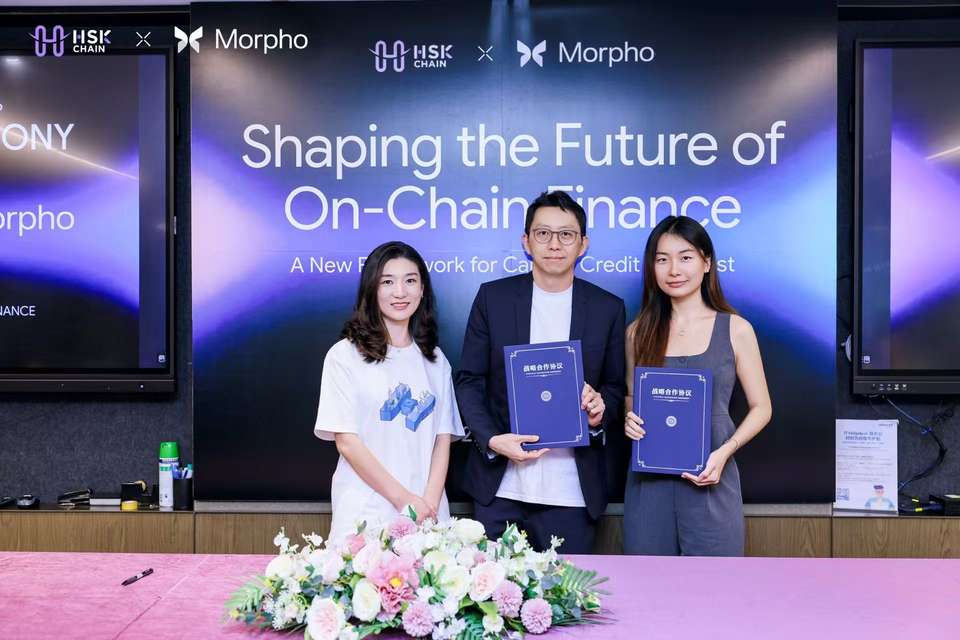
It deepened fiat channel partnerships with JPMorgan Chase and DBS Bank. It collaborated with Canton and Morpho to explore institutional-grade on-chain applications. It initiated the founding of the Ethereum Application Alliance (EAG) and joined the HKMA's tokenized bond expert panel.
Viewing these moves collectively, HashKey is expanding along the path of "Hong Kong single market → Asian multi-market network → global digital financial infrastructure." Founder Xiao Feng clearly articulated the roadmap in the interim report:From a digital asset trading platform to a digital asset financial market, from Crypto Native assets to RWAs and tokenized assets, ultimately forming a new generation of financial infrastructure that connects asset pools and liquidity pools.
How to Interpret This Interim Report?
HashKey remains unprofitable, posting an adjusted net loss of HKD 315 million. Although this represents a 21% year-on-year narrowing, it is still far from the breakeven point. The company's full-year loss for 2025 amounted to approximately HKD 1.087 billion. The stock price has trended downward since its listing debut at HKD 6.67, hitting an annual low of HKD 3.25.
However, viewing these figures from a different perspective may lead to a different conclusion.
HashKey is in its first full six months of operations post-IPO. It faces a macro environment where the broader crypto market is contracting and peer trading volumes are nearly all declining. Against this backdrop, HashKey not only achieved 20.6% revenue growth but also boosted its gross margin sequentially to 60.6%, while institutional trading volume grew by 58.8%.Losses are shrinking, revenues are rising, and the structure is optimizing.
Soochow Securities' forecasting model projects 2025–2027 revenues at HKD 782 million / HKD 1.211 billion / HKD 2.338 billion, corresponding to growth rates of 11% / 55% / 90%. If H1's revenue pace of HKD 343 million can be maintained or improved in H2 (typically the active season for the crypto market), full-year revenue will likely exceed Sochow's HKD 1.211 billion forecast.
For a compliant digital asset infrastructure company that listed eight months ago, is still operating at a loss, yet is seeing counter-cyclical growth in both revenue and trading volume, the question the market needs to assess is not "whether it is profitable right now," but rather "how fast it is progressing down the path to profitability."
The answer provided by this interim report is: Faster than most people expected.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 深潮TechFlow