Analysis of Mining Rig Asset Depreciation and Tax Cost Recovery
Written by: FinTax
For the same ASIC mining machine, this cost may be depreciated over two to three years in the financial statements, while its qualifying tax basis could be fully deducted in the first year on the U.S. federal tax return.
On July 4, 2025, H.R. 1 became Public Law 119-21. Section 70301 amended IRC §168(k), reinstating the 100% additional first-year depreciation deduction (typically referred to as bonus depreciation) for qualifying assets as a permanent rule. In Notice 2026-11, the IRS further clarified that this rule generally applies to qualified assets acquired and placed in service after January 19, 2025.
However, 100% bonus depreciation does not mean that all mining machine costs can be fully deducted in the first year of purchase; actual tax treatment still depends on asset classification, acquisition timing, and the date placed in service.
I. Characteristics of Mining Machine Depreciation
ASIC mining machines used for solo mining that meet the recognition criteria under IAS 16 are typically capitalized by publicly listed mining companies as mining equipment within property, plant, and equipment (PPE) and depreciated over their estimated useful life.
IAS 16 requires the depreciable amount to be allocated systematically over the asset's useful life. When determining useful life, factors such as expected usage pattern, physical wear and tear, technical or commercial obsolescence, and legal or similar restrictions must be considered. The asset's useful life is based on its expected utility to the entity and therefore may be shorter than the economic life of the asset itself; the depreciation method is reviewed at least at each financial year-end and treated as a change in accounting estimate when there is a significant change in the expected pattern of consumption of economic benefits.
However, for mining machines, continued operational functionality does not necessarily equate to economic viability for continued operation. With newer generations of ASICs offering higher hash rates and energy efficiency, older machines require lower electricity rates to maintain marginal returns; increasing network hash rate and mining difficulty also depress expected output per unit of hash rate.
The actual useful life of a mining machine largely depends on the cost at which it can sustainably generate economically viable hash power. A generation of devices may technically operate for five years, but if a company expects that after three years its energy efficiency will no longer support economic operation at its electricity rates, a three-year accounting life may better reflect actual usage patterns. Conversely, if electricity costs are low, maintenance conditions are good, or the model remains competitive over a longer period, the estimated useful life may be extended.
Accounting practices among publicly listed mining companies also reflect a trend toward shortened economic useful lives for mining machines. Bitdeer Technologies Group disclosed in its 2025 Form 20-F that, effective July 2025, the estimated useful life for most mining machines was adjusted to two to three years, down from two to five years previously; Argo Blockchain plc disclosed in its 2025 Form 20-F that mining machines are typically depreciated on a straight-line basis over an estimated useful life of 36 to 48 months.
The depreciation period for mining machines is essentially an accounting estimate made by the enterprise based on the expected economic usage period of the asset, with no fixed lifespan uniformly applicable to all machines. Companies must consider factors such as model and generation, energy efficiency, changes in mining difficulty, equipment replacement plans, and expected residual values to determine the period over which the asset can continuously generate economic benefits. As mining machine iterations accelerate, these estimates become more prone to change, requiring companies to establish sufficient, auditable bases and continuously assess whether the estimated useful life, residual value, and depreciation method remain appropriate.
II. 100% Full Depreciation Under U.S. Federal Tax Law
The core change on the U.S. federal tax side stems from Public Law 119-21. This policy applies to a broad range of qualified depreciable assets and is not limited to crypto mining machines. Qualified assets listed by the IRS include relevant depreciable assets subject to MACRS with a recovery period of 20 years or less, encompassing qualifying new assets and certain used assets. For mining companies, determining whether a mining machine qualifies for 100% full depreciation requires first confirming the asset's tax classification, acquisition and placement-in-service dates, user entity, and other applicable conditions. Merely signing a purchase order or completing payment does not constitute placing an asset in service; the IRS generally requires that the asset has reached the point where it is ready and available for its intended specific use.
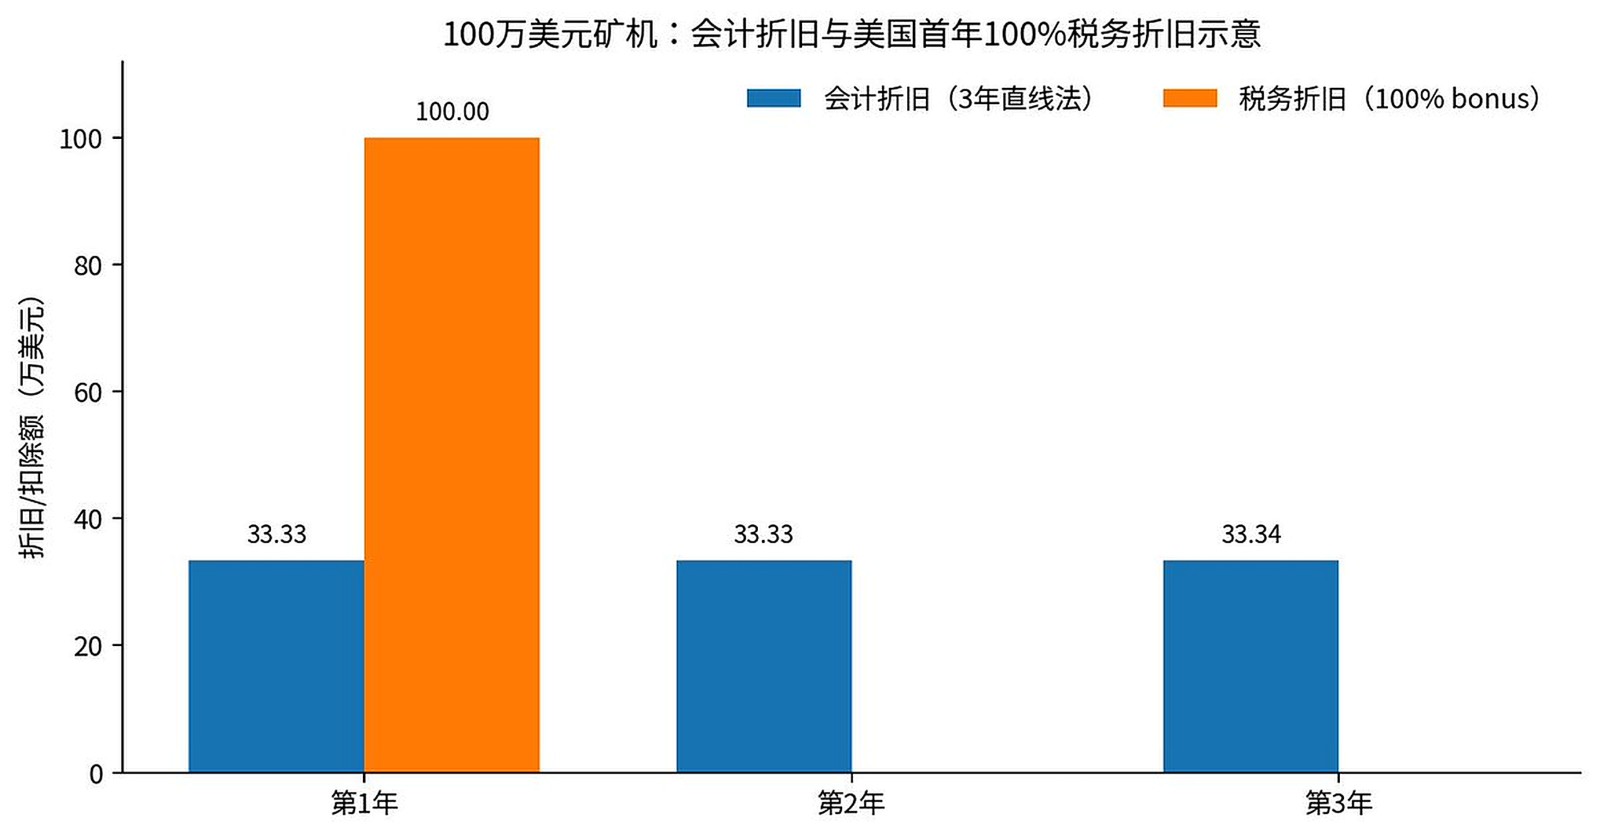
Once a mining machine meets the eligibility criteria, it creates a clear timing advantage for the mining company. Suppose a mining company purchases a $1 million mining machine and depreciates it on a straight-line basis over three years for accounting purposes, recognizing approximately $330,000 in annual depreciation expense. If eligible for 100% full depreciation under U.S. federal tax law, the entire $1 million qualifying tax basis can be deducted in the first year. For companies with high current profits, front-loading deductions can reduce current taxable income and cash tax liabilities.
III. Phased Depreciation May Be More Valuable During Loss Years
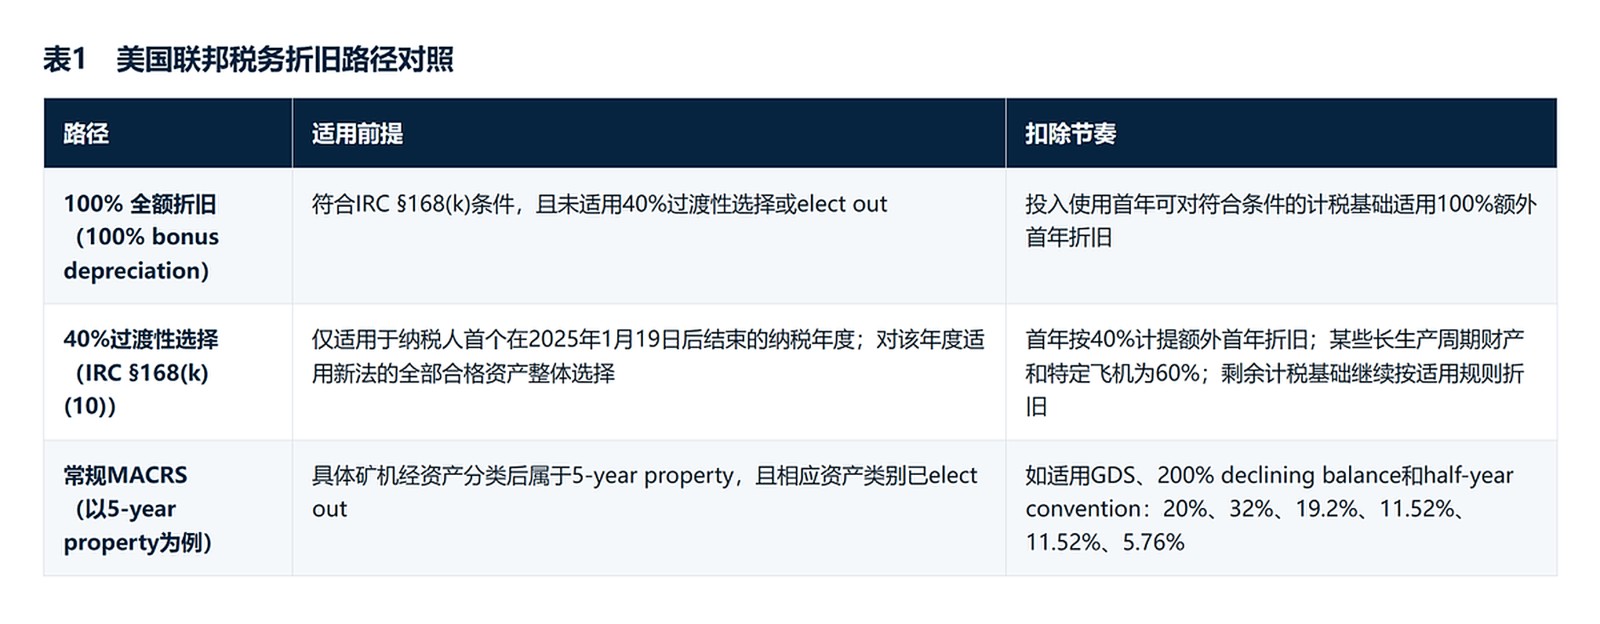
Under IRC §168(k)(7), taxpayers may elect out of the first-year full depreciation for a particular class of assets. This election applies to all qualifying assets in the corresponding class placed in service during the taxable year, not merely to selectively chosen individual units.
Beyond opting in or directly waiving the 100% full depreciation, the new law provides an alternative transitional election. IRC §168(k)(10) stipulates that for the first taxable year beginning after January 19, 2025, taxpayers may elect to claim an additional first-year depreciation deduction of 40% on qualified assets under the new law (a 60% rate applies to certain longer production period property and specific aircraft).
If a company elects out of the 100% full depreciation for a class of assets, it recovers the cost according to standard MACRS rules. Determining whether mining machines fall into the five-year property category requires identifying their specific asset classification. If analysis indicates they qualify as five-year property and use the commonly applied GDS, double-declining balance method, and half-year convention, the standard tables in Publication 946 yield tax rates of 20%, 32%, 19.2%, 11.52%, 11.52%, and 5.76%, spreading actual cost recovery across six taxable years.
Whether a company elects the 100% first-year full depreciation depends on how the timing of depreciation deductions impacts overall tax liability and corporate cash flow. For companies with high current profits, taking depreciation deductions upfront typically reduces taxable income and cash taxes sooner. However, for entities already in a loss position for tax purposes, adding more depreciation may simply widen the Net Operating Loss (NOL) carryforward without producing a simultaneous reduction in cash taxes. For typical C corporations (taxed as separate taxable entities), NOLs generated after 2017 are generally limited to offsetting up to 80% of taxable income in subsequent years; if a change of ownership occurs, the utilization of pre-change NOLs may face further restrictions. Therefore, the decision to apply 100% full depreciation should be comprehensively evaluated by factoring in future profitability, NOL usability, time value of money, asset class elections, and other tax law limitations.
IV. How Tax-Accounting Differences Reflect on the Books
When an asset's carrying amount exceeds its tax basis, a taxable temporary difference arises, typically resulting in the recognition of a deferred tax liability.
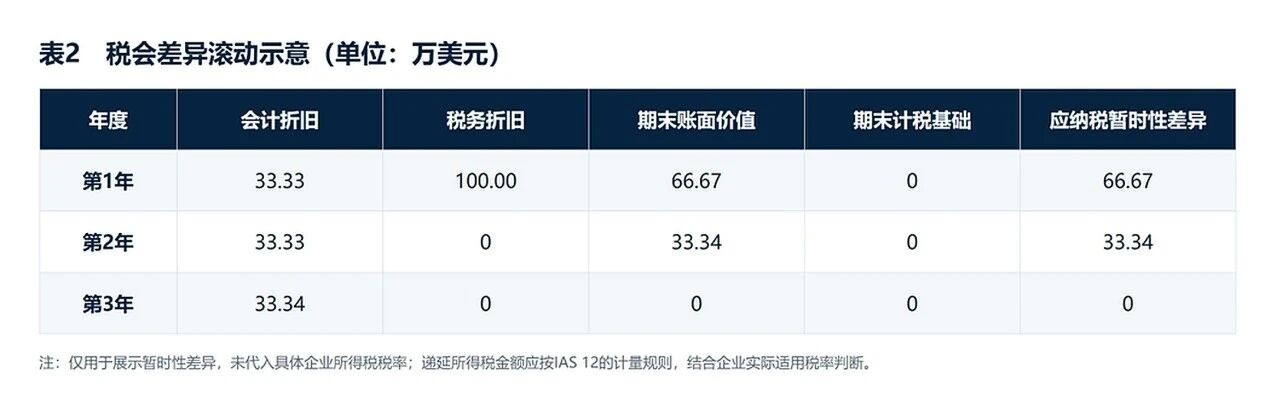
Consider a batch of mining machines costing $1 million with zero residual value, depreciated on a straight-line basis over three years for accounting purposes. At the end of the first year, accounting depreciation amounts to approximately $333,300, leaving a carrying value of $666,700. If the machines qualify for 100% full depreciation under U.S. tax law and the entire $1 million tax basis was deducted in the year placed in service, the tax basis of the machines drops to zero.
At this point, the $666,700 carrying value and the zero tax basis create a $666,700 taxable temporary difference, leading to the recognition of a deferred tax liability. The specific amount of the deferred tax liability is calculated by multiplying the temporary difference by the enacted or substantially enacted income tax rate applicable during the period the difference is expected to reverse.
During the second and third years, accounting depreciation will continue; however, since the tax cost was fully deducted in the first year, no corresponding tax depreciation will be recognized subsequently. As the carrying value of the mining machines declines annually, this taxable temporary difference and the associated deferred tax liability will gradually reverse.
Therefore, the 100% first-year tax depreciation does not shorten the accounting useful life of the mining machine to one year. The financial statements continue to reflect the estimated consumption pattern of economic benefits from the equipment, while tax filings handle cost recovery according to the rhythm permitted by tax law. In practice, the acquisition cost, placement-in-service date, accounting useful life, tax asset class, and amount deducted for the same equipment must align consistently.
V. Regional Differences in Mining Machine Tax Treatment
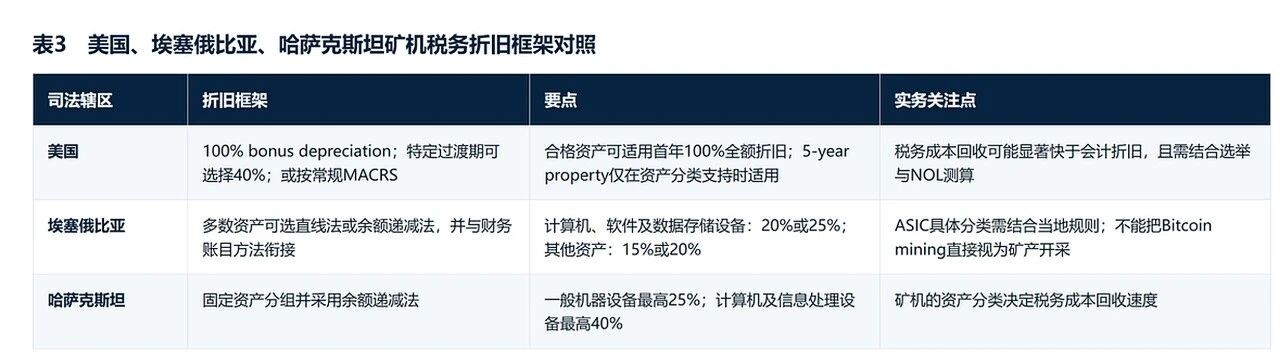
The 100% full depreciation in the U.S. offers mining companies a faster cost recovery speed while retaining the optionality to apply accelerated deductions. In contrast, in Ethiopia and Kazakhstan, mining machines typically must recover costs annually in accordance with local asset classifications and statutory depreciation rules, resulting in relatively limited flexibility in tax treatment.
Ethiopia's Federal Income Tax Proclamation Regulations (Council of Ministers Regulation No. 410/2017) manage depreciation by classification, applying a straight-line rate of 20% or declining balance rate of 25% to computers, software, and data storage equipment. Taking a simplified example, if a company's financial statements depreciate using a straight-line method over three years, and the local tax classification ultimately supports computing equipment depreciated on a straight-line basis, then for a $1 million asset, the first-year accounting depreciation would be approximately $333,300, while tax depreciation would be roughly $200,000. Tax deductions lag behind accounting depreciation, leaving an ending tax basis of approximately $800,000, which is higher than the carrying value of about $666,700, thereby creating a deductible temporary difference. This outcome stands in sharp contrast to the U.S. treatment.
Kazakhstan's new Tax Code (No. 214-VIII) was signed on July 18, 2025, and took effect on January 1, 2026. According to a tax summary updated in July 2026, tax depreciation primarily uses the declining balance method, typically categorizing fixed assets into four groups: general machinery and equipment at a maximum of 25%, and computer and information processing equipment at a maximum of 40%. The speed of tax cost recovery for mining machines will vary accordingly depending on the asset group to which they are assigned.
Conclusion
Handling mining machine depreciation requires first clearly distinguishing between accounting and tax perspectives. From an accounting standpoint, the estimated useful life should be determined based on factors such as equipment generation, energy efficiency, and expected operational cycles. From a tax perspective, using U.S. federal tax law as an example, it must be assessed whether the relevant equipment qualifies under IRC §168(k), and accordingly, whether to apply the 100% full depreciation, the 40% transitional policy, or elect out. For mining machines deployed in other jurisdictions, re-evaluation based on local asset classifications and depreciation rules is necessary.
In practice, the key is ensuring alignment between accounting and tax treatments. This requires enterprises to maintain records in their fixed asset ledgers detailing equipment models, acquisition costs, placement-in-service dates, estimated useful lives, and tax asset classifications, providing a consistent data foundation for calculating deferred taxes and related processes. Given the rapid turnover of mining machines, fluctuations in useful lives, operational arrangements, and applicable tax rules are common; therefore, companies must conduct regular reviews and promptly update accounting estimates and tax judgments.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 TaxDAO