


Ethereum "Rate Cut" Heated Debate: The Unconventional EIP-8363, Is Now the Golden Window for Staking?
Written by: imToken
The Federal Reserve's "rate hike or cut" remains undecided, yet Ethereum staking, this "on-chain financial benchmark rate," is already discussing a "rate cut."
EIP-8363, which has recently sparked widespread discussion in the community, proposes a counter-intuitive new issuance mechanism: as the ETH staking ratio continues to rise, gradually increase the burn proportion in validator rewards; when the network-wide staking ratio approaches 50%, the burn will completely offset the issuance rewards.
In other words, when the network-wide ETH staking ratio reaches 50%, the annualized staking yield will drop to near 0!
Of course, this does not mean that the total Staking yield will strictly reach zero at that time, as validators may still obtain other income such as execution layer fees and MEV, but for the issuance rewards that currently account for the vast majority of staking yields, this is undoubtedly akin to "striking at the root."
It has caused a huge stir.
It should be noted that as of the time of writing, over 40 million ETH are participating in Staking network-wide, approaching about 35% of the total supply, and the protocol layer APR has also dropped to about 2.6%. Thus, a problem that once seemed somewhat distant has suddenly been placed before Ethereum:
When more and more ETH is willing to participate in Staking, is there still a need for Ethereum to continue encouraging more ETH to enter staking through new issuance?
1. Is Ethereum Starting to Worry About "Too Much Staking"?
To see this clearly, we first need to review the different stages Ethereum Staking has undergone.
As everyone knows, when the PoS mechanism was just launched, there was only one most important goal: to get enough ETH willing to enter the Beacon Chain to establish sufficiently high economic security for the entire network.
To this end, the protocol rewards validators through new issuance and simultaneously designed a dynamic yield curve: early participation in staking allows individual validators to obtain higher yields, but in the future, as more and more ETH enters Staking, the yield rate will gradually decline.
This is also why Ethereum's early staking APR was once far higher than today, and has now dropped to about 2.6%. Theoretically, this mechanism itself comes with an "automatic brake."
After all, as yields get lower and lower, someone will eventually feel it is no longer cost-effective, ultimately allowing the entire Staking market to find balance at a certain level, but the core starting point of EIP-8363 is precisely the belief that this brake may not be heavy enough.
According to the current issuance curve, even if more and more ETH enters Staking, there is still an implicit lower limit of about 1.5% for the validator's consensus layer yield. Thus, theoretically, a situation may arise where even if only more than 1% yield remains, a large amount of capital is still willing to enter.

And when an increasingly large proportion of ETH is handed over to trading platforms, custodians, LST protocols, and professional operators, the marginal contribution of additionally increased staking to economic security will become smaller and smaller, but the risks of staking concentration, governance capture, and a large amount of ETH being controlled by a few operating entities may increase accordingly.
At the same time, staking rewards essentially come from new ETH issuance. The higher the staking ratio, the higher the issuance cost the protocol pays for network security; ETH holders who do not participate in staking need to bear the corresponding dilution.
So the problem EIP-8363 wants to solve is actually when the network has already bought enough security, is there still a need to continue spending more ETH to buy additional security with diminishing marginal value?
Of course, the solution it proposes is not yet the Ethereum monetary policy determined to be executed, and there is no small controversy in the community. One very realistic objection is that if yields are suppressed too low, those who first feel it is "not cost-effective" and exit may precisely be Solo Stakers who need to bear hardware, electricity, and operations costs.
And large institutions, due to economies of scale, MEV income, or product demands, are instead more capable of continuing to stay. Then it is very likely to become "the staking rate has dropped, but the remaining people are more concentrated," which obviously conflicts with the original intention of the proposal to hope to improve decentralization and anti-capture capabilities.
Regarding this, the community is still continuing to discuss, whether EIP-8363 will ultimately be implemented and in what form it will be implemented currently has no conclusion.
But it at least releases a very clear signal, which is that Ethereum has begun to rethink a problem that rarely needed consideration in the past—were Staking yields given too much?
2. While Preparing for a "Rate Cut", Staking Has Just Entered the Compound Interest Era
Interestingly, just as Ethereum discusses reducing long-term Staking yields, the capital efficiency of staking itself has just welcomed an important upgrade.
This is EIP-7251 brought by Pectra (Further Reading "When 8 Million ETH Start "Moving House": In the Post-Pectra Era, Will Staking Welcome Structural Huge Changes?").
Simply understood, Ethereum's native staking previously could not automatically compound interest; only the principal (32 ETH) could earn money, but the interest would not automatically accumulate as principal to continue earning money. EIP-7251 allows native staking to truly form a "principal generates ETH → rewards enter principal → more ETH generates new ETH" compound interest cycle for the first time.
Actually, looking at the scale of one or two years, whether compounding interest is done on a yield of more than 2%, the difference in numbers is not that astonishing.
But where it truly plays a role is time.
Assuming a user originally planned to hold ETH for three years, five years, or even longer, then participating in Staking from the first day, the generated ETH constantly rejoins the principal. The longer the cycle, the easier the difference between the two is to be amplified.
For ordinary users using LST, "compound interest" is not a new concept; previously, many LSD/LST products have allowed users to indirectly enjoy staking yield accumulation, but the Pectra upgrade makes automatic compound interest a capability supported by the protocol itself for the first time, rather than having to rely on external products to implement, which will undoubtedly further improve the capital efficiency of the entire Staking infrastructure.
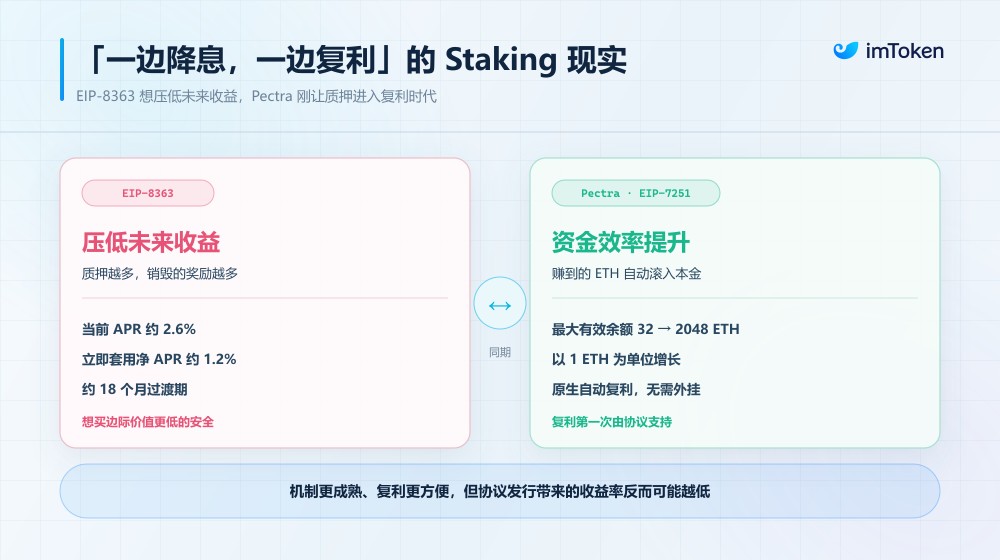
So looking at EIP-8363 and Pectra together, it forms a combination that looks contradictory at first glance but is actually very reasonable: Ethereum is striving to make "how to stake" more efficient, but that does not mean it still hopes to use more and more ETH issuance to continuously increase the economic incentive of "why to stake."
The former solves capital efficiency, the latter solves how much cost the protocol should actually pay for security.
Precisely because of this, future Ethereum Staking is likely to see an increasingly obvious trend, which is that the mechanism becomes more and more mature, compound interest becomes more and more convenient, but the yield obtained solely relying on protocol issuance becomes lower and lower instead.
This protocol layer change is also gradually transmitting to ordinary users' product experience. For example, imToken has planned to further support "automatic compound interest" for ETH native staking, allowing the new capabilities brought by Pectra to not only stay at the validator and large staking institution level but also gradually enter wallet entrances that ordinary long-term holders can directly use.
3. Is Now Instead the Golden Window for Staking?
This returns to the problem that ordinary ETH holders truly care about.
If future Staking APR may continue to decline, does it mean one should "get in quickly while yields are still high"?
Here we need to exclude a misunderstanding that is easy to arise: participating in staking now cannot lock in today's yield of about 2.6-3%.
Because Ethereum's Staking is not a long-term bond with fixed coupons after purchase. Even if EIP-8363 is ultimately implemented, or if Ethereum modifies the issuance curve through other methods in the future, validators' yields will change together.
So the so-called "window" is not rushing to grab a 2.6% long-term certificate of deposit before Ethereum "cuts rates."
What is truly valuable is actually time cost.
Assuming a user has a sum of ETH in hand and originally planned to hold for five years. Not participating in Staking in the first year and deciding to start only in the second year will not make the yield rate in the second year higher, nor can it make up for the ETH rewards missed in the first year. More importantly, the rewards that could have been earned in the first year also lose the opportunity to continue compounding for the subsequent four years.
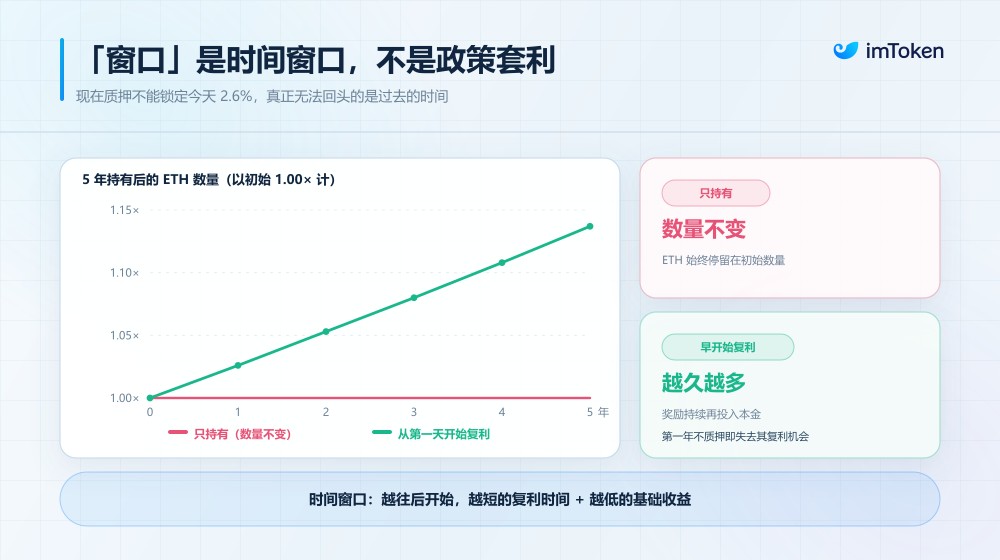
If the long-term direction of the entire Ethereum Staking in the future is indeed a gradual increase in staking rate and a gradual decrease in yield rate, then this problem will become more obvious. The later one starts, what one can enjoy may be not only shorter compound interest time but also lower base yield.
This is where "now might be a window" truly holds water; in other words, it is a time window.
Especially for users who originally planned to hold ETH long-term and have no obvious liquidity needs in the short term, the decision-making method for Staking may also need to undergo some changes.
And the author personally believes that EIP-8363 is just a trial balloon. Regardless of how the community decides subsequently, the general trend of Ethereum tokenomics is destined to move from extensive incentives towards more refined and more restrained issuance design.
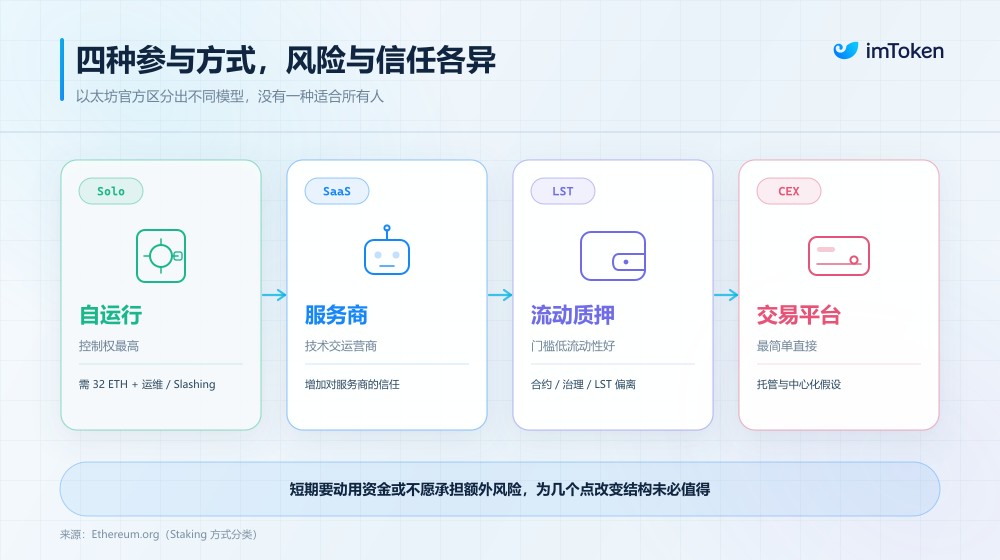
Of course, this does not mean all ETH should be taken for Staking, because any yield corresponds to costs and risks:
- Running native validators yourself can retain control rights and protocol native yields to the greatest extent, but requires at least 32 ETH, and also requires bearing costs such as node operation, offline penalties, Slashing, and daily maintenance;
- Staking-as-a-Service can hand over technical work to professional operators, but increases trust in the service provider;
- Liquid staking has a lower capital threshold and better liquidity. For example, users can directly access services like Lido through self-custody wallets such as imToken, participating in ETH staking while managing their own wallets, but this also adds extra risks such as smart contracts, governance, and LST price deviation;
- Centralized trading platforms are simpler, but mean higher custody and centralization assumptions;
So for users who may sell ETH in the short term, need to frequently mobilize funds, or are unwilling to bear these extra risks, changing their asset structure for a few percentage points of yield is not necessarily worth it.
But if the premise becomes "this sum of ETH was originally intended to be held long-term," then the answer to the question may start to become different.
Final Words
Looking back at the changes in Ethereum Staking over the past few years, it is actually very interesting.
Beacon Chain and The Merge completed the underlying transformation from PoW to PoS, Shapella solved the problem of "whether ETH can come out after being staked," and also cleared key obstacles for the further development of the liquid staking market; by Pectra, native validators began to possess automatic compound interest and higher capital efficiency.
And today's EIP-8363, the problem discussed has further become when there are already enough people participating in staking, how much new ETH should Ethereum actually pay for Staking?
From "trying to find ways to get more people to stake" to "starting to worry about whether there is too much staking," itself already explains that the stage where Ethereum Staking is located has changed.
Through great changes and steady progress, this is also a question that a market moving from early expansion to maturity must inevitably answer.
Future Staking may become more and more convenient, more and more mature, more and more like a set of standardized ETH underlying yield infrastructure, but may not become more and more profitable. For people who are truly preparing to hold ETH long-term, this is perhaps another revelation left by EIP-8363:
When yield rates themselves start to become scarcer and scarcer, what is truly precious about compound interest is actually time.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @imTokenOfficial
















