After Banks: Neobank and the Great Migration of Financial Power
By Emily, Researcher at Bitget Wallet
Introduction
Banks haven't disappeared; they are simply being dismantled.
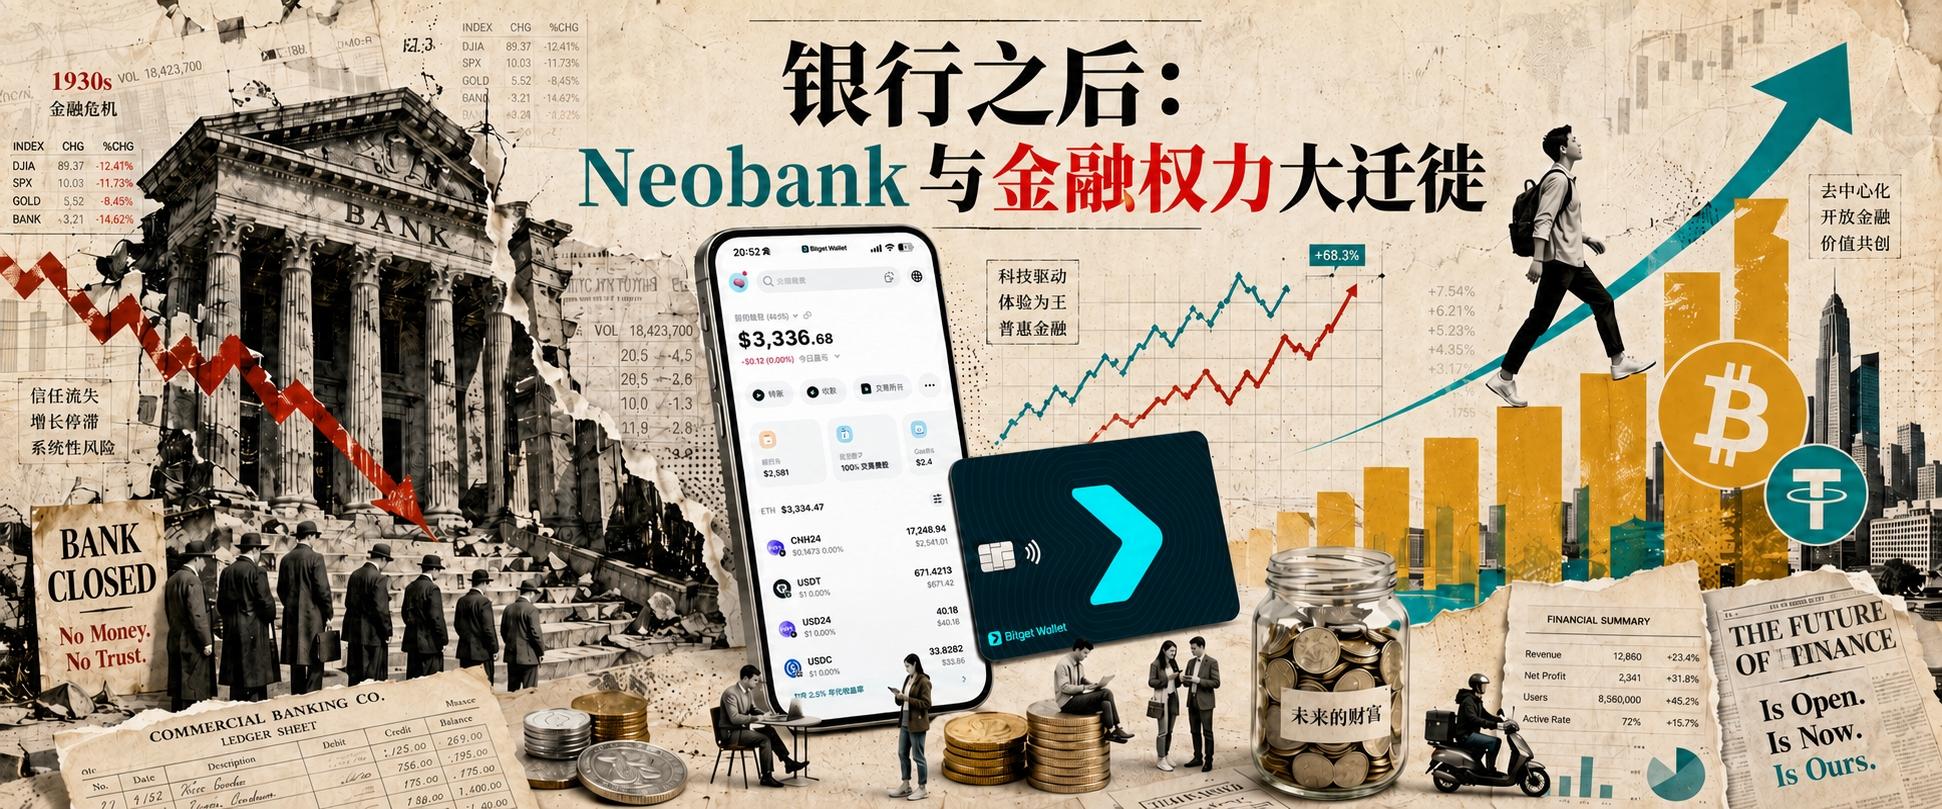
Looking back at nearly 20 years of financial innovation history, we find an interesting yet long-overlooked phenomenon: all stories previously labeled as "financial innovation," whether digital banks, super apps, stablecoins, or today's rapidly rising on-chain wallets, are fundamentally not creating new banks, but constantly dismantling the various powers once monopolized by traditional banks.
For over a century, commercial banks have become the most central organization in the modern economic system not because they are inherently more efficient than other institutions, but because they have long simultaneously held four critical financial capabilities: they manage accounts, organize payments, facilitate currency circulation, and control the ultimate clearing network. For ordinary users, vastly different financial activities such as savings, remittances, consumption, investment, and lending are all uniformly packaged into a single product called a "bank account." This creates the illusion that banks are naturally meant to fulfill all financial functions.
However, following the 2008 financial crisis, this financial organizational model, which had persisted for nearly a century, began to show cracks for the first time.
When Lehman Brothers collapsed, Citigroup fell into crisis, and the global financial system relied on unprecedented government bailouts just to keep running, people realized for the first time that banks might not be the only possible organizational form for financial services. Precisely at this historical juncture, two routes emerged that would later profoundly transform the global financial industry:
- One route sought to redesign the banking experience using mobile internet technology, giving rise to the first generation of Neobanks represented by Revolut, Monzo, Nubank, and Chime;
- The other route aimed to redesign the monetary and clearing systems from the ground up. Beginning with Satoshi Nakamoto's Bitcoin whitepaper, this path ultimately evolved into stablecoins, DeFi, and the on-chain financial account systems that are rapidly developing today.
Looking back at the past 18 years of evolution, we see that the history of Neobanks is never merely a story of bank digitization, but rather a continuous migration of financial power.
This migration has roughly gone through four stages:
- In the first stage, initial Neobanks migrated financial power from bank licenses to the user entry point;
- The second stage saw native payment Neobanks extract payment and clearing networks from the exclusive financial powers of banks;
- The third stage involved native stablecoin Neobanks stripping out the global digital dollar system from banking financial power;
- And the fourth stage happening today, native on-chain Neobanks are attempting the final step—returning financial power ultimately to the users themselves.
We believe that understanding this process may be even more important than comprehending the business model of any specific company.
First-Generation Neobanks: When Banks First Became Internet Products
What is a Neobank? Literally meaning "new-style bank," the term actually encompasses a very broad range of meanings.
Technically defined, a Neobank is a new-generation financial service institution that operates entirely digitally without relying on physical branches, offering seamless account opening, transfers, wealth management, consumption, and cross-border remittance services via mobile apps or web platforms. Although many Neobanks lack traditional "bank licenses," they partner closely with licensed traditional banks behind them, enabling them to provide financial services protected by national deposit insurance.
Today, when people discuss major Neobank representatives like Revolut, Nubank, or Chime, they habitually label them as digital banks. However, looking back to when these companies were founded, what they truly aimed to solve was not banking operations, but user experience.
Because before 2010, the user experience for almost all banking products globally was extremely poor.
Account opening required appointments, transfers took days, cross-border remittances incurred high fees, credit card applications dragged on for weeks, and banking systems themselves ran on core infrastructure built decades ago. For a large number of young users, banks increasingly resembled a forced public utility rather than a true consumer product.
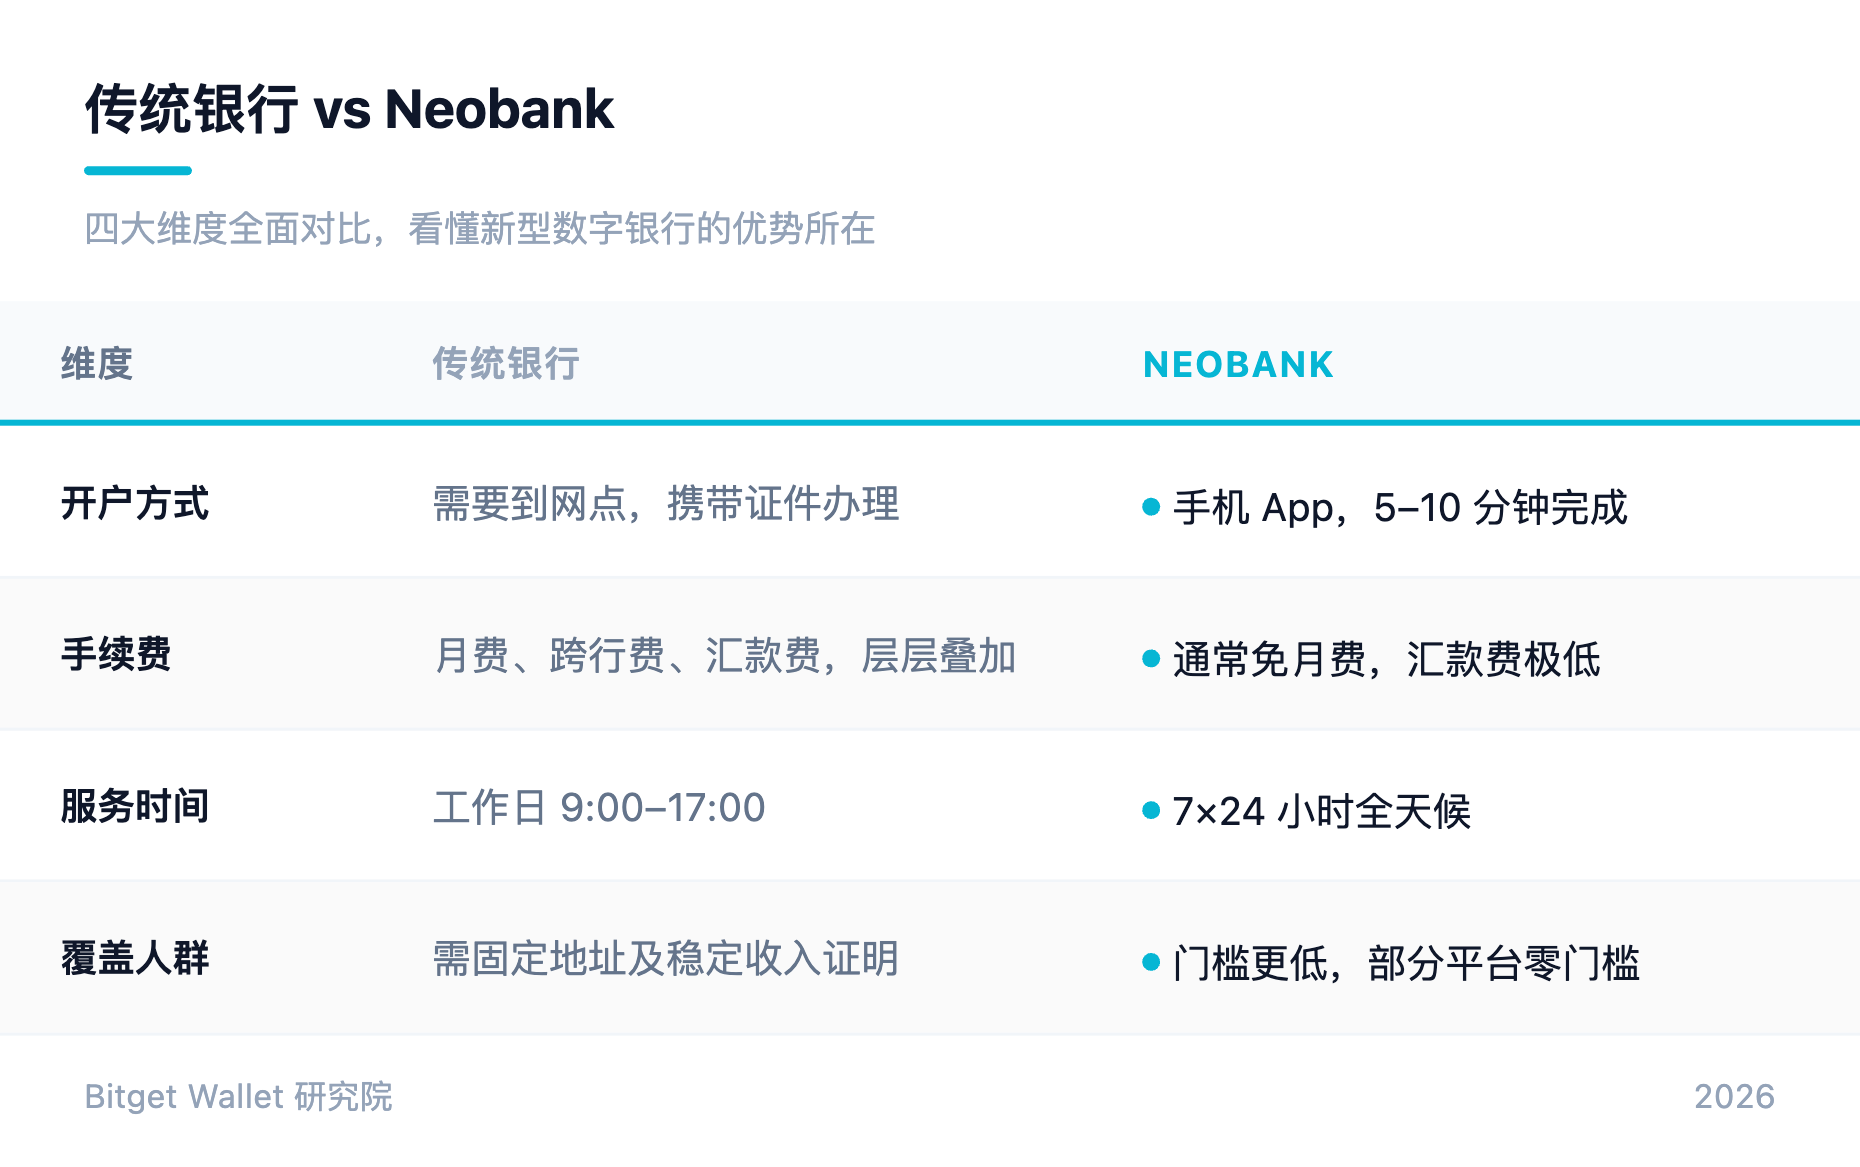
The crucial insight of first-generation Neobank founders was recognizing that users don't love banks; they simply need financial services. Therefore, if banks can be repackaged as mobile internet products, user loyalty will shift from the bank license itself to the product.
This logic was first validated in the UK.
Revolut, founded in the UK in 2015, initially solved a very straightforward problem: why are cross-border payments so expensive?
In the traditional banking system, an international remittance often passes through multiple correspondent banks and clearing institutions, taking several days and charging fees that typically amount to several percentage points. Revolut's solution wasn't to reinvent currency, but to compress the previously complex cross-border payment experience into a single mobile action through its app, multi-currency accounts, and a more efficient FX settlement system.
Ten years later, Revolut has become the largest Neobank globally. According to disclosures, by the end of 2025, Revolut ranks among the world's largest digital banks, boasting 68.3 million retail users worldwide, 767,000 corporate clients, customer asset balances of $67.5 billion, annual revenue of $6 billion, pre-tax profits of $2.3 billion, total transaction volume of $17 trillion, and profitability that surpasses most traditional European commercial banks.
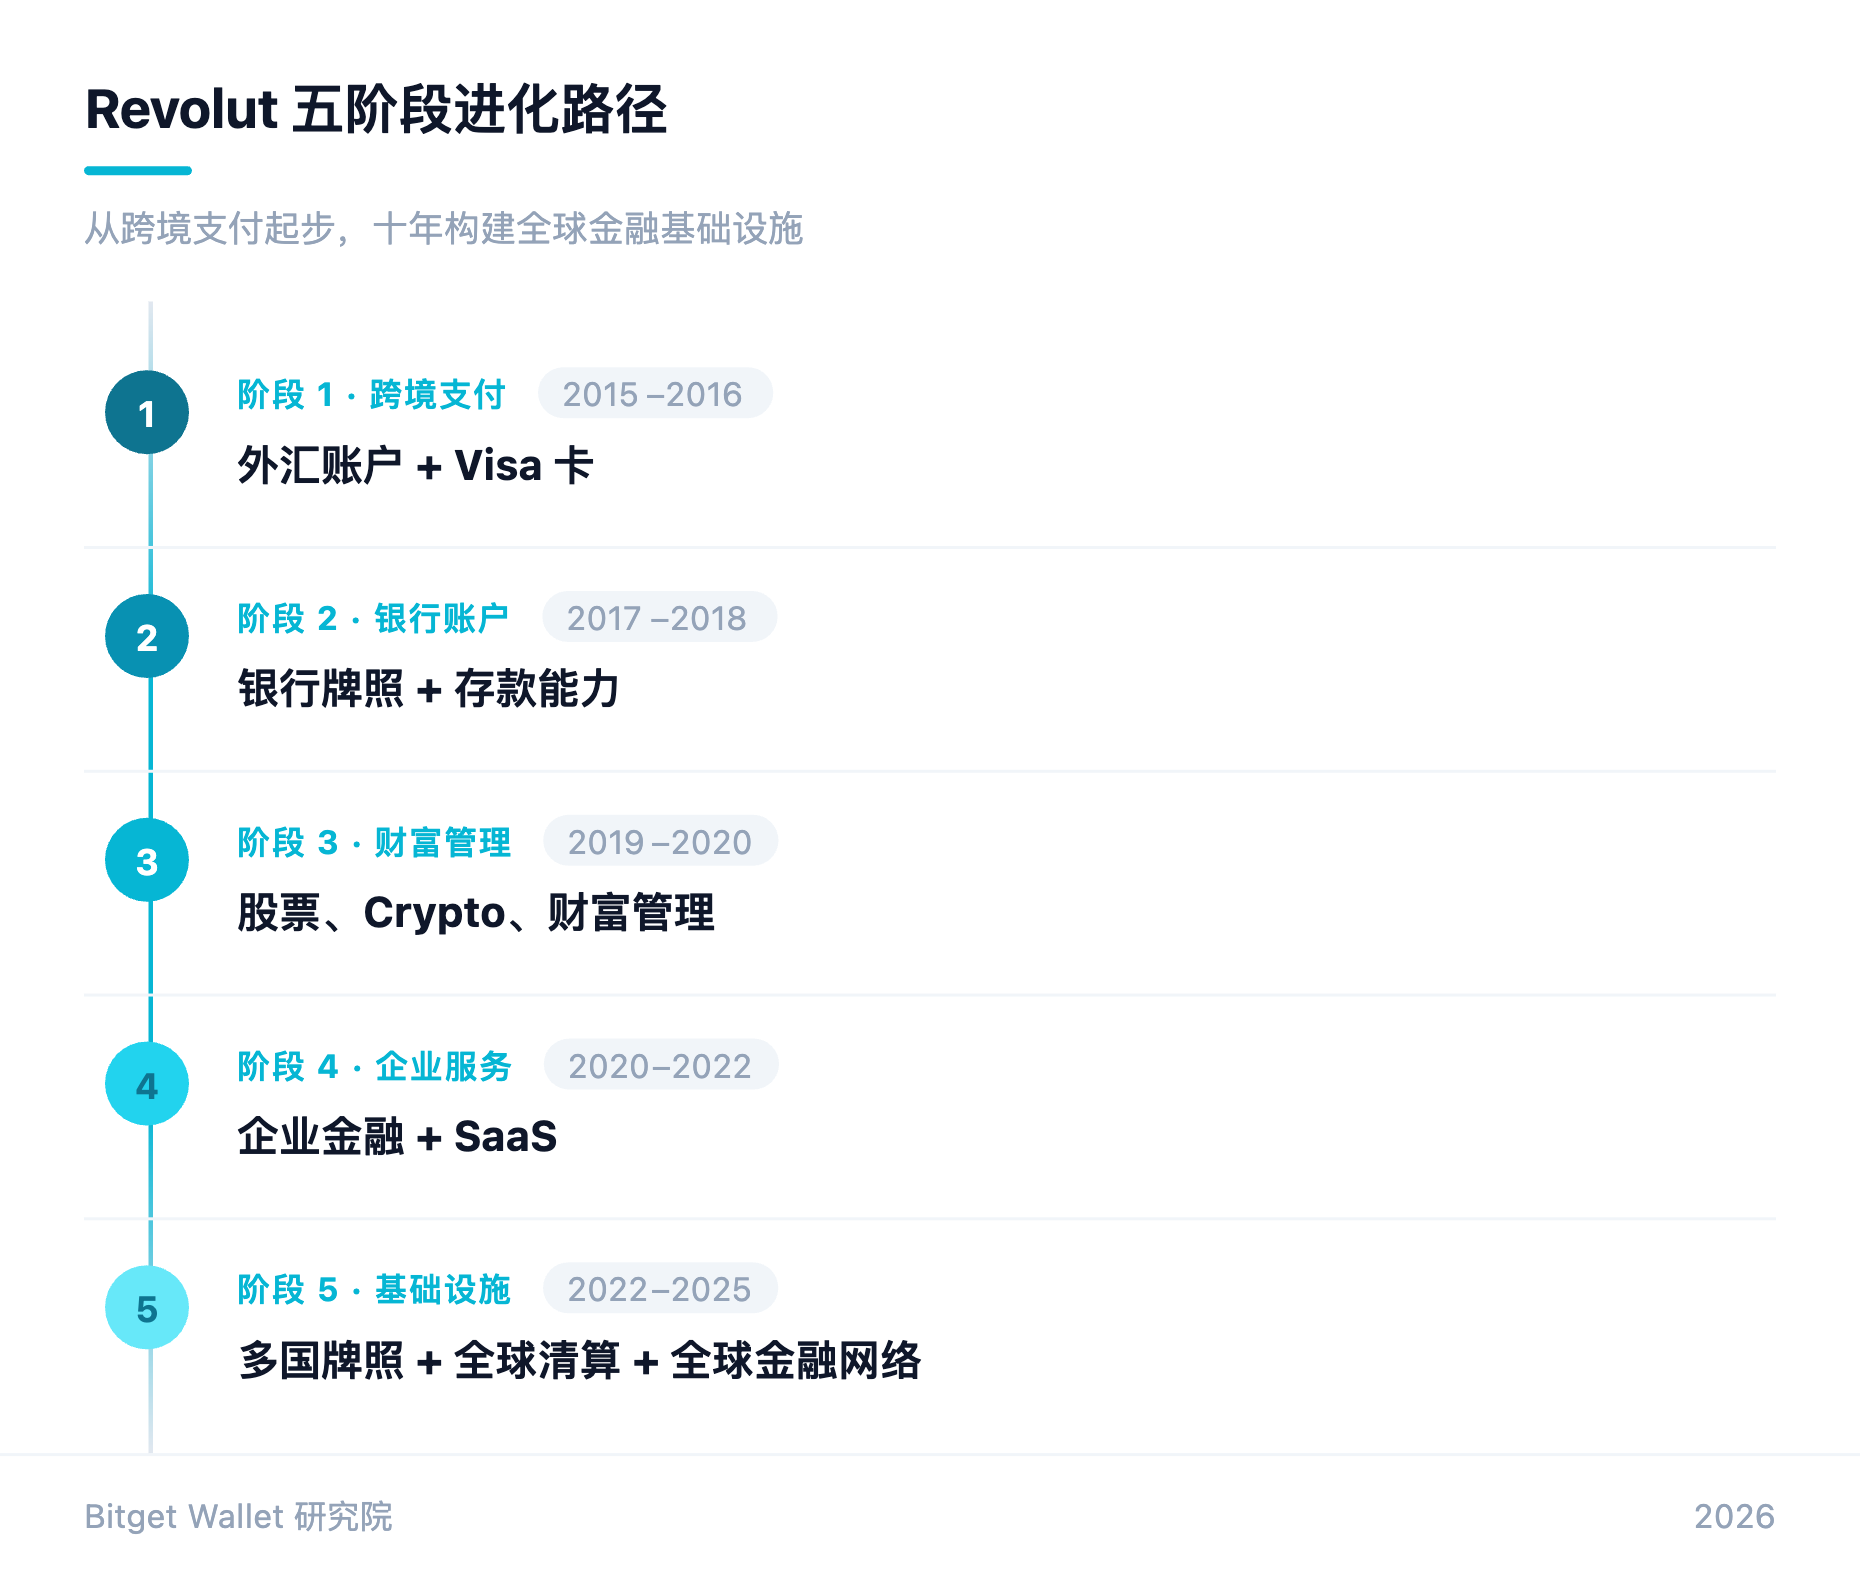
However, analyzing from the perspective of financial power reveals that Revolut hasn't truly achieved a banking revolution, but rather the first attempt at transferring and extracting banking power.
Regarding clearing path control, Revolut is no longer a digital bank in the early sense. After a decade of evolution, it has gradually built its own global multi-currency ledger system, internal FX matching engine, corporate payment network, and partial merchant clearing capabilities, thereby mastering a significant degree of payment orchestration. Nevertheless, whether for card transactions, cross-border transfers, or final fund settlements, the underlying infrastructure remains highly dependent on traditional financial networks like Visa, Mastercard, SEPA, and Faster Payments. This means that while Revolut has partially gained control over payment paths, ultimate clearing authority still rests with national and international payment networks.
In terms of treasury management, Revolut's business model has undergone a fundamental shift. Unlike its early reliance on FX spreads and interbank interchange fees, by 2025 its revenue structure had gradually pivoted toward client funds float, wealth management, corporate finance, subscription services, and interest income from rate environments. With client assets growing to $67.5 billion, Revolut now possesses capital operation capabilities akin to traditional commercial banks and asset managers, achieving a pre-tax profit margin of approximately 38%, outperforming profitability metrics at many historic European banks.
Yet, at the account architecture level, Revolut has not altered the core organizational principle of the modern financial system: accounts ultimately belong to financial institutions, not users themselves. While users enjoy unprecedented financial experiences and global service capabilities, their assets essentially remain within Revolut's controlled centralized ledger system. Account ownership, portability, and ultimate control have not fundamentally changed. In this sense, Revolut redefined the user experience of banking without redefining the account itself.
A similar story also unfolded in Latin America.
Founded in 2013, Nubank's success stemmed not from inventing new financial products, but from identifying that hundreds of millions in Latin America lacked access to quality financial services for too long. In Brazil, traditional banks long maintained high-fee, high-barrier, and inefficient operational models. Nubank rapidly built a massive user base through a fully digital user experience and exceptionally low service costs.
By the end of 2025, Nubank surpassed 131 million users, becoming the world's largest digital bank, with annual revenues reaching approximately $16.3 billion, net profits of $2.9 billion, and customer deposits totaling $41.9 billion. More importantly, Nubank's monthly active user ratio has reached levels unattainable by traditional banks. In its core market of Brazil, roughly 60% of users now consider Nubank their primary bank account. For a digital bank only over a decade old, this user stickiness no longer fits the traditional banking paradigm and instead resembles a comprehensive financial platform covering payments, savings, lending, investment, and wealth management.
Like Revolut, although Nubank secured the user entry point, it still lacks control over the ultimate payment and clearing networks. It relies on Brazil's PIX system, card networks, and traditional financial infrastructure to operate. Thus, it has only completed the first stage of financial power migration: users begin to detach from bank licenses, but funds remain tied to traditional financial rails.
The U.S. market offers another fascinating case study.
Chime's success demonstrates that even bank licenses may no longer matter. By partnering with licensed banks, Chime outsources all regulatory compliance and clearing, concentrating its resources entirely on user growth and product experience. To date, Chime boasts over 25 million users, and its business model has essentially morphed into that of a consumer internet company rather than a traditional bank.
Looking back at the competition among first-generation Neobanks, we realize they didn't achieve a banking revolution, but rather an account entry-point revolution.
They proved for the first time that bank account entry points don't inherently belong to banks and can belong to an app; financial services don't need to be organized around licenses but can be organized around users; and a bank's widest moat isn't the license itself, but user relationships.
However, once first-generation Neobanks acquired tens of millions to over a hundred million users, a new problem emerged: although they owned the users, they did not own the genuinely profitable segments of the financial system.
Because what truly controls the financial world is never the account itself, but the clearing mechanism.
Native Payment Neobanks: When Financial Power Migrates from Bank Accounts to Payment Networks
After first-generation Neobanks accumulated tens of millions of users, a counterintuitive fact surfaced: although users began leaving traditional banks, the financial industry's most profitable, stable, and monopolistic segments remained firmly held by another group of companies.
By 2025, Revolut's global users exceeded 68 million, Nubank surpassed 130 million, and Chime topped 25 million. By sheer user count, they had become among the world's largest financial platforms. Yet these companies quickly discovered that every purchase, transfer, cross-border remittance, and fund settlement still had to pass through another, vastly larger, more invisible, and far more lucrative infrastructure network.
This network is not a bank. It is the payment network.
For a long time, people assumed Visa and Mastercard are merely card companies, but this severely underestimates their true standing. Visa has never issued loans nor directly manages client assets, and Mastercard doesn't hold user accounts. Yet, as of fiscal year 2025, Visa's global total payment transaction volume reached $16.7 trillion, processing 257.5 billion transactions annually, with nearly 4.9 billion valid payment credentials on file, generating $40 billion in annual revenue and over $20 billion in net profit, maintaining a net margin around 50%. Meanwhile, Mastercard's global transaction scale also surpassed $10 trillion, with annual revenue exceeding $30 billion and net margins consistently hovering near 45%.
Their status as the world's most profitable financial enterprises stems not from owning users, but from possessing another, more critical power: clearing path control.
In traditional financial systems, accounts are merely the starting point for funds, while the clearing network itself dictates how money flows, where it goes, and what fees are charged. The success of Visa and Mastercard is fundamentally built on an extraordinarily elegant business model: they assume no credit risk, bear no balance sheet exposure, and do not compete for fund ownership. Instead, they focus exclusively on operating as toll highways for global capital flows.
This is particularly evident in the cross-border remittance sector.
Founded in 2011, Wise (formerly TransferWise) stands as one of the most representative companies among native payment Neobanks. Unlike Revolut, which attempted to redesign bank accounts, Wise never aimed to become a bank from day one. It solved only one problem: why do cross-border remittances need to be so complicated?
The core assets of traditional cross-border remittances are bank licenses, the SWIFT network, and the correspondent banking system; whereas Wise's core assets are local clearing accounts, liquidity pools, and algorithmic matching systems.
This means that in Wise's world, cross-border payments are no longer treated as single international transactions, but rather as a combination of localized trades.
Within the traditional SWIFT network, an international remittance typically traverses multiple correspondent banks, takes several days, and incurs fees at each intermediate node. Consequently, what appears as a simple cross-border transfer conceals a vast and inefficient global web of correspondent banking.
Wise's innovation lies not in reinventing currency, but in restructuring clearing. By establishing local fund pools and domestic clearing networks across various countries, it transformed cross-border capital movements into mutual offsets and matches within individual nations, drastically reducing both the cost and time required for cross-border payments.
According to The Wall Street Journal, by 2026, Wise's active users reached 18.9 million, up 21% year-over-year; client funds on balance hit $39 billion, up 40%; annual cross-border transfer volume totaled $243.5 billion; and pre-tax profits reached $660 million with a profit margin of 26%. Its core competitiveness derives not from a banking license, but from its globally distributed local clearing network.
This signifies that financial power begins its second major migration.
First-generation Neobanks competed for accounts. Second-generation financial infrastructure competes for capital flow.
Those who truly control capital flows invariably make more money than those who merely hold accounts.
This logic becomes even more pronounced in the U.S. market.
PayPal boasts over 440 million active accounts, Cash App exceeds 60 million monthly active users, and Venmo's annual payment volume surpasses $330 billion. Though these products resemble payment tools, they essentially all vie for the same thing: the user's cash flow entry point.
Looking back at this phase's development, a clear pattern emerges: banks manage assets, payment networks manage liquidity, and liquidity often matters more than static assets.
Yet, even Visa, Mastercard, and Wise fail to resolve a fundamental question: why must the U.S. dollar rely on banks and payment networks to exist?
This question was ultimately answered by stablecoins.
Native Stablecoin Neobanks: When the Dollar Begins to Exist Independently of Banks
Over the past century, the U.S. dollar has always depended on the banking system for its existence. Whether for savings, remittances, payments, or international trade, dollars must circulate through commercial banks, central banks, and global clearing networks.
If first-generation Neobanks unbundled bank accounts, and second-generation fintech unbundled payment networks, then third-generation native stablecoin Neobanks have truly separated the most vital financial consensus of the past century: that the dollar must rely on banks to exist.
As of the first half of 2026, the global circulating market cap of stablecoins reached approximately $250 to $270 billion, with USDT circulating supply exceeding $160 billion and USDC nearing $65 billion. Global annual stablecoin transaction volume has climbed to tens of trillions of dollars, beginning to surpass many traditional payment networks. For the first time, stablecoins prove that the dollar can achieve large-scale global circulation and settlement without relying on commercial bank accounts, SWIFT, or national payment systems, emerging as a truly independent monetary infrastructure outside the traditional banking framework.
This shift first materialized in regions where traditional banking systems are weakest, such as Argentina. Over the past decade, the Argentine peso has depreciated cumulatively by over 99%, prompting many residents to effectively treat USDT as a genuine savings account rather than a speculative crypto asset.
Similar scenarios unfold in Nigeria, Turkey, Venezuela, Indonesia, and the Philippines. This explains why the majority of third-generation Neobanks originated in emerging markets.
Take RedotPay as an example. Rather than a conventional digital bank, it is a consumer finance platform centered around stablecoin accounts. Users need not hold USD bank accounts; simply holding USDT enables asset custody, cross-border remittances, and daily spending. By 2025, its services spanned over 150 countries and regions, accumulating millions of users.
Kast pushes the logic further. Kast is attempting to integrate stablecoin accounts with yield-bearing assets like U.S. Treasuries, allowing users to earn on-chain yields while holding digital dollars and complete real-world purchases via Mastercard networks. If successful, this marks the first time that deposit-taking, payments, and asset management—the pillars sustaining traditional banks—are dismantled and recombined.
Meanwhile, Felix Pago has emerged as one of Latin America's most representative stablecoin remittance networks. Using WhatsApp as its frontend interface and leveraging USDC and blockchain as its underlying settlement infrastructure, it drastically reduces costs and settlement times for cross-border remittances from the U.S. to Mexico. Users reap efficiency gains from digital dollar networks without ever needing to understand how stablecoins or blockchain function.
Comparing along the following dimensions reveals that native stablecoin Neobanks have fundamentally diverged from their first-generation predecessors:
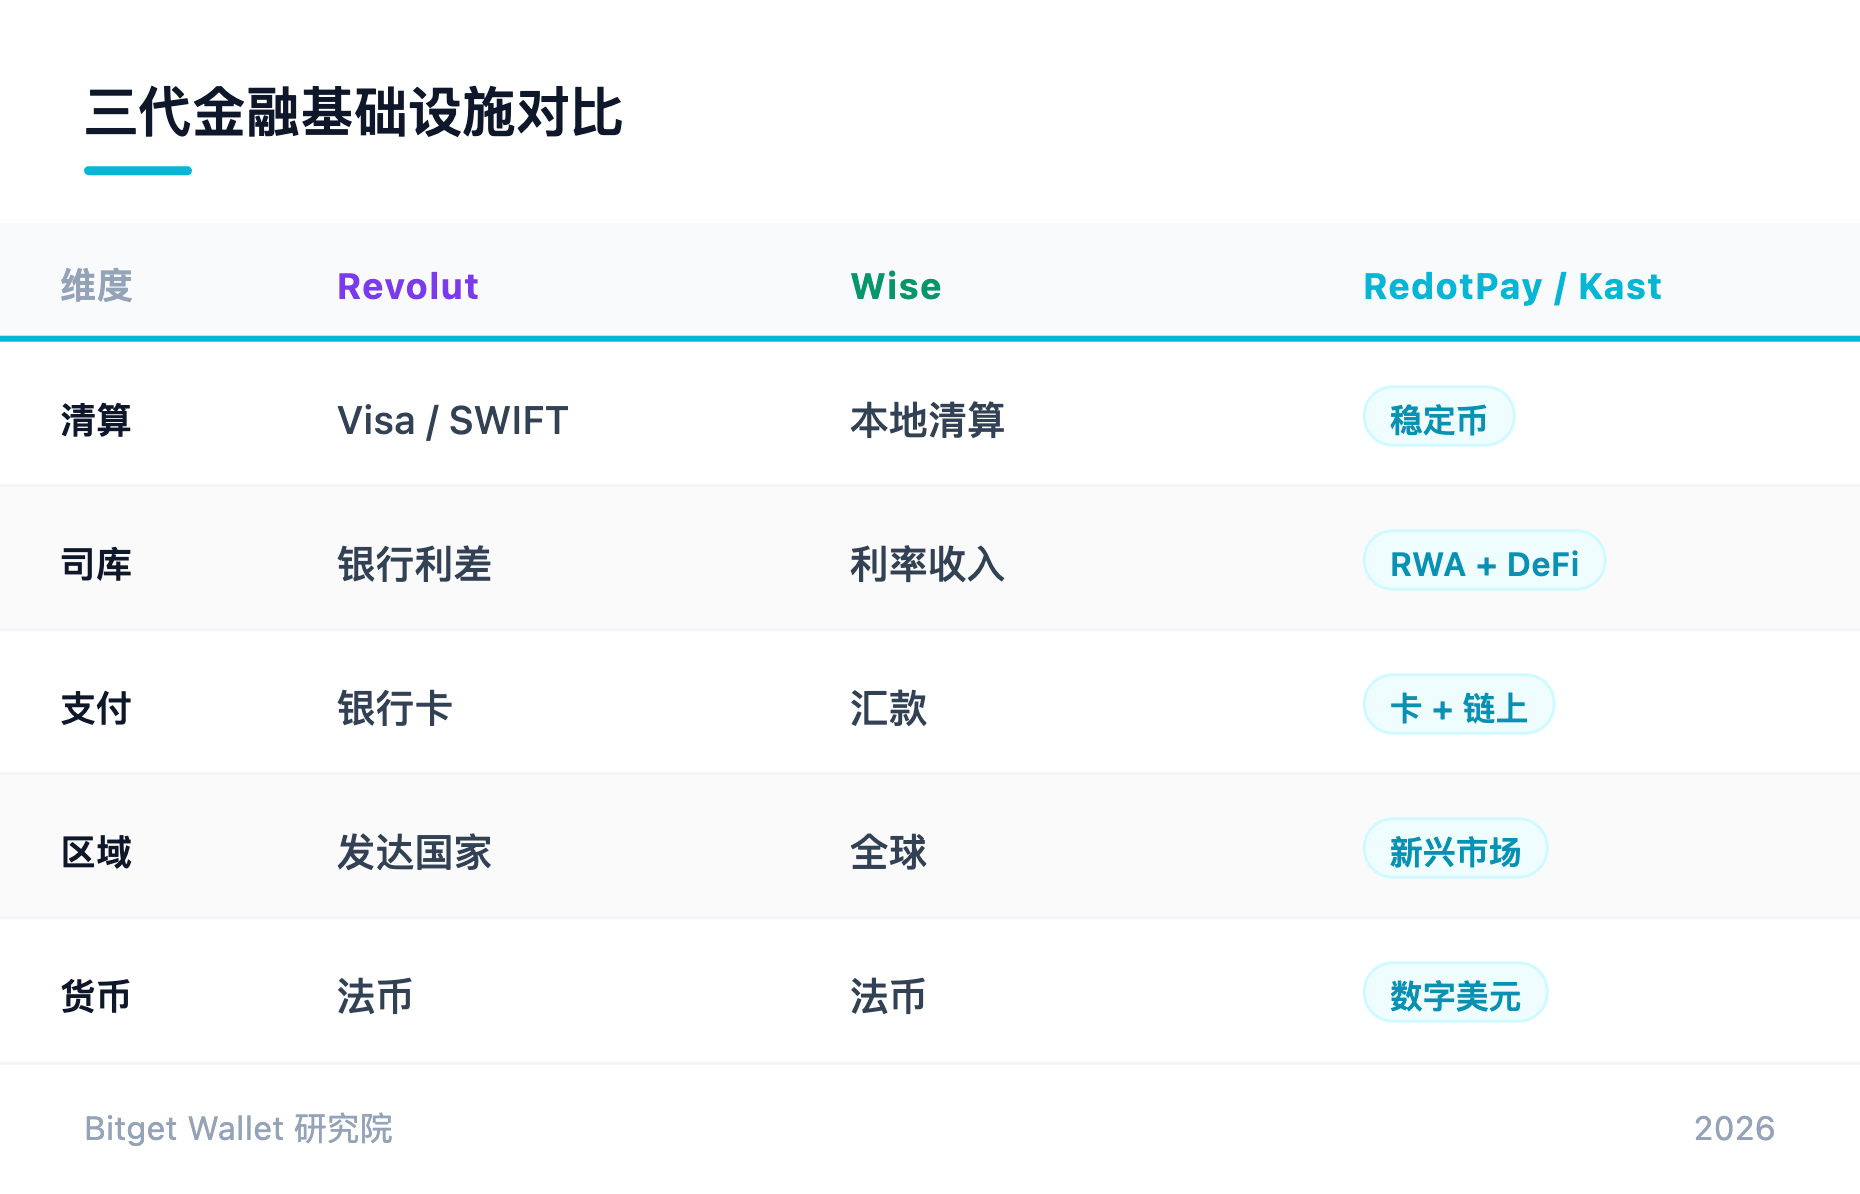
They demonstrate for the first time: the dollar does not require banks. The most crucial asset in the financial system may no longer be bank accounts, but global digital dollar accounts.
Even so, one final question remains unanswered.
If currency already exists independently of banks, why must accounts still belong to them?
Native On-Chain Neobanks: Accounts Begin Belonging to Users Themselves
If the previous three migrations of financial power were essentially redistributions among institutions, the fourth migration heads in an entirely different direction.
Because this time, power begins flowing directly to the users themselves.
By 2026, the global user base of non-custodial wallets has surpassed hundreds of millions. MetaMask has cumulatively broken past 100 million users, Trust Wallet also reaches the nine-figure mark, and Bitget Wallet is rapidly building an integrated financial ecosystem spanning trading, payments, yield, and consumption. Together, they prove one undeniable fact: wallets are no longer mere coin storage tools; they are evolving into global financial accounts.
Represented by Bitget Wallet, Gnosis Pay, Ether.fi Cash, Coinbase Wallet, MetaMask, and OKX Wallet is neither a new payment product nor a new banking tool, but a completely novel method of financial organization.
Gnosis Pay's greatest innovation isn't issuing a Visa card, but for the first time linking a Visa card directly to a user's own on-chain account. Previously, whether in traditional or digital bank accounts, assets ultimately resided in databases controlled by financial institutions. In Gnosis Pay's architecture, user assets remain permanently within their personal on-chain wallets; the bank card merely serves as an entry point connecting to real-world payment networks. When users tap or swipe to pay, the system reads their on-chain assets in real-time and settles transactions automatically. This means, for the first time, a bank card corresponds not to a bank, but to an account owned and controlled entirely by the user.
This implies that user assets can seamlessly fund real-world purchases without ever being deposited into a bank or loaded onto a centralized account. If Revolut transformed the banking experience, Gnosis Pay attempts to transform account ownership itself.
Similarly, Ether.fi Cash endeavors to unify stablecoins, ETH yield-generating assets, on-chain returns, and real-world purchasing power within a single on-chain account, progressively exploring the integration of RWA assets like U.S. Treasuries into this framework.
The true innovation represented by native on-chain Neobanks like Bitget Wallet isn't creating another digital bank, but making the first attempt to unify accounts, payments, yield, trading, global asset allocation, and real-world consumption into a financial operating system owned and controlled by the user. Within this ecosystem, wallets cease to be mere asset containers and begin evolving into a new form of financial infrastructure itself.
- First-generation Neobanks' core asset is: Users
- Second-generation payment infrastructure's core asset is: Clearing networks
- Third-generation native stablecoin Neobanks' core asset is: Digital dollars
- Fourth-generation native on-chain Neobanks' core asset becomes: The global financial account itself, owned by the user
Across Neobank analytical dimensions, it possesses simultaneously for the first time:
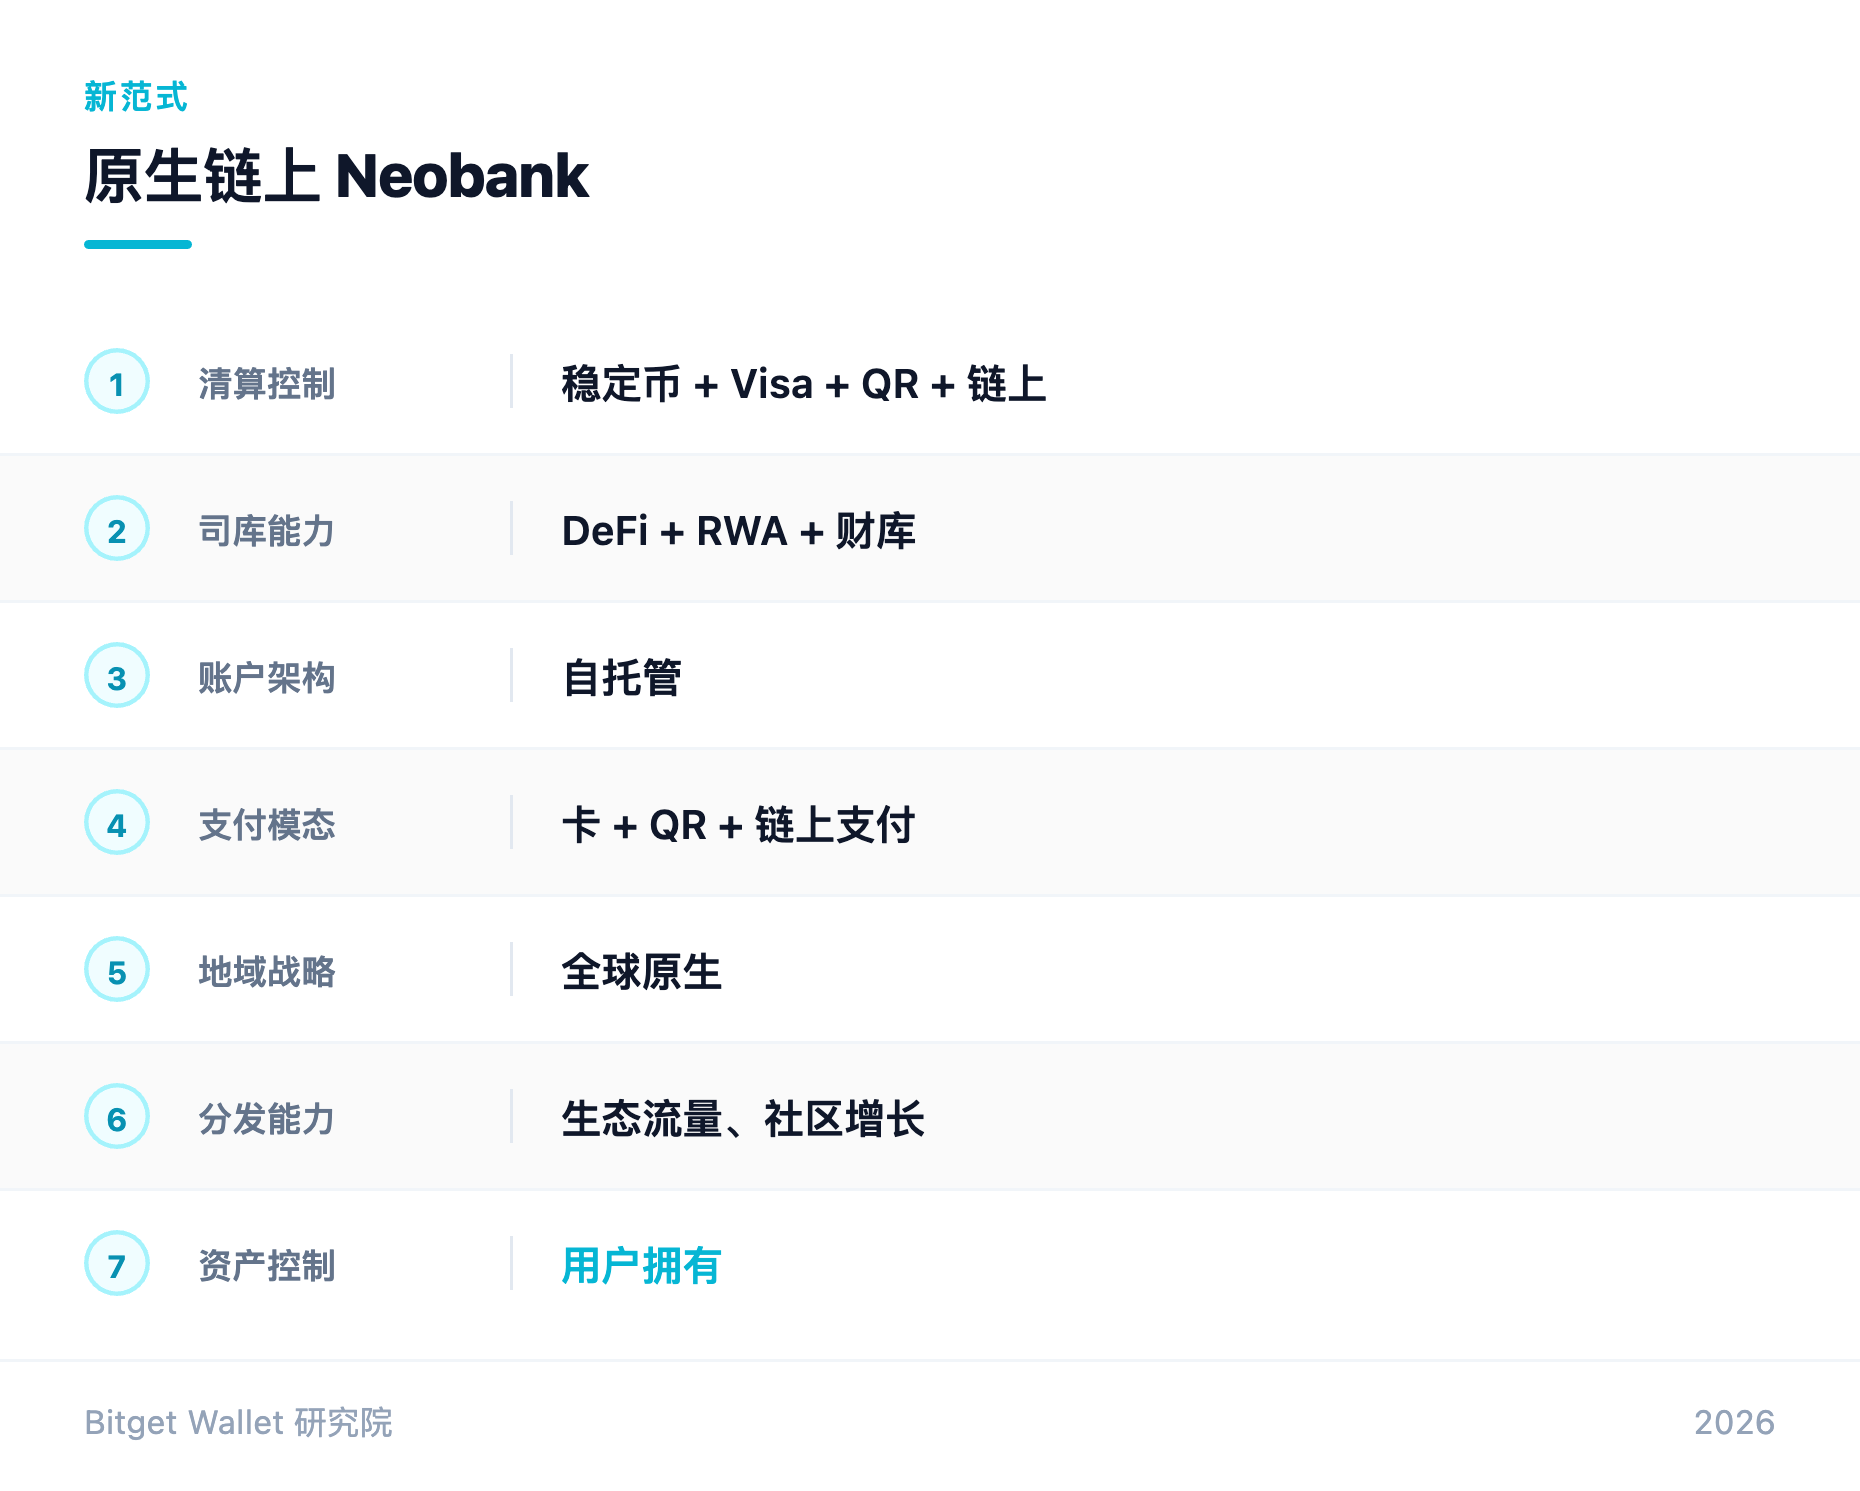
Most crucially, it integrates for the first time: accounts, assets, payments, yields, and identity into a single unified system.
This means the wallet's true competitor was never another wallet. Its actual target of competition is: bank accounts, Revolut, PayPal, Cash App, and Apple Wallet.
Because it is vying not for a single financial feature, but for: the user's singular global financial account.
The Ultimate Destination of Neobanks May Not Be Banking at All
Reviewing twenty years of financial innovation history, we ultimately uncover a clear pattern.
- First-generation Neobanks redefined bank accounts;
- Native payment Neobanks redefined payments and clearing;
- Native stablecoin Neobanks redefined currency;
- And native on-chain Neobanks are currently redefining account ownership itself.
Thus, the history of Neobanks is never merely an evolutionary chronicle of digital banks, but a continuous narrative of shifting financial power.
Over the past two decades, this migration followed a distinct trajectory: from banking licenses to user entry points, from entry points to payment networks, from networks to stablecoins, and today, it migrates toward global on-chain accounts.
Should this trend persist, perhaps the most critical question of the next decade will no longer be: Which bank will become the largest digital bank?
Nor even: Which stablecoin will emerge as the global currency?
The real question may be: Once banking, payments, currency, and accounts fully decouple from one another, who will become each person's singular global financial account?
And that answer likely won't be a bank.
But a wallet.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @BitgetWallet