


Goldman Sachs Research Decoded: Micron's Quarterly Revenue Seen at $51.9 Billion, Capital Returns Take Focus
By Rita
In its forward-looking report on Micron Technology released on September 11, 2026, Goldman Sachs maintains a neutral rating with a 12-month target price of $1,100. Based on the closing price of $977.41 on September 10, this implies an upside potential of 12.5%. The target price is based on 18x normalized EPS of $62. Goldman Sachs estimates Micron's revenue for the current quarter at $51.9 billion, with a gross margin of 87.3% and EPS of $32.54, both exceeding market consensus.
Goldman Sachs analyst James Schneider notes in the report that investors are focused on Strategic Customer Agreements (SCAs), capital return plans, and HBM4 product trends. With DRAM and NAND supplies remaining tight, Goldman expects Micron to deliver another strong quarter, with revenue and guidance likely surpassing market expectations. Investor positioning leans positive due to persistent DRAM and NAND shortages, though some investors worry about long-term supply increases from competitors, particularly in China.
Current Quarter Revenue Expected at $51.9 Billion, Exceeding Consensus
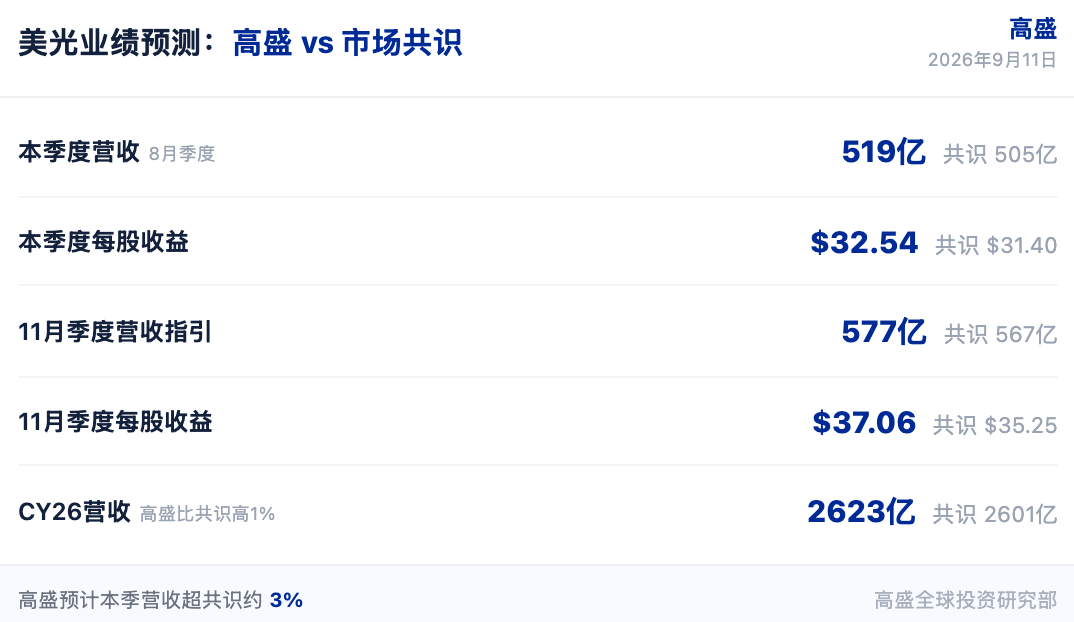
Goldman estimates Micron's quarterly revenue at $51.9 billion versus market consensus of $50.5 billion. Gross margin is expected at 87.3%, compared to consensus at 87.0%. EPS is projected at $32.54 versus consensus of $31.40. Revenue exceeds consensus by approximately 3%.
For the November quarter guidance, Goldman forecasts revenue of $57.7 billion against consensus of $56.7 billion. Gross margin is expected at 88.1%, versus consensus at 87.5%. EPS is projected at $37.06 versus consensus at $35.25. Goldman expects Micron to guide for low double-digit sequential revenue growth in the November quarter, driven by product mix and incremental pricing.
Goldman notes that DRAM price momentum remains, with investor expectations running high but more moderate than in prior quarters. Micron currently holds approximately 20% share in HBM, and investors expect the company to maintain or expand this position.
CY26 Revenue and EPS Forecasts Above Market
Goldman's revenue and EPS forecasts for CY26 are 1% and 3% higher than market consensus, respectively. CY26 revenue is projected at $262.3 billion versus consensus at $260.1 billion. CY27 revenue is estimated at $267.6 billion versus consensus at $264.7 billion. CY28 revenue is forecast at $280.2 billion against consensus at $260.6 billion.
Goldman also introduces CY29 projections, forecasting revenue of $284.5 billion and EPS of $174.22. The firm raises its revenue and EPS forecasts based on the latest DRAM demand outlook and recent pricing trends. Goldman's CY27 revenue forecast is 4.9% higher than previous estimates, with gross margin guidance 80 basis points above old forecasts.
Strategic Customer Agreements and Capital Returns in Focus
Goldman believes investors expect Micron to sign additional strategic customer agreements, focusing on how pricing levels compare to prior deals. The pricing structure of these SCAs is a key market focus, directly impacting revenue visibility and margins over the coming quarters.
Regarding capital returns, Goldman anticipates that management commentary on share repurchase programs will be a focal point, particularly following the lifting of restrictions under the CHIPS Act. Previously constrained by CHIPS Act provisions, Micron's buyback capacity was limited. With restrictions eased, the market is watching whether the company will initiate large-scale repurchases. Goldman views the scale and timing of capital return programs as key variables influencing stock performance.
HBM4 Roadmap to Determine Market Share
On the HBM roadmap, Goldman expects Micron to comment on its HBM market share and provide further details on HBM4 shipments and HBM4E sampling. Goldman notes that investors anticipate Micron will maintain or expand its current ~20% HBM share. The shipment cadence for HBM4 and progress on HBM4E sampling are core indicators for assessing Micron's competitive position in next-generation high-bandwidth memory.
Upside risks listed by Goldman include continued execution of the HBM roadmap and share growth, alongside a significant increase in HBM content per AI accelerator. Downside risks include CXMT continuing to gain DRAM market share, negatively impacting pricing dynamics. As a Chinese DRAM manufacturer, CXMT's expansion could suppress DRAM prices.
Goldman points out that post-earnings discussions will continue to center on long-term customer agreements, excess capital returns, and long-term supply increases, particularly from China. The firm believes the long-term debate surrounding Micron hinges on how long current pricing advantages driven by tight supply will last, and whether capacity expansion by Chinese competitors will alter the supply-demand landscape.
Disclaimer
This article is a compilation and interpretation by TechFlow Research of a third-party brokerage research report (Goldman Sachs, September 11, 2026), combined with publicly available market information. The ratings, target prices, earnings forecasts, and related judgments cited herein reflect the views of that broker's analysts and represent only the stance of their respective institutions, not those of TechFlow Research, nor do they constitute any investment advice.
Markets carry risk; investment decisions must be independent. This article should not be used as a basis for buying or selling any securities.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @chaoxiangooo










