


Ether.fi Surpasses $100M in Monthly Revenue, Yet Token Drops 21%: Can a Buyback Vote Save It?
Author: Alea Research
Compiled by: TechFlow
TechFlow Guide: Ether.fi’s consumer business has surpassed $100 million in monthly transaction volume, yet the ETHFI token is down 21% year-to-date. Can the buyback vote serve as a price catalyst? This article breaks down the revenue structure of its account model, the funding sources for the buyback, and the key variables ahead of the voting deadline, making it highly relevant for holders and those tracking the on-chain financial accounts sector.
A broader financial account. Ether.fi combines investing with everyday payments, creating more revenue streams per customer.
Cash spending up 85%. Monthly transaction volume grew from $54.3 million in January to $100.3 million in July. Its share of tracked card spending remains around 10%.
ETHFI: Down 21% year-to-date. At $0.55, its trailing annualized revenue multiple based on a fixed maximum supply stands at 14.2x.
$16 million in annualized buyback funding. This example proposal uses July data, is pending approval, and does not account for reward distributions.
September 3: Voting deadline. The proposal requires 1 million ETHFI to reach quorum. Borrowings added to the pool total $50 million, compared to $26 million in the proposal.
Ether.fi's Account Vision
Ether.fi aims for customers to manage funds within a single self-custody account. In May 2024, it announced a vision integrating staking, liquidity, and cash. Today, the account combines four functions:
Save and Earn. Hold assets in a self-custody vault and utilize staking and investment strategies.
Spend and Transfer. Pay using Cash and move funds across fiat and crypto rails.
Trade. Buy and sell cryptocurrencies, tokenized stocks, and metals, depending on local availability.
Borrow. Access liquidity via a dedicated Aave market with eligible collateral.
Ether.fi also offers corporate accounts for company treasuries and employee cards. Its client interface integrates several services built on partner infrastructure, including Aave lending and card payment rails. It is this vertical integration, and how all components create a feedback loop, that provides its strategic advantage.
The business model and end-user utility stand out for their practicality. Yield-bearing assets back collateralized borrowing, and loan proceeds can fund Cash spending without requiring asset sales. This generates fee income while reducing the need to transfer assets to other providers. Membership perks also encourage customers to stake ETHFI, ensuring staking value derives from all business lines. This makes Ether.fi not only a differentiated on-chain financial account but one with high stickiness.
Cash Spending Nearly Doubles
Paymentscan recorded January Cash monthly spending at $54.3 million, rising to $100.3 million in July, an increase of 85%.
Monthly active addresses reached 40,040, up 83% from 21,898. Spending per address remained relatively stable, moving from approximately $2,479 to $2,505. Monthly transactions per address decreased by 22%, while the average transaction amount increased by 29%.

The larger base of active users accounts for most of the spending growth.
Over the same period, the broader tracked market expanded by 81%. Cash's share moved from 9.5% to 9.7%, a relative increase of 2%. Cash kept pace with this rapidly growing category. Paymentscan discloses that its coverage includes self-reported off-chain data. The sample excludes portions of the card market.

Cash kept pace with its growing category.
Nexo has already combined borrowing and spending. KAST pairs cards with accounts and yields. Gnosis Pay supports self-custody spending. RedotPay leads current trading volume rankings on Paymentscan. However, the competitive opportunity lies in cross-service convenience. Contribution margins after rewards and repeat usage will determine the strength of this advantage.
How the Account Generates Fees
Cash monetizes spending through swipe fees. DefiLlama published an adapter estimating revenue at 1.38% of spend: every $1 billion in annual transaction volume implies $13.8 million in pre-cost revenue. Earn collects staking and vault fees. Trading adds trading fees. Borrowing takes a cut of the fees retained by its lending market.
A July 14 Aave proposal disclosed that ether.fi receives 80% of instance protocol fees, while Aave takes 20%. This split excludes loan principal and interest paid to lenders, with Ether.fi covering operational costs and risk management.
Based on revenue reported by DefiLlama across the four business lines, cumulative rolling 30-day annualized revenue reached $38.5 million as of August 30, with $17.6 million coming from Cash. Cash's annualized run rate nearly doubled since January 1, while tracked total revenue fell 22% due to reduced staking yields and a drop in ETH's price.

As staking yields weaken, Cash is diversifying revenue.
Cash's share of monthly revenue rose from 17% in January to 46% in July.

Cash captures a larger share of the shrinking total revenue.
What Was Released on August 13
The summer version released on August 13 announced tokenized stock and metal trading, alongside an integrated Aave market. The redesigned app added support for over 30 currencies and payment methods. These new features launched to both new and existing users on the day of release.
In this version, management reported over 500,000 members and an annualized trading run rate of $2 billion.
How Fees Flow to ETHFI
The foundation released the proposal on August 30. Voting concludes on September 3.
If approved, contributions from card, swap, and staking revenue will fund the foundation's weekly purchases via CoW Swap. Labs must first collect the fiat swipe fees, convert them to USDC, and then bridge the contributions on-chain. Based on the July example, the foundation contributes $1.33 million monthly, implying an annualized $16 million, pending approval and execution.
In its example, a $10,000 swap at a 0.5% fee generates a $50 fee. Labs retains $20. The remaining $30 is used to buy back ETHFI: $15 goes to the foundation vault, and $15 serves as user rewards.
The proposal also authorizes using up to 20 million vault ETHFI to cover reward shortfalls.
The foundation can adjust reward structures and fee splits, or alter the buyback pace.

Growing contributions increase purchasing power before reward distributions.
A 25% contraction would lower the same annualized funding anchor to $12 million; a 50% growth would raise it to $24 million. With the token price held constant at $0.55, $16 million could purchase approximately 29 million ETHFI. Higher prices result in fewer tokens purchased.
Cash Grows While ETHFI Lags Year-To-Date
Cash revenue and the token price have diverged this year. ETHFI rebounded 45% from August 13 to August 30 to reach $0.55, though it remains down 21% from January 1.
The price has recently bounced back above the 30-day and 90-day moving averages.
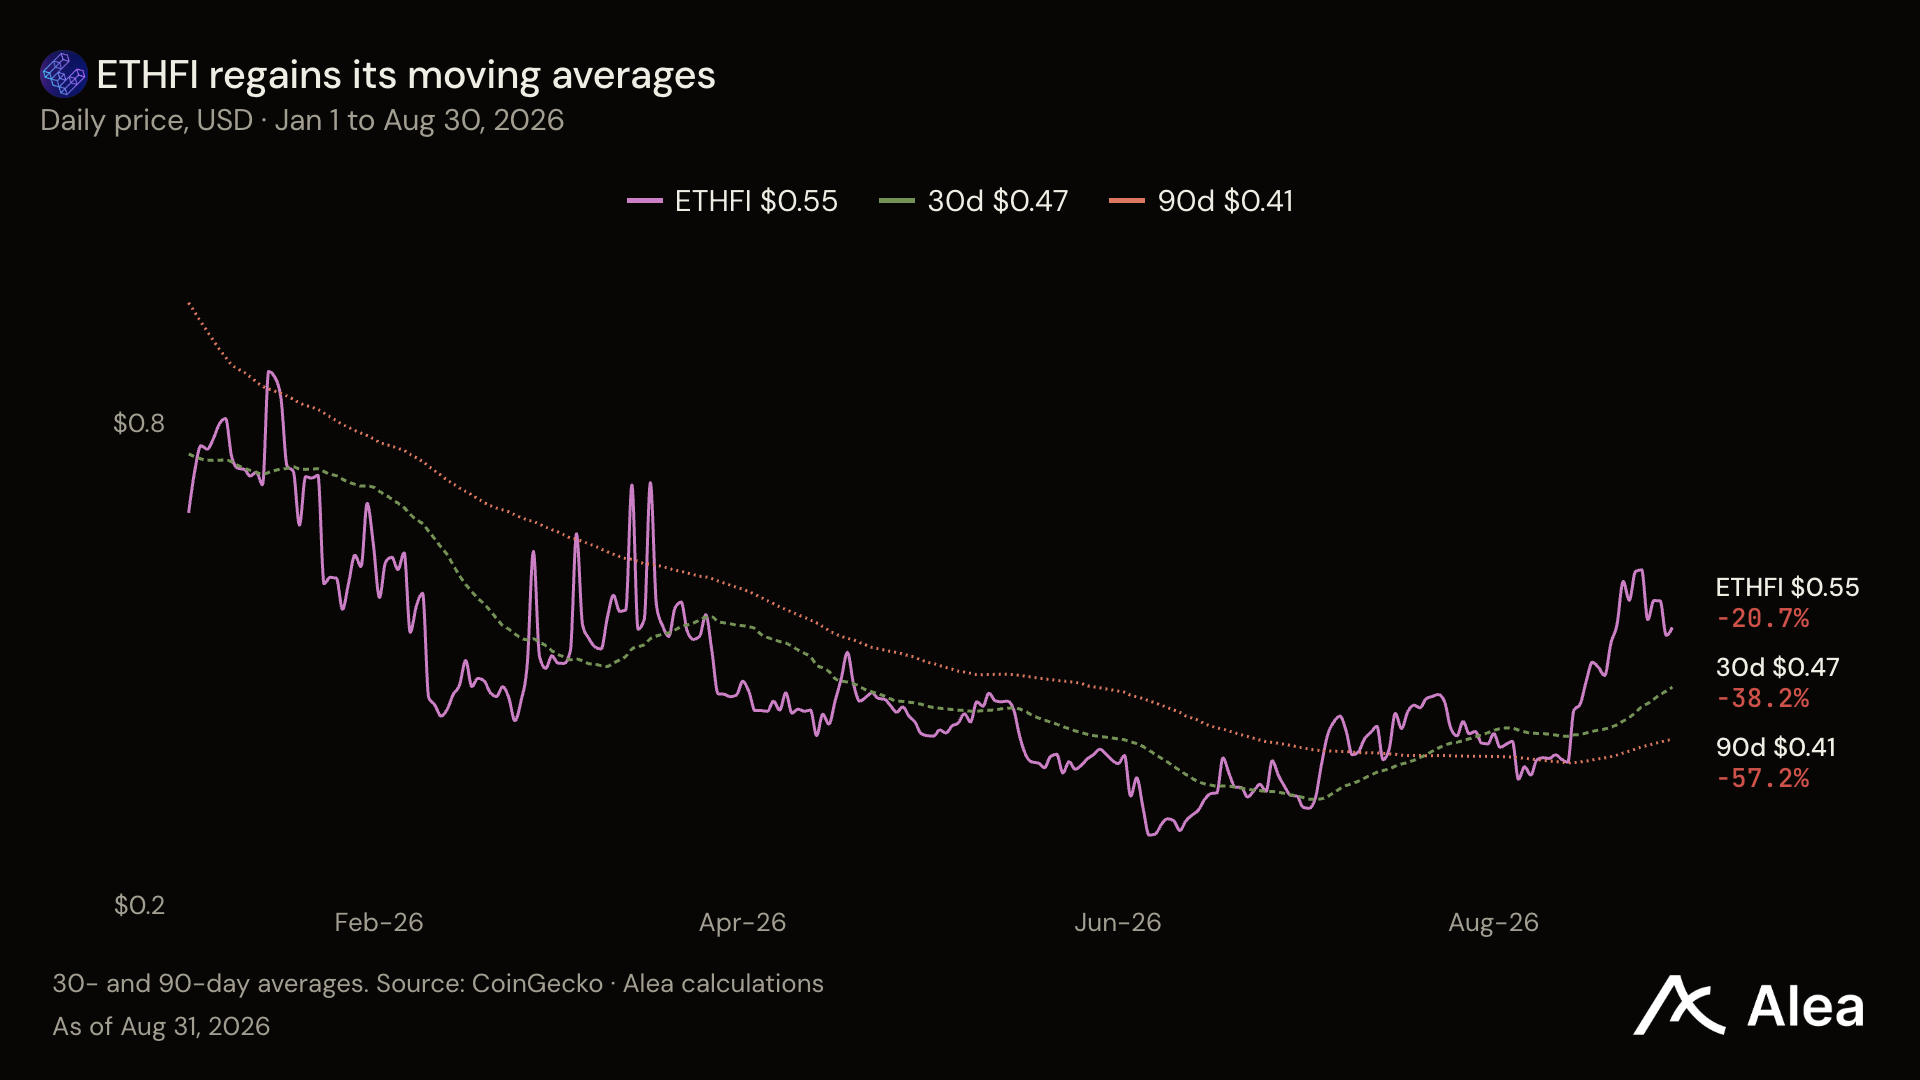
The August recovery still leaves ETHFI below its January starting point.
Against a 1 billion maximum supply, this price implies a reference valuation of $545 million, representing 14.2x trailing annualized revenue and 3.6x gross fees. Gross fees include staking rewards and card cashback, which do not accrue to ETHFI holders.

The multiple derived from gross fees sits significantly lower than that of protocol revenue.
The proposed $16 million annual funding anchor equals 2.9% of this reference valuation, excluding reward distributions. If contributions grow by 50%, this ratio reaches 4.4% at a constant price.
These ratios measure total capital capacity. ETHFI holders hold no equity claim on Labs.
Assuming a 10x revenue multiple, maintaining the $545 million valuation requires $54.5 million in annual revenue, which is 42% higher than the current run rate.
September 3 and Beyond
September 3: Voting ends. As of August 31, voting power stood at approximately 245,800 ETHFI, merely 25% of the 1 million required for quorum.
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @AleaResearch












