


Making Money by Solving AI’s “New Problems”: Ramp and Stripe’s New Business Playbook
Author: Simon Taylor
Compiled by: TechFlow
TechFlow Summary: AI brings more than efficiency gains; it also brings a new set of previously non-existent customer tasks: token spend, agent identity, and model routing. Ramp and Stripe have built new revenue pools around these tasks. Their valuation narratives are not just about growth, but a bet on being AI-native. Understanding this map of "new tasks" helps investors distinguish who benefits and who gets left behind.
🧠 AI created new customer problems
Solving these problems is where next-generation financial products take shape. Token spend, agent identity, and model routing barely existed before AI.

Ramp recently raised $750 million at a $44 billion valuation. It might not even need the money, but this round bought something bigger than impressive growth*. This round bought into a coherent narrative about becoming AI-native.
This story is credible because it is rebuilding itself around the customer tasks created by AI. For example, Router finds the lowest-cost, highest-quality model for each request, saving customers an estimated 40% in costs according to Ramp. Stripe is assembling a similar tech stack: payments at the base, Metronome handling usage-based metering and billing, and OpenRouter at the top routing traffic across 400+ models. It reportedly paid out over $7 billion to those top layers.
Every investor, especially growth investors, is looking for companies that benefit from AI's rapid acceleration and thus become more durable. They want to hold beneficiaries and avoid victims as much as possible.
I spoke with three founders this week. All three are closing on major funding rounds under the banner of being AI-native. And all three asked me roughly the same question:
How should we position ourselves as AI-native? What should our product look like?
They are asking about positioning. I think the answer lies in product.
This column is my answer.
Quick map:
Where you sit: Adopter, Beneficiary, or Native
The task ladder created by AI: Doing old tasks better; New tasks right next to the core; Unresolved new tasks
Why your agents need a distribution strategy
What to build now
Where you sit: Adopter, Beneficiary, or Native
The most useful idea from Clayton Christensen for this piece is: Customers don't buy your product; they hire it to get a job done.
Jobs to be done in finance include: reimburse my expenses, reconcile my invoices, help me manage fraud. These jobs predate AI. Modern models can execute some of them faster, cheaper, and with less human intervention, but when customers wake up, they still want the exact same outcome.
AI has also created a second class of jobs: monitor my token spend; route each inference request to the best model; let my agents make purchases without handing over full identity and bank account access.
No one had these jobs before AI brought these problems to light.
AI-native describes the product. AI-created describes the demand.
I think about becoming AI-native through a 2x2 matrix.
Jobs: Old customer jobs have always existed (like managing fraud), while AI-created jobs emerge alongside the technology (like managing my token spend).
Company: A company or product that existed before AI, or one that only exists because of AI.
Put them together, and it looks like this?
Old customer jobs
AI-created customer jobs
Existing companies / products
Nubank / NuFormer
Ramp and Stripe
Couldn't exist without modern AI
Harvey, Hebbia, and Rogo
OpenRouter and fal
Top-left is deep adoption. Nubank uses NuFormer to make better credit decisions, but underwriting is an ancient banking job.
Bottom-left is where Harvey, Hebbia, and Rogo sit: These products couldn't exist before modern models, yet they tackle legal and financial research jobs that have been around forever.
The right side is where tailwinds live. While AI gives customers something new to buy, Ramp and Stripe already have businesses going. OpenRouter and fal make sense only because inference became an industry.
This also means a company can occupy more than one quadrant. Ramp's spend product sits in the top-left. Its token dashboard and Router land in the top-right. Stripe's payment business is top-left; Metronome and OpenRouter drag it to the right side of the grid. Things rarely fit cleanly into a 2x2 matrix.
So let me throw another concept at you.
I find three labels work best to describe a company's stance:
Adopters use AI to serve needs they already have. Maybe they added a co-pilot. There is real value here. They can be faster, cheaper, and leaner, but the sales motion stays the same. Most SaaS companies that bolted on an agent fall into this bucket.
Beneficiaries do old jobs better and capitalize on new demand created next door by AI. Ramp or Stripe are the cleanest examples. Spend management remains the core job; token cost management and model routing are new pockets of revenue sitting adjacent.
Natives exist because of new demand. OpenRouter routes requests across 400+ models. fal runs generative media inference at scale. In a world without inference to sell, neither would have a business.
This matrix tells you where demand comes from.
Jobs tell you where opportunities might lie. Becoming AI-native is a ladder: the bottom is familiar, the top features brilliant unsolved challenges. So let's climb it together.
Premise: Run yourself with AI
AI-driven operating models change a company's shape, governance, and OS. Teams build extensions around employees, tap into internal data, share skills, and change who can do what. Product managers and designers start shipping code. Engineers move deeper into product. Teams build their own internal tools. (More in the AI Operating Models report.)
This is your ticket in. It lets you accelerate, but by itself, it won't change what you sell.
Level One: Old Jobs, Done Better with AI
Some AI-native products serve very old jobs. That doesn't dilute their native status.
Compliance screening, document and email reconciliation, legal research, and financial reporting were cumbersome paperwork before AI. Beacon, Sardine*, Gradient Labs, Harvey, Hebbia, and Rogo use modern models to synthesize hundreds of documents and data sources, then spit out answers or manage workflows. You literally could not have built these products a few years ago. But the jobs themselves are ancient.
I am an advisor to Sardine.
Level Two: New Jobs Right Next to the Core
If you do spend management, account management, or help people pay, old customer jobs remain, but new ones have popped up right beside them. Here are a few different flavors.
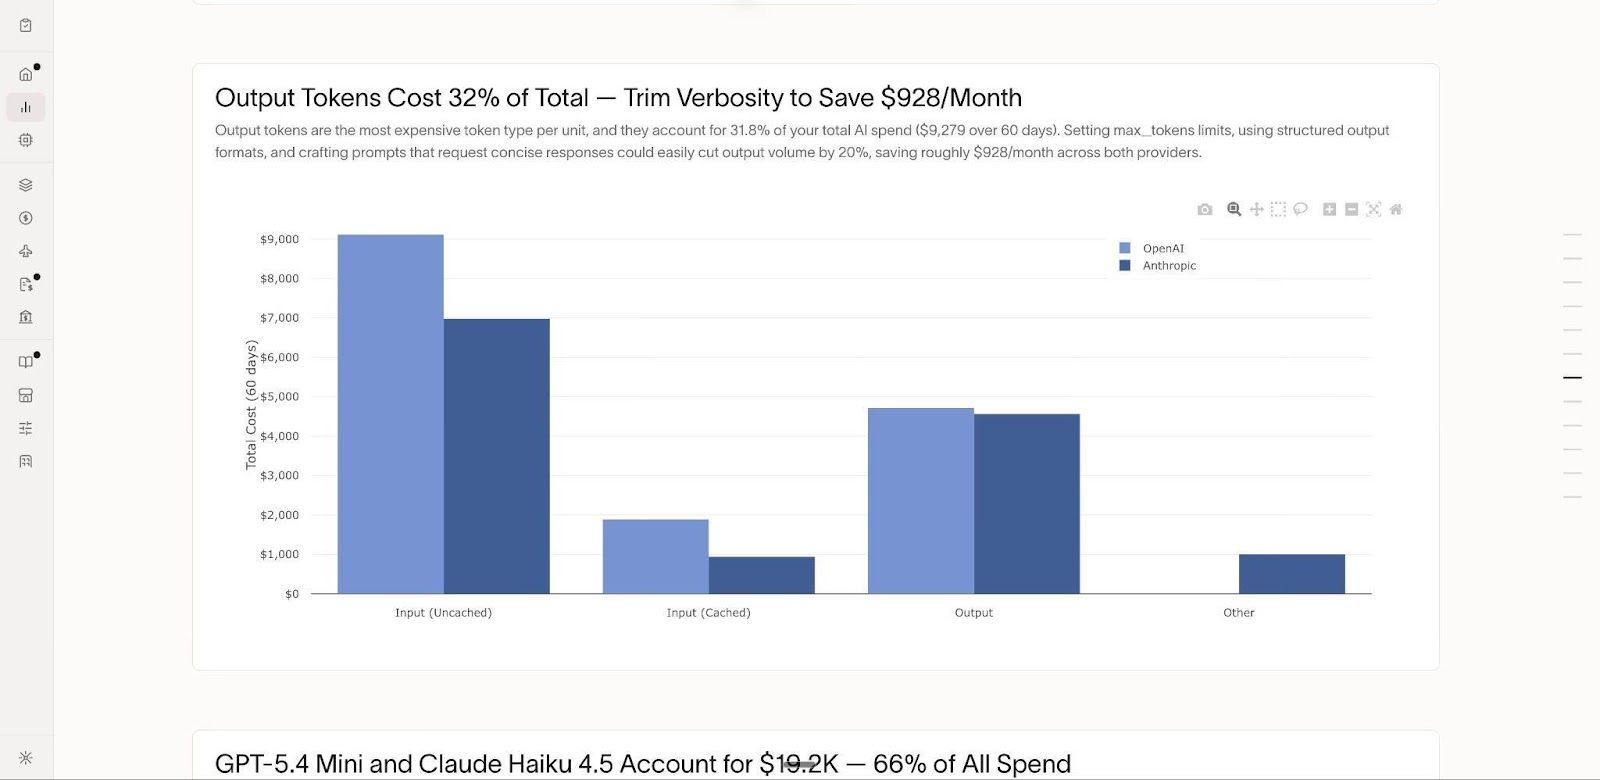
Job: Help me manage AI usage. Ramp's token dashboard is an AI-created job living inside an existing product. You might push back, saying cost dashboards aren't new. Vantage and Datadog have been pricing cloud and compute spend for years. The difference is the bill. Before AI gave you a token bill, no one needed to categorize, forecast, or split token costs between COGS and OpEx. On Ramp, AI token spend grew 20.7x between June 2025 and June 2026. Metronome now belongs to Stripe, sitting on the other end of the same job, handling metering and billing for this usage.
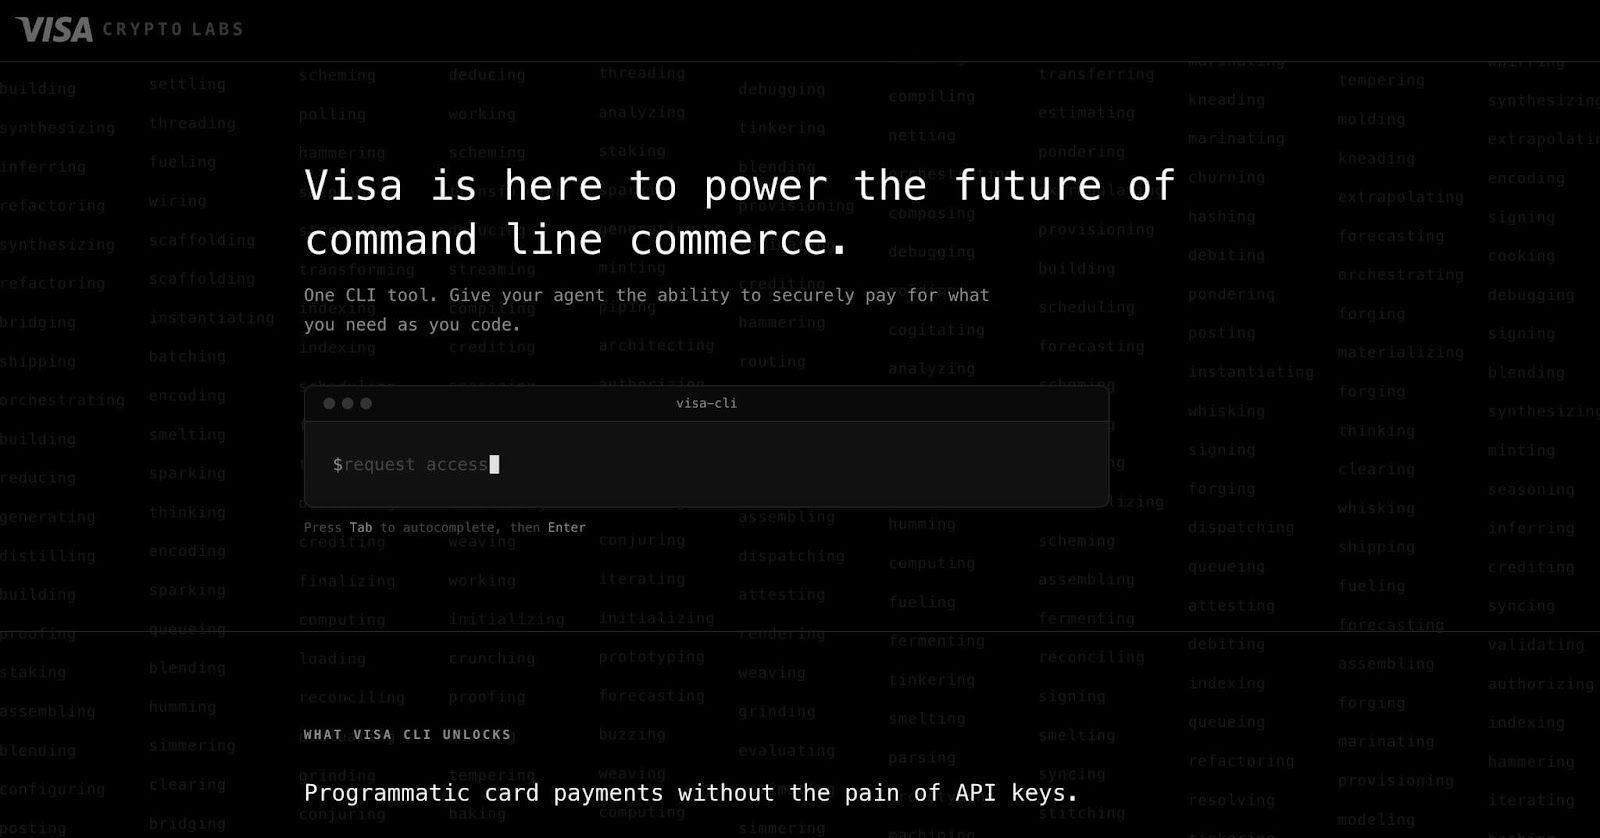
Job: Help my agent connect to your product and get things done. Companies like Mercury, Visa, and Ramp are rolling out command-line interfaces (CLIs). Legacy Stripe actually shipped its own CLI seven years ago. But since Claude Code launched, usage has exploded. A CLI is a user interface that uses a command line (terminal) rather than an app or webpage. Agents find these interfaces much easier to navigate. And they consume far fewer tokens using a CLI. For example, running the Ramp CLI in --agent mode returns the transaction as JSON, costing roughly 105 tokens. Running the same transaction in --human mode requires 280 tokens for formatted display. This is a product interface designed for "non-human customers."
Job: Help my store get discovered by AI agents. About a third of Gen Z now uses AI instead of Google to research what to buy. If your store and SKUs aren't there, you might be missing out. Companies like Shopify and WooCommerce, as well as payment service providers (PSPs) helping e-commerce merchants, are now optimizing for this space too.
AI has created an entire category of demand right beside your existing business. Your opportunity is to build interfaces that serve this demand. You don't need to pivot your entire business overnight.
But imagine a future where agents account for 80% to 90% of internet traffic, commerce, and the economy. If even half of that holds true, how would you reposition your company and narrative? What is the core unit of value you create? How does it apply to that customer?
In this thought experiment, we must abandon the mindset of treating AI as an add-on feature layered over existing business.
Level Three: New Work That Exists Because of AI
Some questions did not exist before the AI explosion. They stem from more than just simple AI usage.
How do I trust this agent with my data, or with the decisions it makes? We are entering a world where third-party developed agents will interact with your business. You need a way to ensure they are safe, reliable, privacy-compliant, and backed by a legal entity responsible for them. The simple pattern is an agent living inside a SaaS provider where you already have enterprise agreements. But agents are increasingly becoming the product itself. They might come from a lab like Anthropic, a startup, or an internal division. I see companies building or buying shells or control planes (like Primitive) to wrap these agents. Another approach is AIUC, which aims to underwrite and certify agents.
How do I trust this agent to transact? If an agent shows up in your store trying to buy something, how do you know its reputation, or who built it? Has the user verified that agent to make purchases? There are emerging standards right now, like Google's A2A, Visa's Trusted Agent Protocol, and FIDO building identity standards. But we are still in the very early days. Companies like Natural Payments, Skyfire, and A-comm are staking claims here. They handle the segment of the agent commerce workflow where agents actually move money.
How do I get cheaper inference and compute? Brex states that companies bring in their first open compute vendor within five months of incurring their first OpenAI or Anthropic API bill. Five months. One minute you are paying an API fee to a model lab. The next you are comparing Together AI, Fireworks, and Baseten. You decide where workloads run and ask finance how to hedge the costs. AI created a software supply chain, and capital stacks are now starting to build beneath it. Nvidia and Wall Street are trying to marshal $500 billion around this layer.
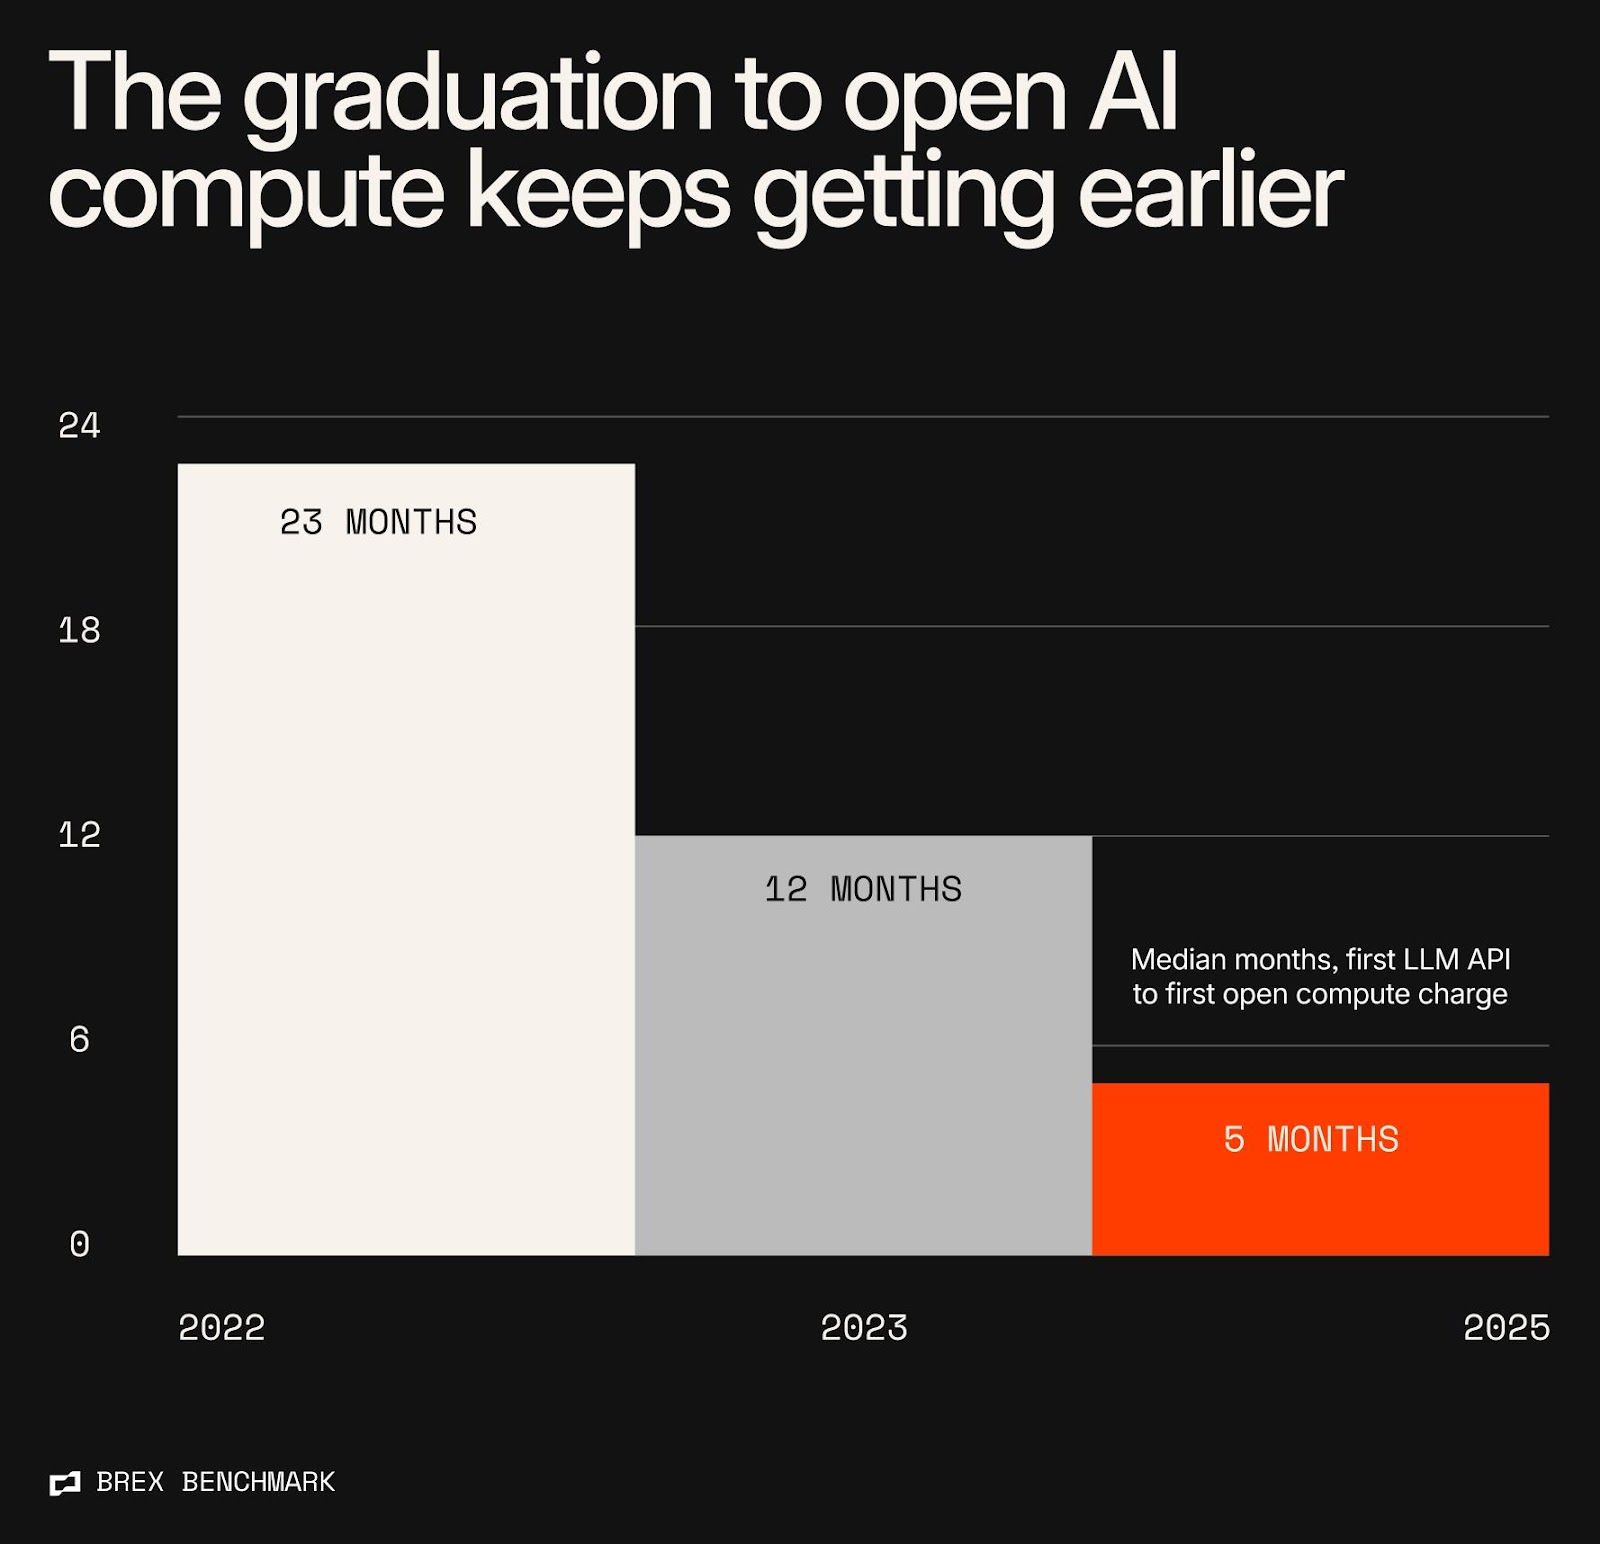
Source: Brex Benchmark; Brex card and bill payment data, January 2021 – June 2026
These jobs are bigger than features. They span product, data, identity, and capital. Once they span products, the question becomes which customer trusts who sits atop them.
Your agents need a distribution strategy
I don't want your agent. I want my agent integrated into your product.
Most enterprise customers will eventually run some form of control plane or shell: a single place to orchestrate the agents they own across the tools they use. The CFO's finance agent, the engineer's coding agent, and the ops team's procurement agent will budget, authorize, and observe from a layer above the products.
Consumers will have their version too. Whether it's Grokbot or Instinct, new consumer apps from OpenAI or Google, or Apple finally making Siri less terrible, there will always be something across products looking out for the user.
Garry Tan put the threat facing incumbent software perfectly:
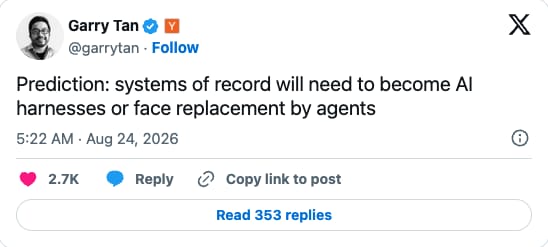
Systems of record already own the data, permissions, and distribution required for a shell. The problem is, a new orchestration layer can sit on top of them, turning every product underneath into a callable vendor.
This creates three strategic choices:
Own the orchestration. Become the place where customers view, authorize, and manage every agent.
Own a trusted control point. Even if others own the shell, identity, reputation, routing, procurement, and settlement retain value.
Become the easiest-to-call product for every major shell. CLIs, APIs, and agent interfaces are distribution. (This will be the correct answer for more of you than you think)
Salesforce and core banking systems won't easily give up the sticky wedges they already hold. This isn't purely aggregation theory. Systems of record can become shells; experts can own control points; products can distribute through all of these.
This tension is the whole point. The prize could be the control plane. Or it could be the indispensable component every control plane needs.
What to build now, and the unsolved puzzles
Back to those three founders I spoke with.
The answer is always the job. Positioning follows product.
Find the jobs AI is creating right beside the value you already deliver. Build interfaces for them.
Then decide how it distributes. You can own the shell, house a trusted control point inside it, or become a product that elegantly gets called from every shell.
This is what reinventing yourself looks like. You start by running yourself with AI. You use it to do old jobs better. Then you climb toward the jobs that didn't exist before models gave customers new problems.
Ramp hit $44 billion not because expense management is its absolute best use case. It got there because investors believe AI will continuously spawn new demand right next to the core. And Ramp has the speed to capture it.
Pick the job. Pick the interface. Give it distribution.
* (By fintech standards, Ramp's growth is absurd: TPV grew 170% year-over-year through March, the fastest pace in three years, while its business has scaled 20x.)
Join TechFlow official community to stay tuned
Telegram:https://t.me/TechFlowDaily
X (Twitter):https://x.com/TechFlowPost
X (Twitter) EN:https://x.com/BlockFlow_News
 @sytaylor
















