


Bitcoin Mining Companies Go All-In on AI, What's the Cost?
Written by: Prathik Desai
Compiled by: Luffy, Foresight News
Over the past year, every top listed Bitcoin miner has faced a survival crisis. Looking at financial reports, it can be seen that they are shedding the identity of "miners".
Now they have repackaged and repositioned themselves, calling themselves "energy infrastructure platforms," "vertically integrated AI cloud service providers," or "digital infrastructure companies built on electricity, land, and computing power".
Behind this rebranding lies a shift in revenue structure; corporate market capitalizations have surpassed their valuations when they were purely Bitcoin mining companies.
On the surface, the story looks beautiful. Struggling miners seized the opportunity, embraced the exploding demand for AI inference computing power, and found a way to save themselves. But if viewed from a broader perspective, they are also giving up something crucial.
This article will explain why miners making a 180-degree turn and completely departing from Bitcoin mining may backfire on them in the future.
What Caused This Transformation?
In April 2024, the Bitcoin block reward halving forced miners to make a choice: either mine Bitcoin and hold coins waiting to sell at high prices, or modify hardware and turn to High-Performance Computing (HPC) to diversify business. In October 2024, Bitcoin rose from less than $70,000 all the way up, touching $124,000 in October 2025. This market trend led some miners to choose to continue mining and accumulating the Bitcoin produced.
But the market liquidation event on October 10 saw the crypto market lose $19 billion in market cap within 24 hours, triggering a downward cycle that has not yet fully recovered.
The current Bitcoin price is nearly halved compared to last October's high, at about $63,000. At this price, selling Bitcoin after mining is almost unprofitable. Bitcoin mining costs are affected by both electricity prices and network-wide difficulty. Comprehensive mining costs rose from about $40,000 in February 2024, reaching $90,000-$110,000 in the October 2025‑July 2026 interval; by August this year, Bitcoin comprehensive mining costs hit a new high, soaring to $140,000.
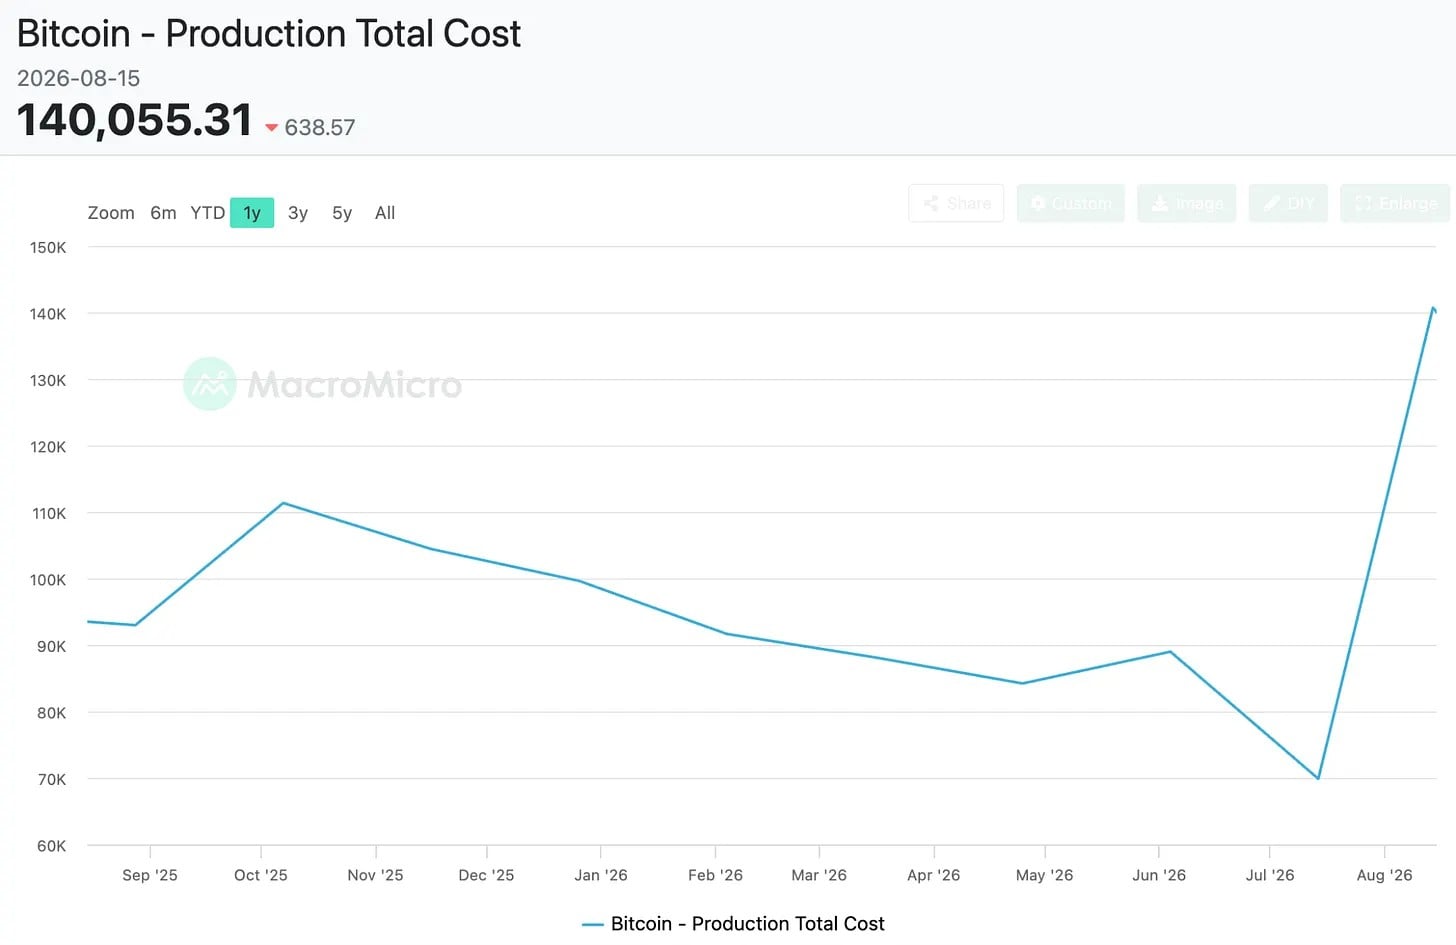
Source: MacroMicro
During the same period when the Bitcoin mining environment continued to deteriorate, a large amount of capital flooded into the AI inference track.
Bitcoin miners use ASIC chips to run complex algorithms to obtain block rewards. This hardware infrastructure is highly similar to the underlying conditions required for high-performance computing and AI inference. This allows miners to transform into AI inference without starting from scratch, significantly lowering the threshold. For miners wanting to find a profitable way out, turning to AI seems natural.
Almost the entire listed mining sector collectively changed direction. Changes in revenue structure over the past few quarters intuitively reflect the scale of this transformation.
Taking Core Scientific as an example: In the second quarter of 2025, data center hosting services for AI and high-performance computing generated quarterly revenue of only $10.6 million; during the same period, revenue from mining and selling coins was $62.4 million. Twelve months later, the positions of the two almost completely reversed. In the second quarter of 2026, hosting business revenue was $136.7 million, while mining revenue shrunk by 65% to $21.5 million.
The proportion of hosting business to the company's total revenue soared from 14% last year to 83%.
TeraWulf's high-performance computing leasing revenue has accounted for 71% of total revenue. This business had no revenue in the same period last year, reaching $32 million in Q2 2026; during the same period, crypto asset mining revenue shrunk by about 75%, leaving only $13 million.
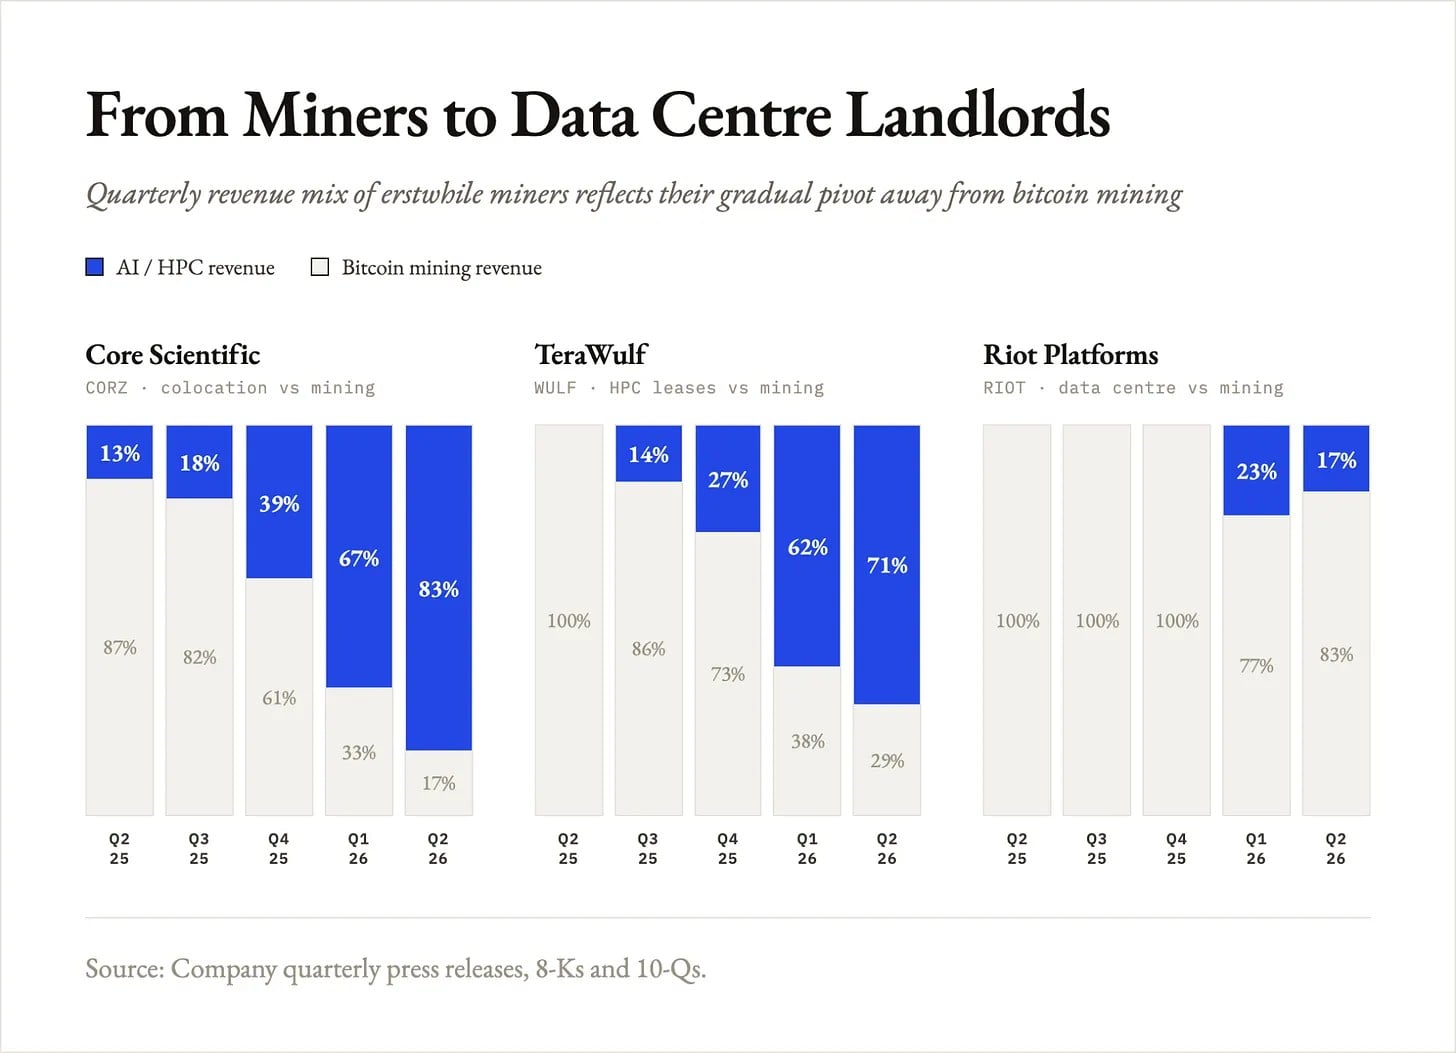
A large number of miners are also modifying existing mining plants and hardware to host AI and high-performance computing business.
A Land Grab Worth Warning About
Shifting from Bitcoin mining to AI computing power has evolved into a collective rush. In addition to allocating existing capacity to AI, former Bitcoin miners are frantically seizing electricity and land, signing a large number of demand orders. The total scale of contracts already landed reaches the level of tens of billions of dollars.
Core Scientific has committed up to 2.5GW of available computing capacity to AMD and CoreWeave, with total potential revenue over the contract period exceeding $24 billion. Hut 8 holds 949 MW of signed computing power, with a contract base value of $26.6 billion, and simultaneously secured $7.5 billion in new project financing.
TeraWulf signed a 20-year lease agreement worth about $19 billion with Anthropic, and acquired a gigawatt-level park in Kentucky to undertake computing power demand. In the past six months, Riot Platforms completed multiple leases, totaling 241 MW, corresponding to a contract scale of about $10 billion. Just last week, IREN delivered the first batch of AI cloud deployment nodes to Microsoft; this five-year contract is worth $9.7 billion; it simultaneously reached a 5GW cooperation with NVIDIA, continuing to acquire power sites in Texas and Spain to supply computing power demand.
This series of large contracts ignited market enthusiasm. Compared with miners' past business, signing a 20-year lease with top cloud vendors means more stable cash flow. After mining continued to lose money for a whole year, locking in contracts up to fifteen years long looks like a solid reality.
But many market commentaries underestimate the hidden risks therein.
Although mining is full of suffering, Bitcoin mining possesses a characteristic that AI hosting business does not have: a self-healing mechanism. When mining is unprofitable, miners will shut down machines; when enough miners exit, Bitcoin network-wide difficulty automatically adjusts downward. Miners who remain, with the same equipment and same electricity costs, can obtain higher returns.
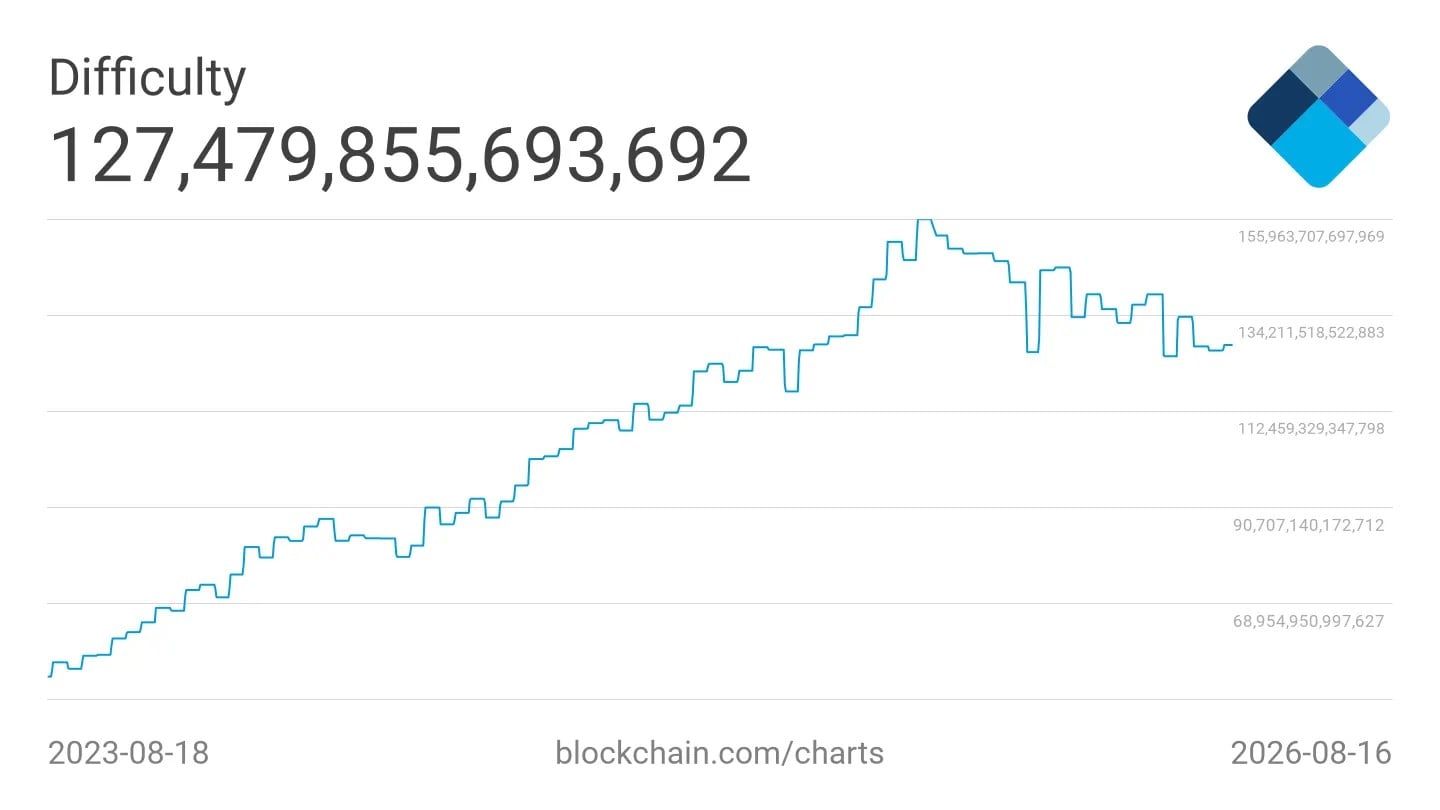
After a large number of miners switched to the AI track, Bitcoin network-wide difficulty has fallen from a peak of about 156 trillion in 2025 to 127.5 trillion. Every company that withdraws from mining is making the mining returns for remaining miners higher.
But the AI computing power industry does not have this automatic adjustment mechanism. If a large number of players flood in, computing power supply will exceed demand, and prices will be continuously pressed down.
Although the overall demand for AI computing power is rising, prices are likely to fall instead of rise — this seems contrary to basic economic common sense. In fact, several AI companies have already lowered service pricing. In the early stage of the industry, hardware and supporting resources were scarce, and service providers could charge high premiums; now major cloud vendors around the world are competing for megawatt-level power resources, and scarcity attracts a large number of Bitcoin miners and data center manufacturers to expand capacity aggressively. Once new supply fills the supply-demand gap, computing power prices will decline rapidly.
When prices fall back, the 15‑20 year long-term lease contracts signed by miners at current high prices will look costly in retrospect.
There is another tricky part to this transformation: this road is basically one-way. Transforming mining machine rooms into AI computing power parks is simple; power infrastructure is already complete. But once you replace ASIC miners with H100 GPUs and sign a lease up to twenty years long, you will be firmly bound by this contract for the next twenty years and will no longer be able to easily switch back to mining.
In the future, when the market cycle reverses, Bitcoin prices break away from the $60,000 low, coupled with a decline in network-wide difficulty, mining is bound to become profitable again. At that time, former miners who have completely transformed, bound by multi-year long-term lease contracts, can only watch opportunities slip away. Worse, if the actual returns from AI computing power fall short of the beautiful expectations at the time of signing, a double blow will follow.
So should miners not transform to AI and honestly wait for the mining cycle to reverse? I don't think so. For most enterprises, transformation is a choice forced by survival. Comprehensive mining costs are as high as $140,000, while the coin price is only $63,000; continuing to mine is not commercially viable, AI is the only lifeline at hand.
But the will to survive will drive enterprises to make extreme choices. The risk lies precisely with those players who go all in on AI: forced by survival pressure, they completely give up Bitcoin mining, destroy/replace all ASIC miners, and lock in decades-long contracts in an emerging industry that will still experience price corrections.
However, not all miners chose a 180-degree complete turn; some enterprises have moved more cautiously.
Those Holding Hedging Options Have the Advantage
Listed mining enterprise Marathon Digital, which holds the largest Bitcoin treasury, took a cautious route. In the second quarter of 2026, it sold 30% of its Bitcoin holdings to reduce debt, but it did not give up Bitcoin mining equipment, instead choosing another way to fund its artificial intelligence expansion.
MARA used its remaining Bitcoin as collateral to obtain $150 million in funds through a 2026 credit line to fund AI business expansion. As of June 30, its balance sheet still held over 35,000 Bitcoins, while maintaining mining business with flexibly schedulable loads.
Hut 8 also did not give up mining. It spun off its Bitcoin mining business into a new subsidiary American Bitcoin Corp absolutely controlled by the parent company, while the parent company shifted focus to high-performance computing and AI infrastructure.
By keeping miners running and maintaining Bitcoin inventory, these enterprises hold an option that those who completely went all in on transformation gave up. When mining becomes profitable again, they can switch power loads back to mining; while enterprises already deeply bound to AI long-term contracts can only look on from the sidelines.
Treating old mining business as a burden and going all in on AI computing power is equivalent to betting on an unverified future. But historical laws are not hard to predict: chips, computers, smartphones, with every emerging technology as the industry matures, products will continuously decrease in price; the AI computing power industry has already shown signs of price loosening.
Companies like Marathon and Hut8 did not miss the AI bonus. They did not liquidate everything to purchase GPUs, but retained a portion of mining capacity and Bitcoin inventory, treating AI as a diversified layout rather than betting all capital on a track that is not yet mature and will still experience price revaluation. As long as ASIC miners are still there, when mining returns are higher and AI computing power premiums fade, they can switch loads back to mine Bitcoin.
From a more macro perspective, these companies are essentially power operators, only the hardware loaded on top is ASIC miners or H100 graphics cards. Enterprises that can flexibly schedule power resources between mining and AI computing power based on which business yields higher returns will not be completely manipulated by market cycles and market narratives.















